


Forget the Recent Delivery Beat: Here's the Key Number That Will Decide Investors' Reaction to Tesla's Earnings
Key Points
Multiple factors are influencing Tesla's margins, both positively and negatively.
Long-term margin improvement may depend on production scale and new technologies.
- These 10 stocks could mint the next wave of millionaires ›
Tesla's (NASDAQ: TSLA) 486,532 vehicle deliveries in the third quarter exceeded Wall Street estimates, and the market responded positively. Still, the same thing happened with the big deliveries "beat" in the second quarter, only for second-quarter earnings to disappoint on the margin front. As such, the key metric to monitor in Tesla's upcoming earnings report is its gross margin. Here are the factors working for and against it.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The cleanest number to follow is Tesla's automotive gross margin excluding regulatory credits. The credits are variable and can't be treated as a run-rate item. The first chart below shows the sequential decline from Q1 to Q2. It was a disappointing result and raised concerns that Tesla's profit margins were in a structural decline, particularly concerning at a time when its free cash flow is negative.
Management discussed margin performance on the earnings call with analysts and in its Securities and Exchange Commission (SEC) filings. CFO Vaibhav Taneja discussed commodity price increases and rising subvention costs as interest rates have risen this year. Subvention costs are the costs of providing promotional financing for buyers, in other words, discounts.
In addition, in the SEC filing, Tesla noted: "Average cost per unit was relatively consistent due to unfavorable sales mix and a negative impact from the weakening of the United States dollar when compared to foreign currencies year over year," in the first six months. A "consistent" cost per unit is actually disappointing, considering Tesla sold 16% more vehicles in the first half of 2026 than in 2025, and unit costs should drop with increased deliveries/production.
Putting these facts together, it's understandable that investors are concerned with what Tesla's gross margin might be in the third quarter.
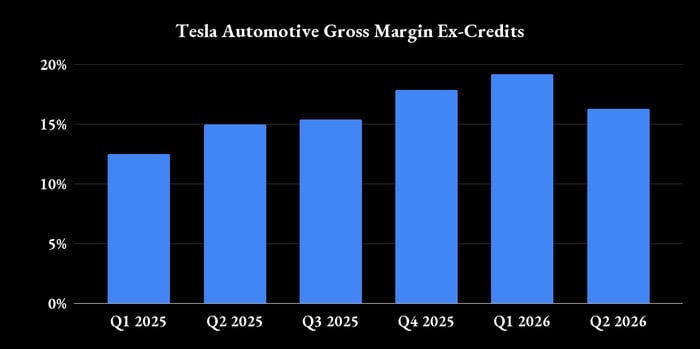
Data source: Tesla presentations. Chart by author.
Positive factors for Tesla's gross margin
There are three factors potentially working in Tesla's favor and three working against it. On the plus side:
- Tesla delivered slightly more vehicles in the third quarter than in the second (486,532 vs. 480,126), which, in theory, should lead to a lower cost per unit.
- Tesla delivered significantly fewer "other models" in the third quarter than in the second quarter (8,295 to 12,364), and these lower-volume models (including the S, X, Cybertruck, and Semi) are likely to be lower-margin.
- It's possible that the subvention costs (discounting) that hit margins in the second quarter were due to Tesla's aggressive inventory reduction. The chart below shows a large drop in days of supply in inventory between the first and second quarters, and a much more moderate drop between the second and third quarters. It's possible Tesla wasn't so aggressive in discounting in the third quarter.
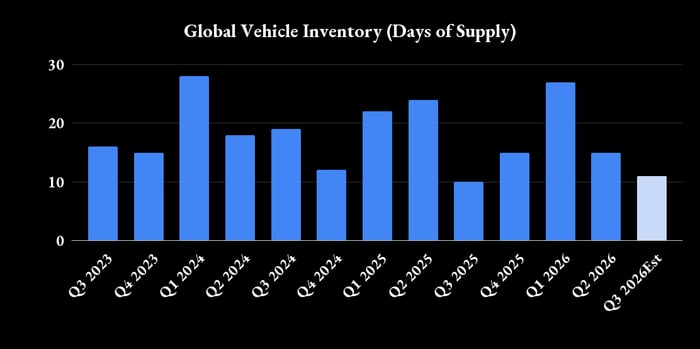
Est = estimate. Data source: Tesla presentations. Chart and Q3 2026 estimate by author.
Three factors working against Tesla's margins
On the other side of the argument:
- Interest rates have risen throughout the year, so the cost of subvention was likely to be higher in the third quarter, all things being equal.
- It's unclear what was in the inventory Tesla cleared in the third quarter. If it were older, less valuable models, then it may have had to aggressively discount them and erode margins in the process.
- Pricing could be an issue, as Tesla may well be selling relatively more in geographies where it competes with price-competitive Chinese electric vehicle manufacturers, rather than in the U.S.
Image source: Tesla.
What to expect in Tesla's report
The primary question is whether gross margin will increase sequentially. However, the secondary question is whether any of the numbers that might cause it to fall reflect a larger trend? In other words, if gross margin declines again, is it a sign that Tesla's margins are structurally declining?
The first question will drive the market's reaction to the results, and the second will guide the long-term. My guess would be a slight decline, but long-term gross margins will improve as production scales up for the Y and 3, with the added value of Tesla's self-driving shining through as the robotaxi rollout expands significantly next year.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Nvidia: if you invested $1,000 when we doubled down in 2009, you’d have $596,081!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $64,217!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $379,123!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, available when you join Stock Advisor, and there may not be another chance like this anytime soon.
See the 3 stocks »
*Stock Advisor returns as of October 11, 2026.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Tesla. The Motley Fool has a disclosure policy.
Recommended Articles


