


3 Reasons to Buy Reddit Stock This Week
Key Points
Reddit reports its latest quarterly results on Thursday afternoon.
There are valid concerns, but engagement and improving monetization continue to deliver monster growth.
Reddit stock is trading near its lowest forward earnings valuation as a public company. That's opportunity knocking.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
It's showtime for Reddit (NYSE: RDDT) and its investors. Shares of the company behind the popular online forum with more than half a billion users reports its third-quarter results after Thursday's market close.
Expectations are high. The stock price is low. There are some pretty good reasons to be hopeful for a big bounce on Friday, but hold your optimism in check. There are still some serious red flags waving in the wind. Still, I think it's good to warm up to the "community of communities" platform operator. Let's break down the reasons it could be a good buy this week ahead of its telltale financials.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
1. Reddit is historically cheap
Reddit stock has gone cold after a pair of monster rallies since going public in early 2024. The shares are trading 37% lower in 2027, down nearly half from their peak 13 months ago.
A stock doesn't slide in a vacuum. There are some potential potholes to watch for -- and I will get there, eventually -- but few things excite me as much as a stock that's sliding despite strong fundamentals. Reddit's business is booming.
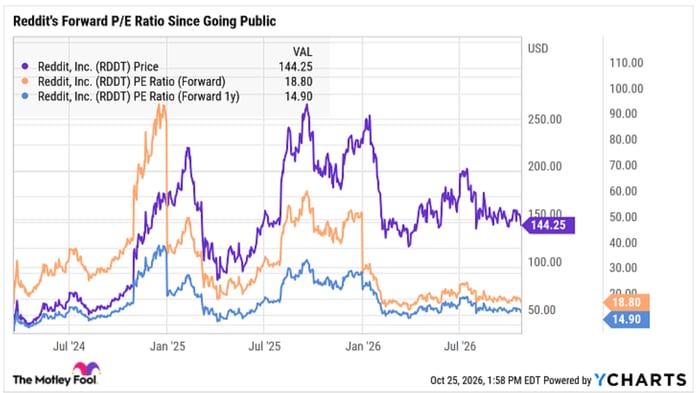
Revenue soared 61% in Reddit's latest quarter, its eighth consecutive quarter of better than 60% top-line growth. Earnings, adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA), and free cash flow more than doubled. You would think that the price of admission for this high-octane performance would be a healthy market premium. Spoiler alert: Reddit is cheaper than you think.
RDDT data: YCharts.
Reddit is now trading for almost 20 times next year's earnings, but less than 15 times the bottom-line target for 2028. This is near a historical low for Reddit, admittedly, given its short time as a public company. Growth should slow from here, but shouldn't a company posting this kind of growth be worth a healthy premium to the market?
2. Reddit is an earnings season beast
Reddit has now gone through 10 earnings seasons as a publicly traded company. It has consistently topped Wall Street revenue and profit targets. But that doesn't mean stretching that winning streak to 11 will send the shares higher.
Reddit stock has fallen the day after reporting quarterly results in roughly half of its updates. Sometimes there are valuation concerns. With that off the table now, the deal-breaker has been a lack of long-term visibility.
You would think a company growing its business at a 61% clip in its latest quarter wouldn't have top-line pressure points, but check out the average revenue per user (ARPU) for its logged-in U.S. daily active uniques. This group represents less than 5% of its 514.6 weekly active uniques worldwide, but it's Reddit's most lucrative regulars. This base grew to 23.1 million at the end of June, up just 1% from 22.9 million a year earlier and a sequential dip from the 23.2 million it peaked at in March.
There are concerns about how Reddit's licensing deals with AI giants will fare as they come up for renewal. Reddit's stronghold on free organic search traffic will face challenges as search engines continue pushing AI responses to questions Reddit's forums have historically answered.
My money is still on Reddit. The fundamentals don't match the downticks. Over the past three months, the stock has tumbled 15%. In that same time, analysts have boosted per-share profit targets from $4.98 to $5.39 for this year and from $6.53 to $7.10 by 2027.
3. Growth finds a way
Reddit's guidance three months ago called for $860 million to $870 million in revenue for the quarter it will discuss on Thursday afternoon. That represents 47% to 49% top-line growth, ending its two-year run of at least 60% quarterly revenue growth. Analysts see revenue slowing to 32% next year. Those same market pros feel that earnings will grow faster.
I can't deny the deceleration, but Reddit has made a habit of introducing conservative guidance that it can easily exceed. The "beat and raise" performances haven't even been close. Reddit has landed between 30% and 72% above Wall Street's profit targets over the past four quarters.
In the meantime, Reddit stock has moved lower despite its index inclusion in August and rising revenue and profit estimates. With monetization efforts improving both here and abroad and initial success with its Reddit Max AI-powered ad campaign platform, it may be a welcome surprise to see more good news than bad this week despite all of the recent downticks.
Should you buy stock in Reddit right now?
Before you buy stock in Reddit, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Reddit wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 26, 2026.
Rick Munarriz has positions in Reddit. The Motley Fool has positions in and recommends Reddit. The Motley Fool has a disclosure policy.
Recommended Articles


