


The Fed will sit still on October 28 — but 100 of 100 economists now expect a December hike

Mitrade Insights — The market and the forecasters now agree on October and disagree about nothing: the Fed will hold the funds rate at 3.75-4.00% on October 28, and the live debate has moved to December. A Reuters poll run October 16-20 found 94 of 100 economists expecting no change on October 28 — and all 100 expecting a hike in December, against fewer than half who said so a month earlier. CME FedWatch was pricing roughly 17% for October and 82.8% for December as of October 20. The interesting part is not the October meeting; it is what a unanimous December call does to a market that has spent seven weeks pricing a soft landing.
1. How the consensus flipped
The September-to-October reversal was driven by the data, not by a change of Fed rhetoric. September CPI came in at 3.7% with core at 2.6% year on year, and September producer prices posted their biggest increase in years — the release that pushed October hike odds up to more than 40% before the Fed went quiet. September payrolls were soft, and September housing starts fell 5.2% to 1.221 million with permits at a three-and-a-half-year low of 1.400 million, which took the pressure off an October move.
Since then the Fed has deliberately said nothing: the central bank has been in its pre-meeting blackout since October 17, and Chair Kevin Warsh's speech in Bangkok on Friday October 16 was the last scheduled word — no signal on the month, only a reference to "synchronous tightening" by central banks around the world.
The survey medians are where it gets uncomfortable. About 60% of forecasters see the policy rate peaking at 4.00-4.25%, but 38 of 92 expect at least two further increases — up from one in five in the September survey. The same medians have PCE inflation staying more than 100 basis points above the 2% target for several quarters and not returning to target until at least 2028. Morgan Stanley's US chief economist Michael Gapen put the asymmetry plainly: "The risks are in the direction of a Fed that ultimately needs to hike rates more than we expect." UBS's Simon Penn, writing in late September, expected December rather than October; RSM's Joseph Brusuelas saw little sign of disinflation and more than one further hike.
2. The five dates that decide the rest of the year
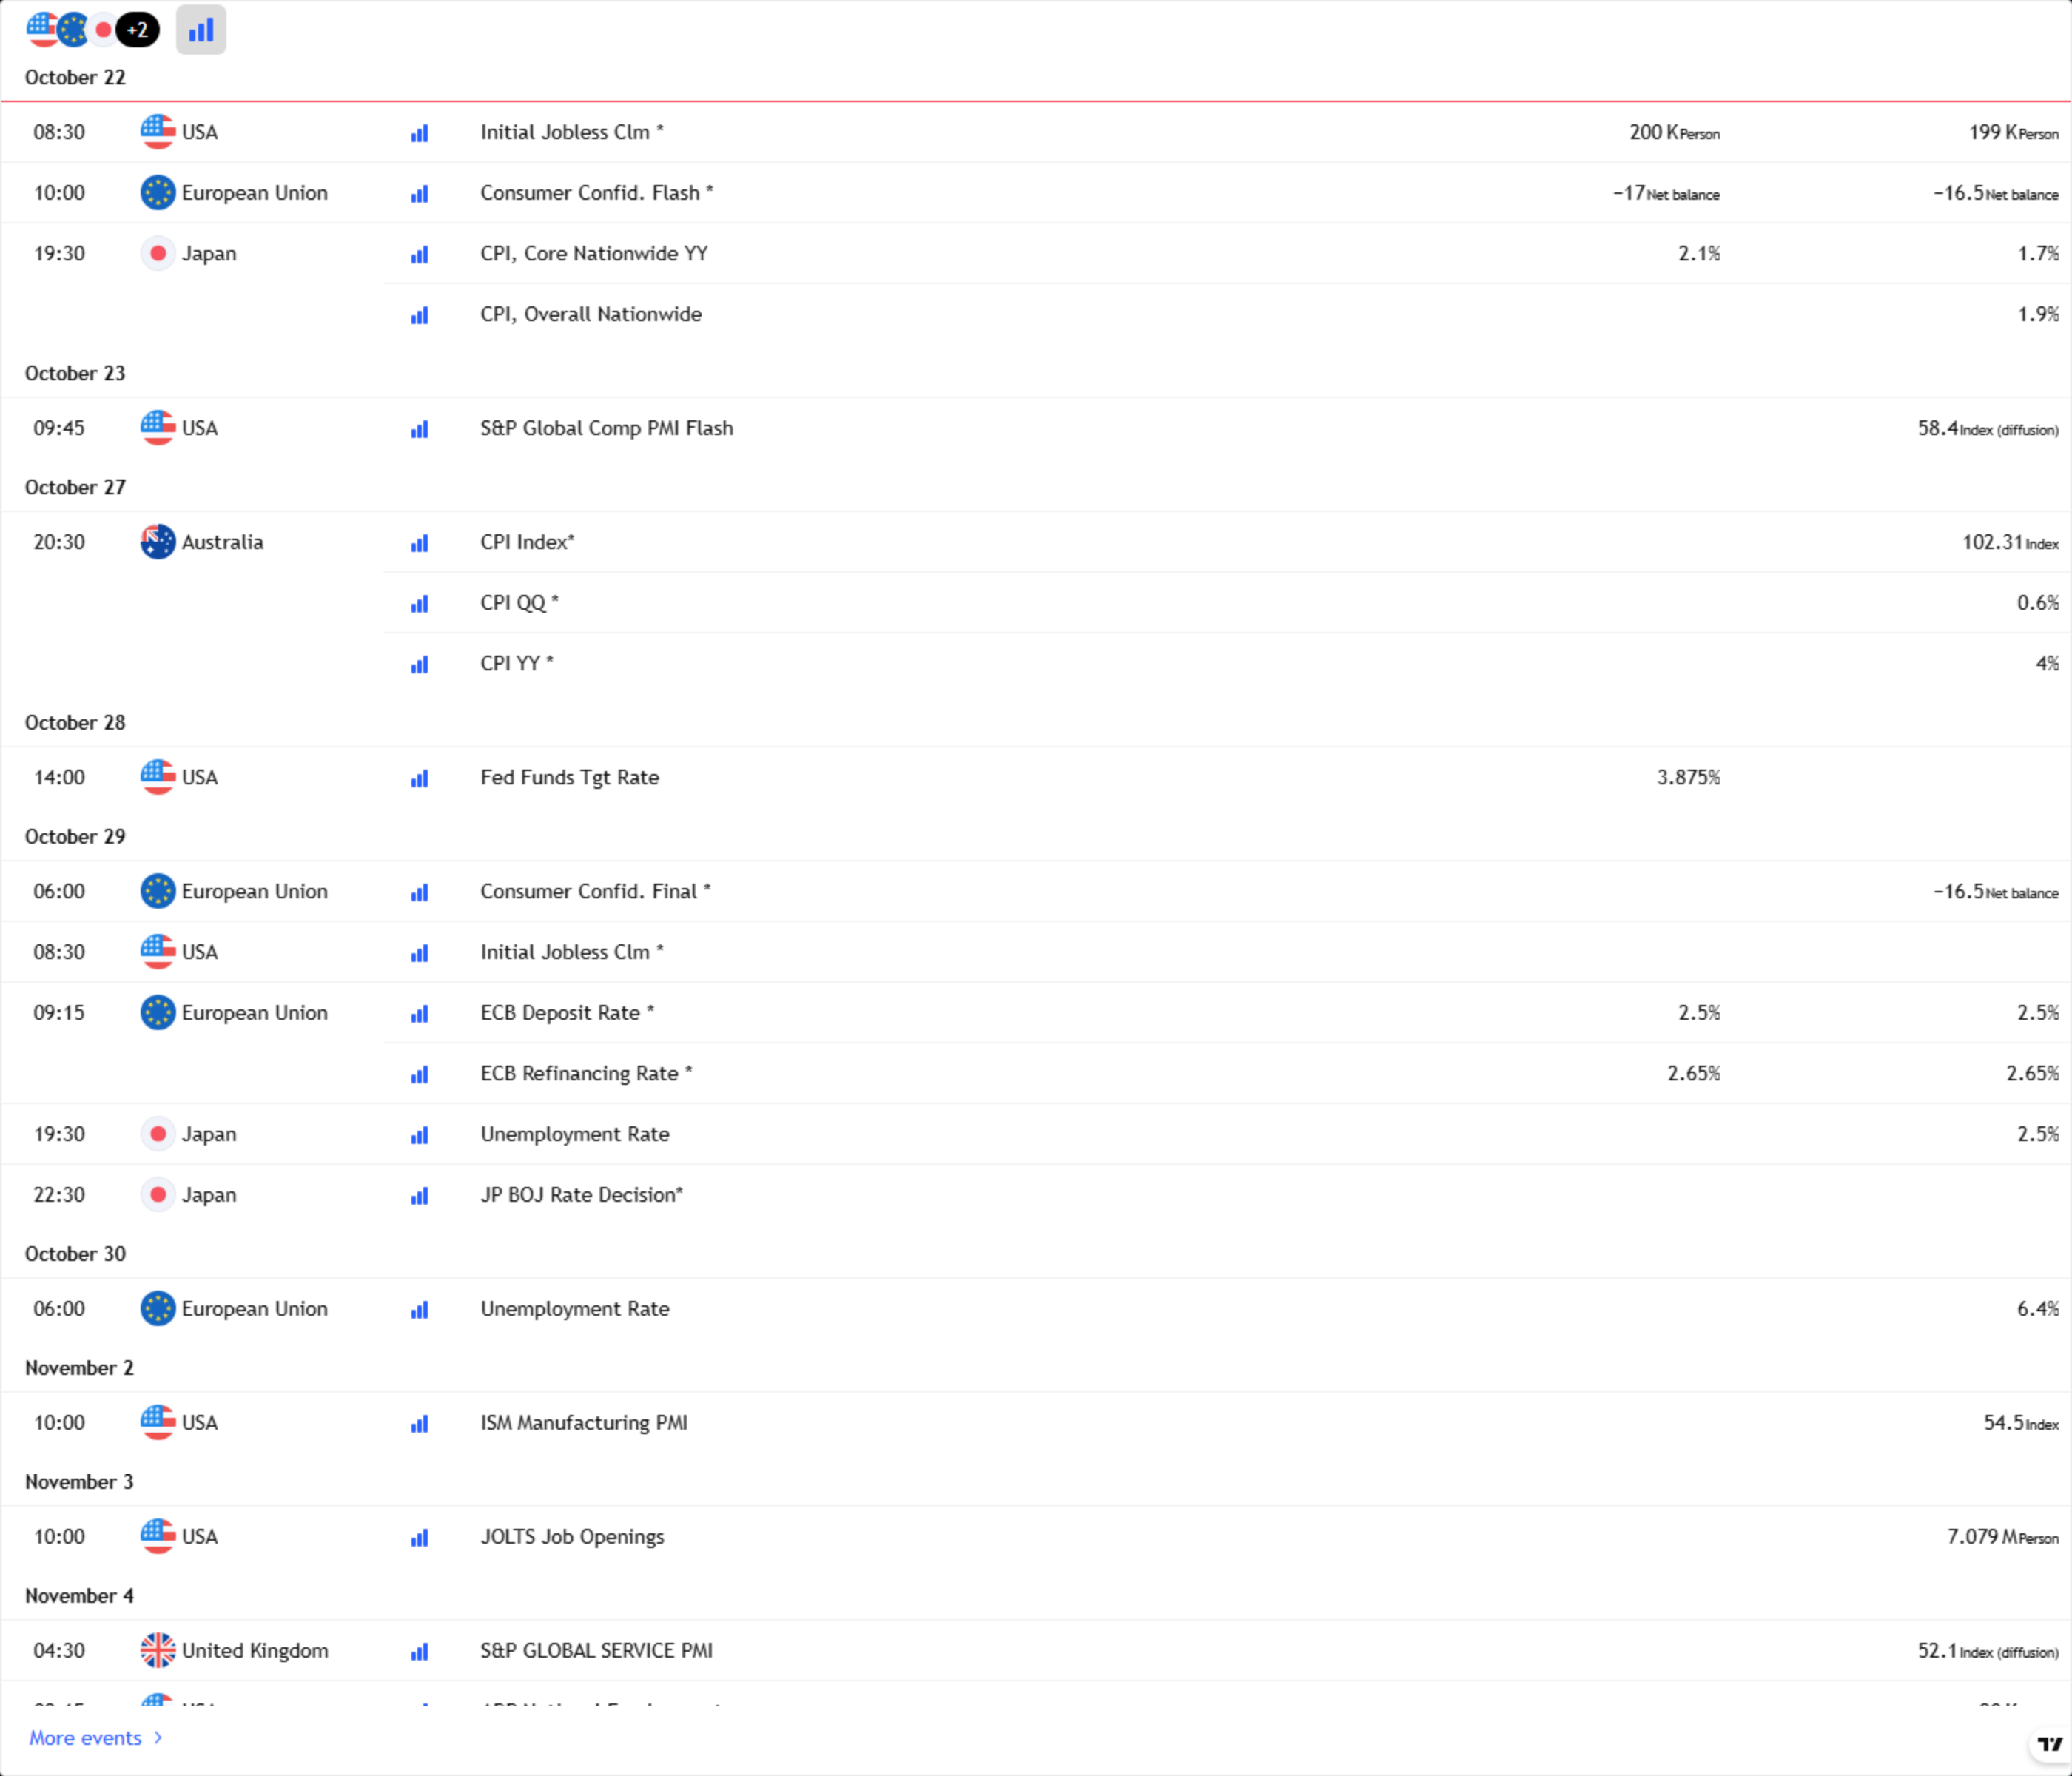
* Chart source: TradingView official economic calendar widget.
The run-up is short and the data is stacked at the front of it. US flash composite PMI on Friday is the first real test, with 58.4 expected — a number that would be an outright strong reading for the US economy. Claims, the 5-year TIPS auction and existing home sales follow, and then the Q3 GDP advance estimate and September PCE on October 29 land a day after the decision itself. That ordering is the awkward part: the market will trade the December path on data printed after the meeting that sets up the path.
3. What the market has already priced
The dollar index sits at 101.69, a whisker below its 52-week high of 102.95, and the 10-year Treasury at 5.146% — roughly 22 basis points below the 5.364% it touched on October 7. The long end has been doing the talking: if the December hike is fully priced, the question is whether the terminal rate is 4.25% or 4.50%, and the front end of the curve is where that will be settled. The dollar's own levels are simpler: 102.95 on top, the 101.50 pivot in the middle of the October range, and 100.00 underneath.
Equities have not flinched. The S&P 500 closed October 21 at 7,757.17, up 0.58% and within 1.1% of its record high, with the VIX at 16.68. Gold at roughly 4,113-4,132 an ounce is the outlier: it has fallen for consecutive sessions and now sits near the 4,100 level, which is what a rising real-rate path and a firm dollar do to it.
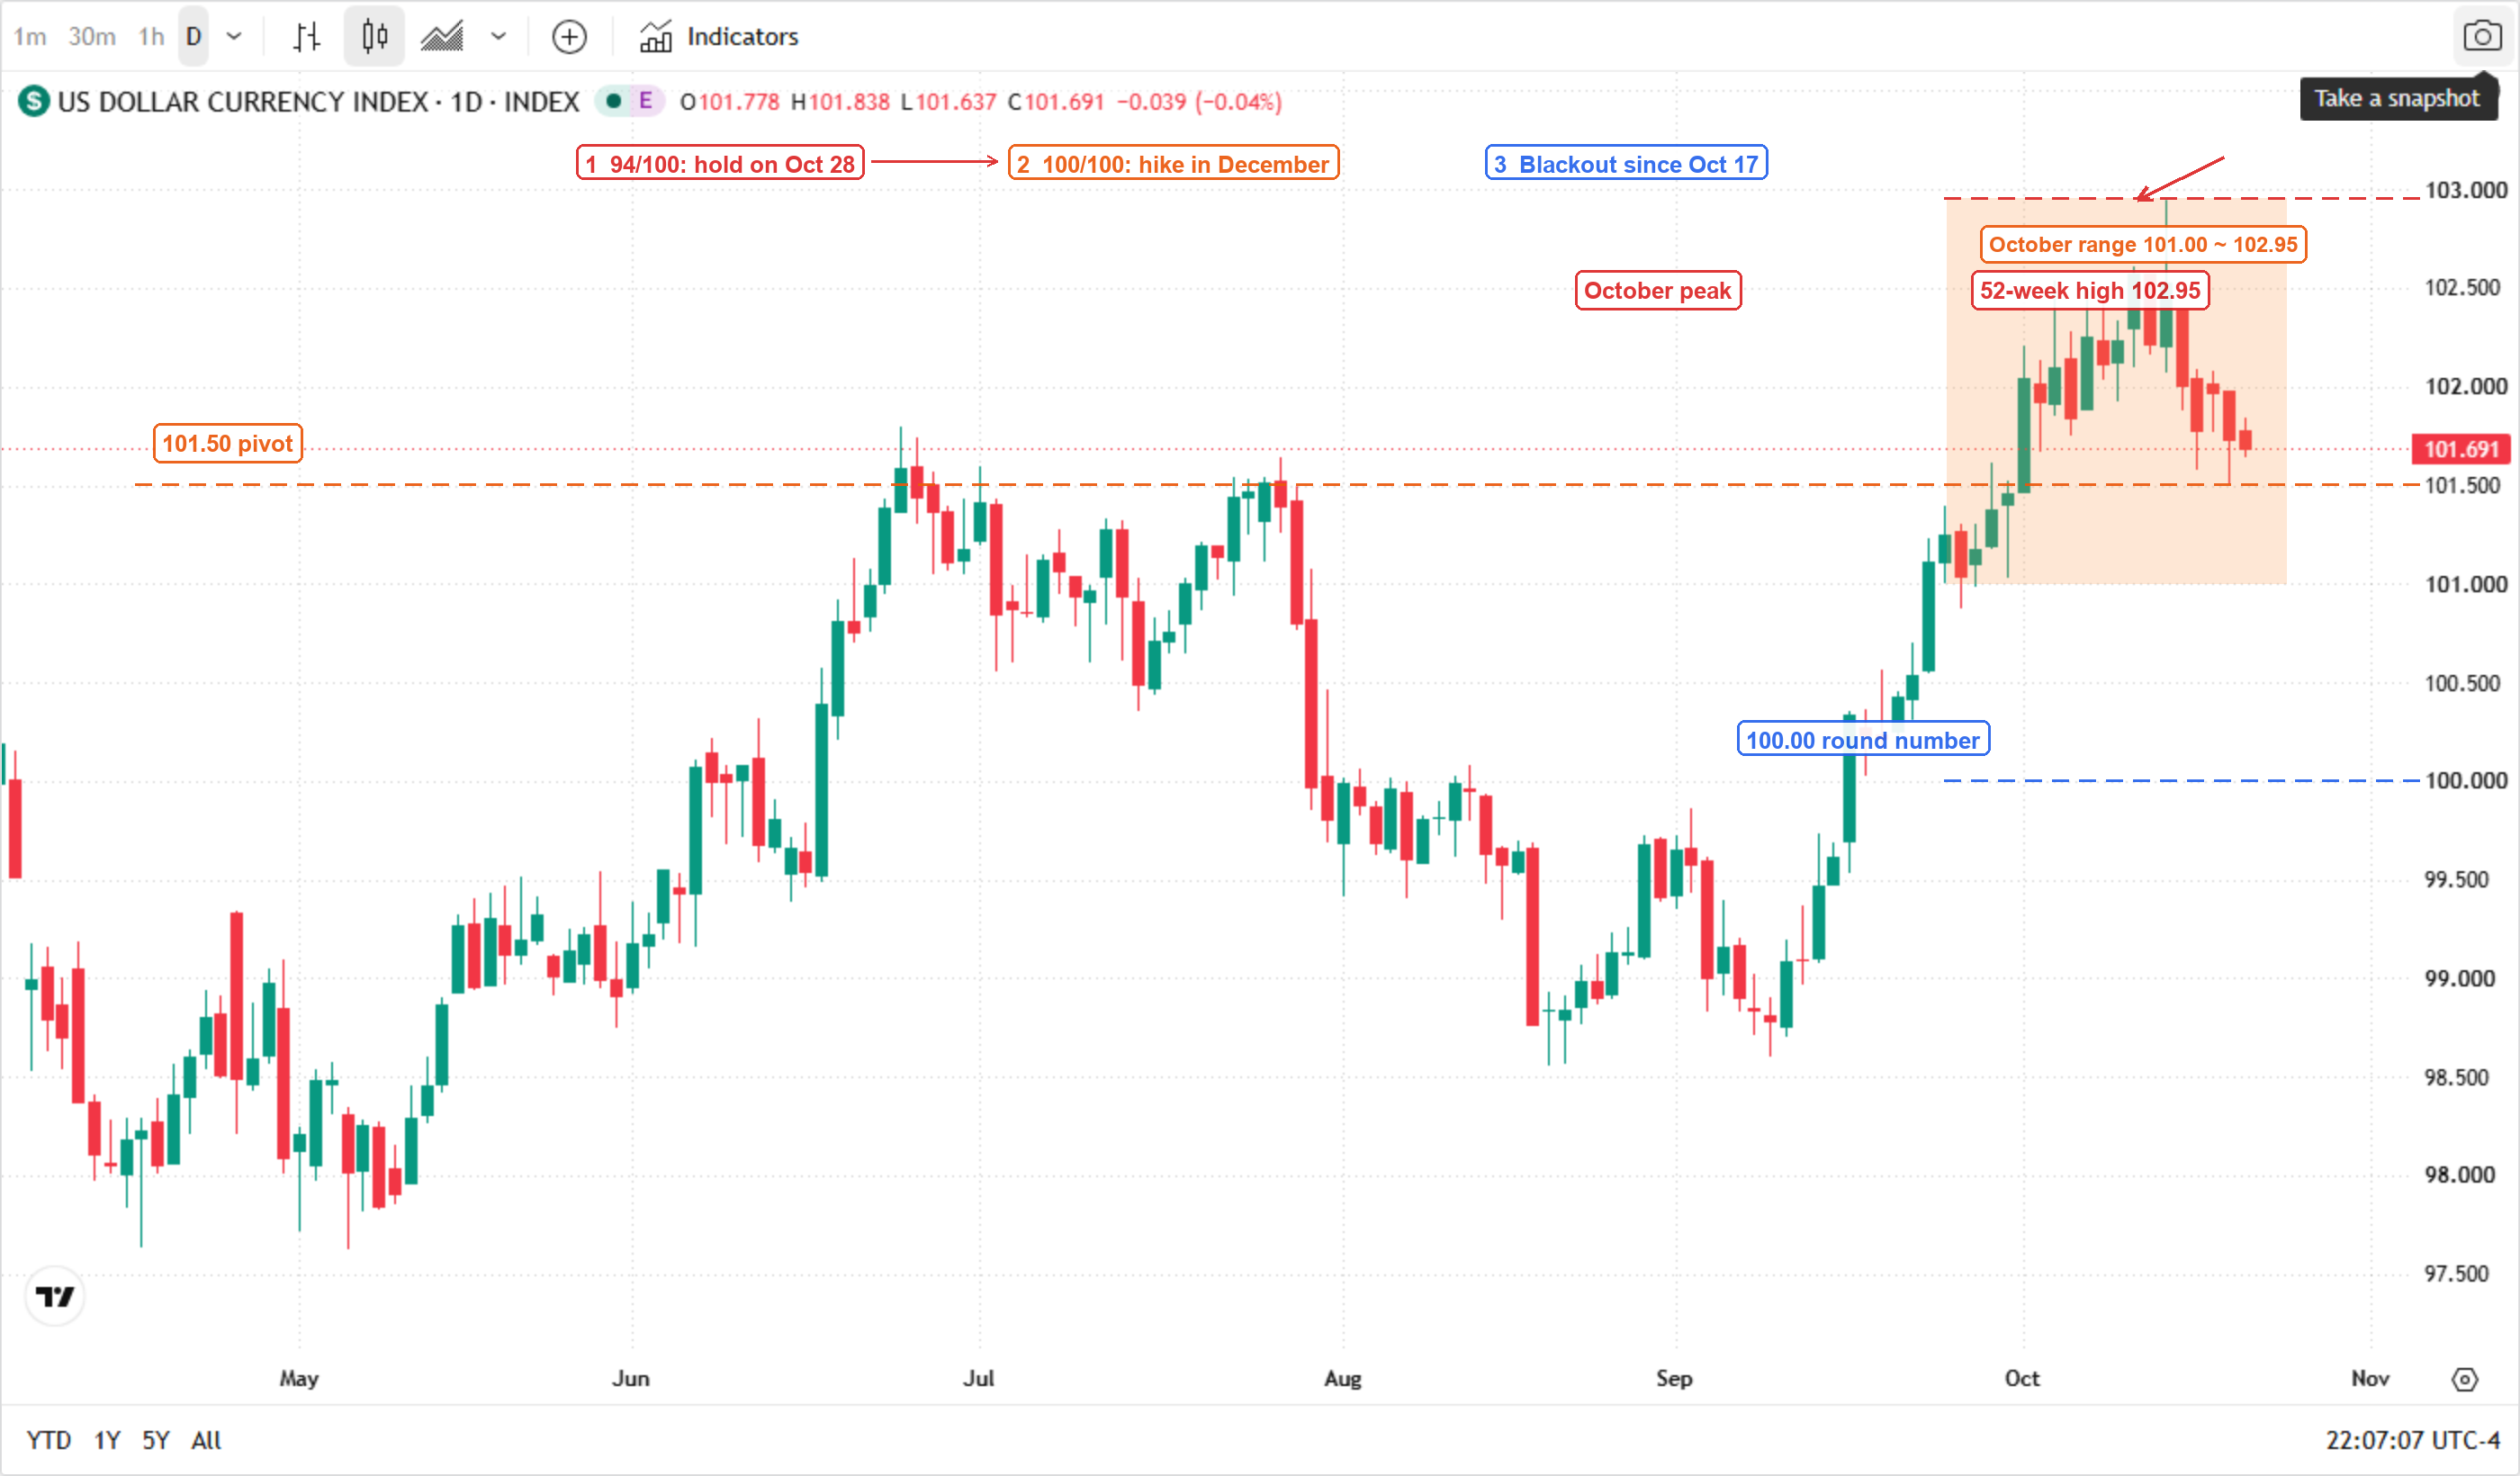
* Chart source: TradingView official chart screenshot, data source INDEX (US Dollar Index).
4. Two directions at each date
| Date and time (ET) | Event | If it comes in hot | If it comes in soft |
|---|---|---|---|
| Thu Oct 22, 08:30 | Initial jobless claims (200K expected) | December odds push toward the 90s; dollar extends above 102.95 | December odds slip back toward 75%; gold stabilises |
| Fri Oct 23, 09:45 | US flash composite PMI (58.4 expected) | A 58-plus print is a hawkish shock; the long end sells off | Anything under 57 unwinds the "one more hike" premium quickly |
| Mon Oct 26 | September existing home sales | Rates stay high for longer; the housing pipeline keeps shrinking | A soft print buys a lower terminal rate but weakens the economy |
| Wed Oct 28, 14:00 | FOMC decision and press conference | A hawkish hold — "the next hike is data-dependent" — extends the dollar's run | A dovish hold, or a hint that December is live but not guaranteed, unwinds December pricing |
| Thu Oct 29, 08:30 | Q3 GDP advance estimate and September PCE | Sticky PCE confirms the 4.50% terminal debate; equities de-rate | A soft PCE with a firm GDP is the stagflation-lite case nobody wants |
The bottom line: October is a formality; the trade is December, and December is a coin flip that one poll has made look like a certainty. A unanimous forecast is usually a description of what has already happened, not a prediction — and at 5.146% on the 10-year and 101.69 on the dollar, a good deal of that December hike is already in the price. The asymmetry is in the second hike, not the first, and the data between now and October 29 is what decides whether the market has to reprice it.
Read more
Before making any trading decisions, it is important to equip yourself with sufficient fundamental knowledge, have a comprehensive understanding of market trends, be aware of risks and hidden costs, carefully consider investment targets, level of experience, risk appetite, and seek professional advice if necessary.
Furthermore, the content of this article is solely the author's personal opinion and does not necessarily constitute investment advice. The content of this article is for reference purposes only, and readers should not use this article as a basis for any investment decisions.
Investors should not rely on this information as a substitute for independent judgment or make decisions solely based on this information. It does not constitute any trading activity and does not guarantee any profits in trading.
If you have any inquiries regarding the data, information, or content related to Mitrade in this article, please contact us via email: insights@mitrade.com. The Mitrade team will carefully review the content to continue improving the quality of the article.


