


6 Defense and Industrial Stocks to Buy and Hold Through 2030
Key Points
Defense revenue helps smooth cyclical risks in aerospace and industrial end markets.
Each company has unique strengths and growth drivers through 2030, and buying a combination of these stocks would ensure some diversification in a portfolio.
- 10 stocks we like better than GE Aerospace ›
The case for combining a cyclical industrial business (in this case, aerospace) with a more stable defense business is compelling. The reliable, long-term income from a defense business smooths out the ups and downs of industrial-side income. It enables companies like RTX (NYSE: RTX) and GE Aerospace (NYSE: GE) to commit to multibillion-dollar investments in developing long-cycle products such as aircraft engines. Here's a look at them and four other attractive companies.
RTX for its balanced exposure to commercial aerospace and defense
As the company with the largest long-term defense exposure, the key to the investment case for RTX is the balance between the commercial aerospace business in Pratt & Whitney (aircraft engines, largely commercial aerospace but also defense), Collins Aerospace (heavily focused on commercial aerospace structures and components), and Raytheon (almost entirely defense).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
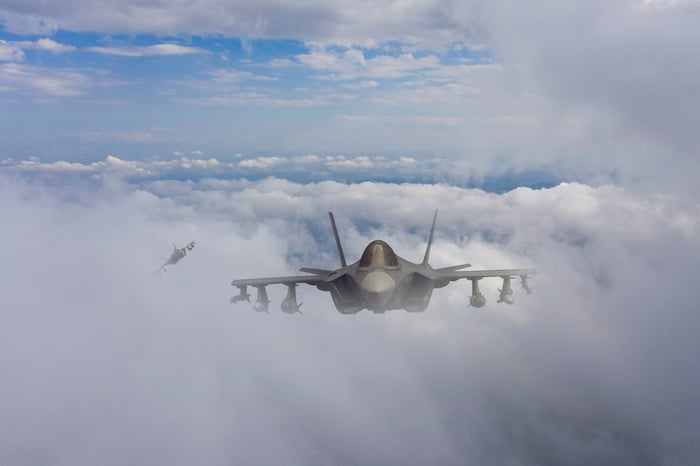
Image source: Getty Images.
The interesting thing about RTX's Raytheon, and why I think RTX is a better buy than Lockheed Martin, comes down to having relatively less exposure to some of the fixed-price development programs that have led to massive cost overruns and charges at Lockheed and Boeing (NYSE: BA) in recent years. For example, Raytheon has proven technologies such as Tomahawk missiles and advanced medium-range air-to-air missiles (AMRAAMs) in its backlog, which, although subject to supply chain risk, pose significantly fewer challenges than the F-35 (Lockheed) or next-generation strike fighters (Boeing) pose.
Moreover, Pratt's commercial engines, primarily the geared turbofan (GTF) on the Airbus A320neo, can generate decades of lucrative aftermarket revenue, and Collins is a major player in commercial aerospace across many platforms.
GE Aerospace for its dominant position in aircraft engines
GE Aerospace's management expects to generate $1.6 billion to $1.7 billion in operating profit from its defense and propulsion technologies business in 2026, compared to $10.25 billion to $10.35 billion from its commercial engines and services segment. Clearly, defense is not the primary reason to buy GE Aerospace stock. Still, it is a profitable business that is also highly complementary to the commercial aerospace business, with commercial and defense engines sharing core technologies, materials, and supply chains, and with stronger bargaining power when negotiating with suppliers.
Meanwhile, the commercial aircraft engine business, like RTX, has a long tail of lucrative recurring aftermarket revenue (engines can be used for more than 40 years) driven by its dominant position in the industry.
Image source: Getty Images.
Boeing for the turnaround
The case for buying Boeing isn't based on flawless execution in its commercial airplane business (the high-profile groundings and delays, notably on the 777C) or even in its defense business (barely profitable after years of challenges with fixed-price development contracts). Instead, it rests on the idea that CEO Kelly Ortberg is improving execution and leveraging Boeing's $715 billion backlog, including $597 billion in commercial airplanes.
There are clear signs of progress with delivery rates ramping up on the 737 MAX, and management expects a 2.5% profit margin in the defense business in 2026 as it works through the problematic defense programs. Moreover, based on analyst estimates, Boeing trades at a clear discount to the sector, implying meaningful upside potential if Ortberg continues to turn the business around.
Hexcel for composite content growth
Boeing, Airbus, and their suppliers make up the bulk of demand for Hexcel's (NYSE: HXL) advanced composites, and "defense, space, and other" accounts for 37% of its overall revenue. Hexcel is essentially a play on improving aircraft build rates and increasing the content of advanced composites on newer aircraft. This clear trend continues to grow with each new generation of aircraft.
While the company has suffered in previous years as aircraft build rates have slowed, notably for widebodies that use more composites, backlogs at Boeing and Airbus will drive future demand.
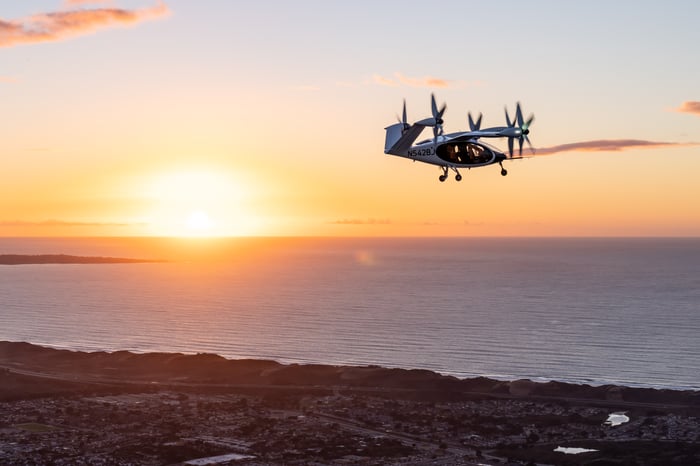
Image source: Joby Aviation.
Joby Aviation for eVTOL growth
The case for buying Joby Aviation (NYSE: JOBY) isn't based on its long-term defense business. Instead, the company needs to get its commercial electric vertical take-off and landing (eVTOL) aircraft certified and in operation as it slowly builds out its transportation-as-a-service model. It's an exciting business, but it will take time and cash before it turns a profit. That's why eVTOL companies like Joby and Archer Aviation are increasingly turning to defense work, which offers more immediate upfront revenue.
In fact, Joby recently acquired Resonant Sciences, a radio-frequency (RF) sensing and signal-processing defense technology company, for $500 million. Resonant will become Joby's defense business, with the intent to "unite Joby's dual-use aircraft, propulsion and autonomy technologies with Resonant's radio frequency (RF), sensing and mission systems capabilities."
AAR Corp., buy the dip
If Hexcel and Boeing are original equipment (OE) plays, and GE Aerospace and RTX are a mix of both, then aviation services company AAR Corp. (NYSE: AIR) is on the aftermarket end of the spectrum. It generates about 27% of its sales from government sources, mainly military. The company made the news recently after its stock fell following the planned acquisition of a majority stake in the complementary maintenance, repair, and overhaul business MRO Holdings.
However, the deal makes perfect sense, comes with a reasonable price tag, and promises to expand AAR's geographic reach, notably in Latin America, and its offerings, making it the world's largest maintenance, repair, and overhaul company. I think the dip is a buying opportunity in a company expanding its footprint in an expanding market.
Should you buy stock in GE Aerospace right now?
Before you buy stock in GE Aerospace, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and GE Aerospace wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $370,440!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,470,022!*
Now, it’s worth noting Stock Advisor’s total average return is 955% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 7, 2026.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Aar, Boeing, GE Aerospace, Lockheed Martin, and RTX. The Motley Fool recommends Hexcel. The Motley Fool has a disclosure policy.
Recommended Articles


