


Conagra Stock Forecast: Can Q1 Earnings Stabilize CAG After Its Dividend Cut?
TradingKey - Conagra Brands (CAG) is scheduled to release financial results for the first quarter of its fiscal 2027 on September 30, before the market opens. The stock is currently under distribution. With a recent close at $14.13, CAG has recorded a 52-week range of $12.53 to $20.32. The stock’s near-term outlook depends on the company’s ability to protect margins and volume. The dividend cut provides the company with financial flexibility. A low earnings multiple makes CAG’s valuation look cheaper, but only positive revisions to the company’s long-term guidance will alleviate downside.
Q1 Earnings Are the Immediate Test
Conagra is expected to release results for the first quarter of its fiscal year 2027 on September 30. Management will hold a live Q and A at 9:30 AM Eastern Time. Accordingly, the information in this article will be considered speculative. For the quarter, the most important metrics will be volumes, gross and operating margins and EPS. While an EPS beat will be acknowledged, the focus will be on the underlying volumes. Improving volumes and gross and operating margin will be better indications of the health of Conagra’s business. The guidance management provides for the remainder of the fiscal year will be a major factor if Q1 will be considered positive.
Q4 Showed Why Reported Sales Need Context
Conagra Brands reported its latest quarterly results, including its fourth quarter of fiscal year 2026. Conagra reported an increase in net sales of 3.6% for the quarter. However, organic net sales were approximately flat. For the quarter, Conagra reported a decrease in volume of 1.6%. Adjusted operating margin for the quarter was 11.7%. Adjusted EPS for the quarter was $0.47. Conagra reported a diluted loss per share of $3.37 for the quarter, primarily due to non-cash goodwill and brand impairment charges. The impairment charges were non-cash accounting charges. For the full fiscal year, Conagra reported net sales of $11.3 billion. Adjusted EPS for the year was $1.72. Conagra reported a 2.9% decline in full-year net sales, while organic net sales decreased 0.4%. I will discuss Conagra’s reported sales for the year and focus on organic sales.
Fiscal 2027 Guidance Already Assumes a Difficult Year
Conagra expected organic sales to decline between 1.0% and 3.0% for fiscal year 2027. Expected adjusted operating margin was 10.0% to 10.5% for the year. Expected adjusted EPS was between $1.40 and $1.50 for the year. If the expected adjusted EPS for the year was $1.45, which is the midpoint of the expected range, then a decline in adjusted EPS of 15.7% would be reported for the year compared to fiscal year 2026. Based on the expected guidance for the year, the strongest scenario would likely be for management to maintain the expected range of guidance. If the expected range of the guidance was reduced, then a decline in the stock price would likely occur.
The Dividend Reset Improves Flexibility
Conagra reduced its annual dividend in July to $0.70. On September 24, its board of directors declared a cash dividend of $0.175. The dividend is payable on December 3, 2026 to shareholders of record as of November 5, 2026. With a share price of $14.13 at the September 29, 2026 close, this dividend yield 5.0%. From a dividend growth investor’s perspective, this dividend reduction is unfortunate; however, from a finance perspective, this gives Conagra more financial flexibility. Free cash flow for the year ending in May 2026 was $978.7 million. With high financial leverage, management expects to end the fiscal year 2027 with net financial leverage of 4.0 times. Cash flow reduction, coupled with the leverage and a better financial performance and operating result should be the focus of the cash dividend reduction.
Balance Sheet Pressure Remains Relevant
Although some may think Conagra’s balance sheet is less important, this is not the case. Total debt is around $7.27 billion and net debt is about $7.05 billion. Net debt to adjusted EBITDA was 3.83 times at fiscal year-end. While this remains meaningful leverage, it sets a limit on the company’s ability to withstand downturns in the packaged food industry. Management expects several things in fiscal 2027. First, they expect CAPex of about $550 million. Second, they expect free cash flow conversion of greater than 90%. Given these expectations, cash flow and spending will probably be the focus of the earnings call. Although management expects good things for fiscal 2027 and 2028, concern for fiscal 2029 and beyond is probably warranted. Since Conagra is selling packaged food and other CPG products, consumer demand probably influenced management’s expectations for the next few years.
September News Shows Where Management Sees Demand
Results of Conagra’s Future of Snacking survey outlined consumer trends. Conagra pointed out that consumers are using Artificial Intelligence to search out and identify snack foods containing higher levels of protein and fiber. Also, consumers are looking for functional benefits in snack food choices. Obviously, an uptick in consumers’ snack food choices, may impact the way Conagra develops new products, and/or alters current product offerings. It will also impact how Conagra designs, and artWorks packaging and distributes its products. Conagra already produces a myriad of products that may satisfy consumers’ needs; therefore, it may just be a case of Conagra better marketing and promoting products already in its line.
Portfolio Simplification Could Help
Reuters also reported Conagra’s CEO is evaluating parts of the company’s business that are outside of the company’s core business. Management’s changes to the company’s portfolio have the potential to positively impact the company’s financials. It is positive for the company if Conagra sells part of its business for more than the business is worth. The proceeds from the sale should be invested in a manner that positively impacts the business. There is a positive impact to the business if part of Conagra is sold, and the proceeds are used to reduce the company’s debt.
Valuation Looks Cheap, but Only if the Guide Holds
At the time of writing, CAG is trading at approximately $14.13. Management has provided an adjusted EPS guidance of $1.40 to $1.50 for fiscal 2027. Using the midpoint, this works out to an EPS of $1.45. Trading at 9.7x the midpoint of management’s EPS guidance implies a relatively low valuation. Investors are likely discounting the value of the stock given declining earnings, falling volume and increasing financial leverage. When accounting for free cash flow, the stock looks even more attractive, trading at a multiple of 7x. I agree that the stock is attractively valued. However, the low multiple offers little protection given the consensus view is that EPS will continue to decline. The fair value of the stock depends on how management communicates guidance for fiscal 2027.
Conagra Brands Technical Analysis: CAG Tests $14.04 Support as Downtrend Remains Intact
Conagra Brands last closed at $14.13. The 1 hour chart shows price approaching $14.04. Price broke below $14.33 and is also trading beneath the 200 and 50 SMAs and the rising trendline. The falling structure, coupled with lower highs and lower lows, indicates a bearish trend.
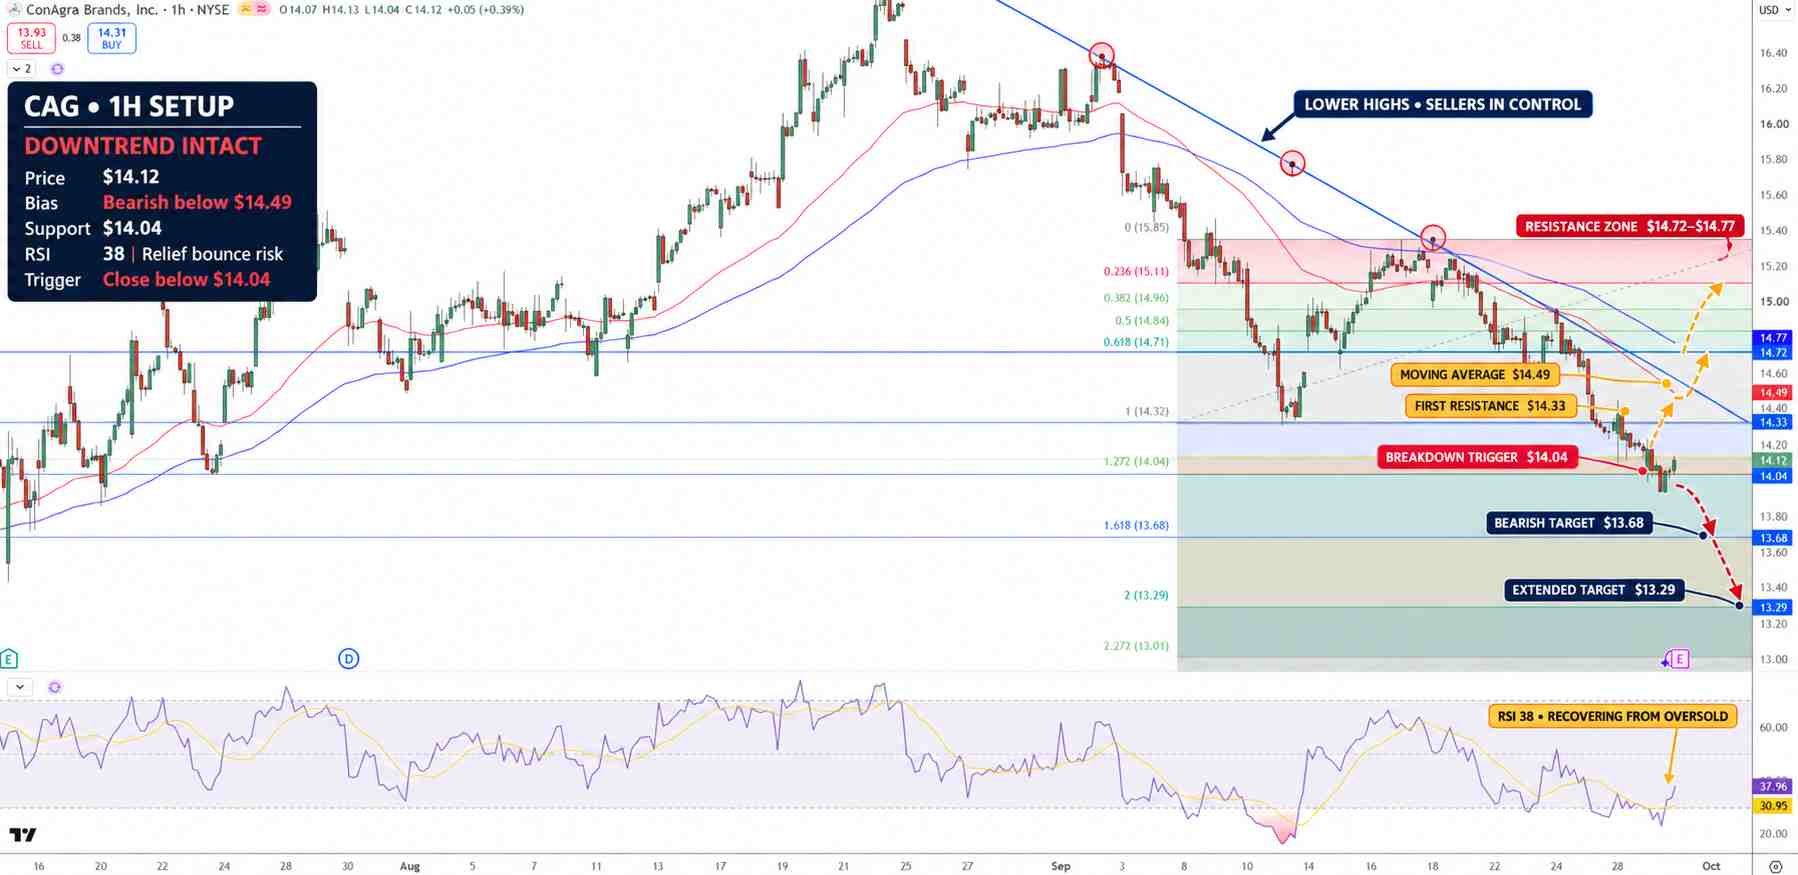
Conagra Stock Price Chart - Source: Tradingview
The RSI is at 38. RSI is above its signal line near 31, leaving room for a relief bounce but not confirming a trend change. I expect price to move towards the support at $14.04. A break below $14.04 would target $13.68. Other levels of support are at $13.29. For price to rise, it would have to break and close above $14.33. Other levels of resistance are at $14.49 and $14.72 to $14.77. I believe price is likely to move toward my bearish target of $14.04 and then $13.68, so long as it trades below $14.33 to $14.49.
Why is Conagra stock in focus now?
Conagra has lowered its guidance for reduced organic sales, cut its expected adjusted EPS, and lowered its dividend. The company will release its financial results for the first quarter of its fiscal year 2027 on September 30. Investors will assess if the company is making progress to improve operating margins and operating cash flows.
What level confirms a stronger CAG recovery?
Progress in the form of a sustained hourly close above $14.49 would provide a positive adjustment to the near-term outlook and lay a foundation for a test of 14.72-14.77. Should an hourly close fall below $14.04, the bearish configuration would gain validity and enhance the probability of a move toward the $13.68 area.
Bottom Line
Conagra trades at a low valuation, and will require positive changes to its multiple operating levels. Management has initiatives in place to restore operating margin of the business.
The primary negative is a continuation of the negative trends baked into consensus estimates for fiscal 2027.
From a technical viewpoint, Conagra is bearish under $14.33 to $14.49. Holding $14.04 could support a relief bounce. A decline below $14.04 would likely reinforce the bearish trend and connect to the $13.68 area.
Recommended Articles


