


Micron Earnings Preview: Can AI Memory Demand Sustain Its Boom? Wall Street Highest Target Hits $2,000
TradingKey - Micron Technology (MU) will release its fourth-quarter fiscal 2026 financial results after the U.S. market close on September 30. Against the backdrop of continued AI server expansion, rising DRAM and NAND prices, and rapidly growing HBM demand, this earnings report has drawn high market attention.
According to FactSet estimates, Micron's fourth-quarter revenue is expected to be approximately $51.07 billion, with earnings per share of about $31.52. The company's previous guidance was revenue of around $50 billion, plus or minus $1 billion, and adjusted earnings per share of about $31, plus or minus $1. Over the past four quarters, Micron's earnings have consistently exceeded expectations, and current market expectations for this earnings report are relatively high.
Can HBM4 Volume Ramp Help Micron Catch Up With Samsung and SK Hynix?
Over the past year, the biggest change for Micron has come from AI data center demand.
As AI models expand in scale and inference workloads increase, servers demand increasingly higher memory capacity and bandwidth, making high-performance storage products such as HBM and DDR5 the primary drivers of industry growth. Meanwhile, supply and demand dynamics in the traditional DRAM and NAND markets have also improved significantly, with rising prices further amplifying Micron's revenue and profit growth.
This trend is expected to continue into the fourth quarter. According to market forecasts, Micron's fourth-quarter DRAM revenue is projected to reach approximately $38.26 billion, up more than 300% year-over-year, while NAND revenue is expected to reach around $12.32 billion, a year-over-year increase of over 400%.
Currently, Micron's share in the HBM market still lags behind SK Hynix and Samsung, but the company is attempting to narrow the gap through HBM4 product iterations. Management previously stated that Micron has already shipped over $1 billion worth of HBM4 products, and whether it can scale up production in the next phase will directly affect its competitive position in the AI memory market.
Competitors are not slowing their expansion plans either. Samsung is expanding capacity for HBM4 and next-generation HBM4E, while SK Hynix is accelerating relevant fab construction and equipment investment. With both major rivals ramping up supply simultaneously, whether Micron can expand its market share with HBM4 will be a key metric to watch over the coming quarters.
How Much Longer Can Memory Prices Keep Rising? Micron Really Faces Cyclical Risk
Currently, one of Micron's strongest earnings drivers is that the memory chip market is experiencing a tightening supply-demand balance.
The industry was previously weighed down by excess inventory for a long time, but as manufacturers reined in capital expenditures and demand for AI servers grew rapidly, market supply gradually tightened, and DRAM and NAND prices began to rebound significantly. For Micron, this environment has not only expanded its sales scale but also significantly boosted its profit margins.
In the third quarter of fiscal 2026, the company achieved revenue of $41.46 billion, up 74% quarter-over-quarter, with GAAP net income reaching $28.24 billion and profit margins remaining at high levels. The market expects fourth-quarter gross margin to potentially rise further to around 87%, and some institutions even believe there is room for profit margins to move higher.
However, that is precisely where the problem lies.
The memory industry has always been highly cyclical. While current price increases have given Micron exceptional profitability, market supply will sooner or later recover as Samsung, SK Hynix, and other manufacturers gradually expand capacity. If the release of new capacity outpaces the growth in AI demand, the magnitude of price increases could diminish, putting Micron's profit margins under pressure as well.
Micron itself is also investing heavily to prepare for the next wave of demand growth. The company continues to increase production capacity for products such as HBM and DRAM while expanding its R&D and manufacturing facilities. Over the next decade, the company plans to invest approximately $10 billion to build an advanced R&D center in Boise, Idaho, further positioning itself in next-generation memory and advanced packaging technologies.
These investments will help Micron maintain long-term competitiveness, but they also mean the company must bear higher capital outlays. If market strength persists, the new capacity will serve as the foundation for future revenue growth; however, if the cycle suddenly turns, high capital expenditures could further amplify earnings volatility.
Wall Street Remains Optimistic, but Expectations Are Already High
Based on current market expectations, Wall Street remains highly confident in Micron.
According to TipRanks, among the 20 analysts covering Micron over the past three months, 19 give it a "Buy" rating, while only one recommends a "Hold." The average price target reaches $1,501.84, with the highest target at $2,000 and the lowest at $1,100.
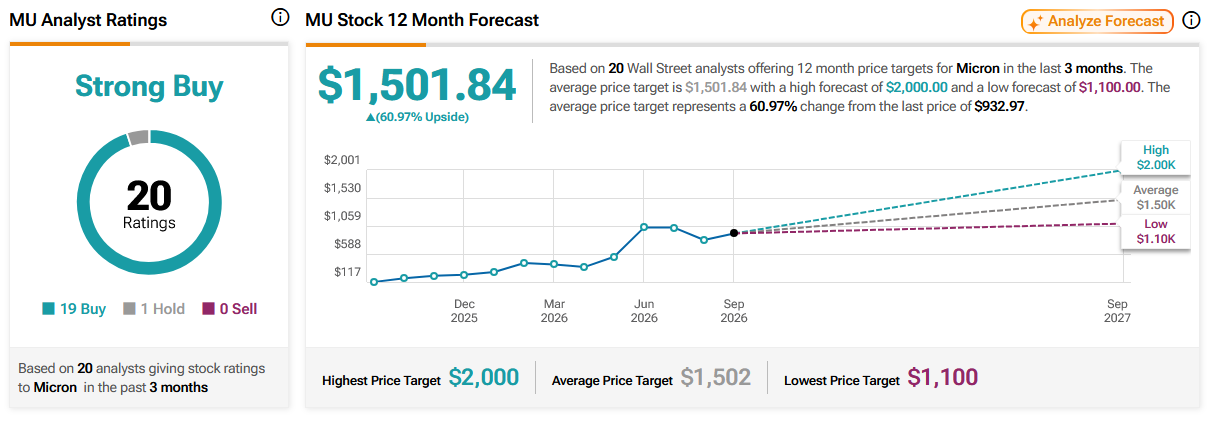
Source: TipRanks
Recently, several institutions have also maintained positive outlooks. UBS maintained a "Buy" rating with a $1,625 price target; Rosenblatt reiterated its $1,500 price target; Citi raised its price target from $1,150 to $1,300; BMO Capital Markets likewise maintained its $1,300 price target; and Wells Fargo issued a $1,400 price target.
The core assumptions behind these price targets are broadly consistent: AI infrastructure investment will maintain rapid growth, demand for HBM and high-performance DRAM will continue to expand, and Micron will maintain strong pricing power.
However, it is worth noting that market expectations are already high, meaning that simply beating earnings expectations may not be enough to drive a sustained stock rally. For Micron, which has already experienced significant gains, investors are looking for clear signals from management that demand will continue to exceed supply in the coming quarters.
Recommended Articles


