


Western Digital Q1 Revenue Surges 55% YoY, Shares Drop Nearly 7%: Can $330 Support Hold?
TradingKey - Western Digital (WDC) reported strong first-quarter fiscal 2027 results and provided next-quarter guidance significantly above Wall Street expectations, but still failed to reverse its stock price decline.
Following the earnings release, WDC's stock price initially rose over 2% before quickly pulling back, with the maximum after-hours drop approaching 7%, reflecting investors' reassessment of the sustainability of the hard drive boom cycle.
For the first fiscal quarter ended October 2, 2026, Western Digital's revenue reached $4.381 billion, up 55% year-over-year and 17% quarter-over-quarter, exceeding market expectations of approximately $4.14 billion. GAAP net income was $1.779 billion, up about 50% year-over-year; diluted earnings per share came in at $4.63, up from $3.07 in the same period last year.
Excluding special items, the company's adjusted earnings per share reached $4.64, up 161% year-over-year, also beating the market consensus of $4.11 from a FactSet survey. Both revenue and profit surpassed analysts' forecasts, indicating that demand for enterprise-grade hard drives from cloud computing and artificial intelligence infrastructure remains strong.
The company stated that customer demand remained robust, driven by increased storage capacity shipments and improved average selling prices, which jointly propelled revenue and margin growth. As the volume of data generated by generative AI continues to expand, cloud service providers require not only more computing power, but also increased storage capacity to retain training data, model outputs, and corporate files, which continues to support demand for nearline hard drives.
Western Digital's outlook for the second fiscal quarter was also significantly higher than market forecasts. The company expects revenue of $5.0 billion to $5.2 billion, with a midpoint of about $5.1 billion; adjusted earnings per share are projected to be $5.60 to $6.00, with a midpoint of $5.80. In comparison, analysts had previously expected revenue of approximately $4.57 billion and earnings per share of $4.84.
Despite both results and guidance beating expectations, WDC's stock still turned from gains to losses, initially reflecting clear "sell the news" pressure. Western Digital's stock had experienced a substantial rally over the past year, with the market having fully priced in the gains from AI data growth, controlled hard drive supply, and rising prices. Facing a high valuation, merely beating consensus expectations was no longer sufficient to drive the stock price further up.
Investors are also concerned about whether the current hard drive boom cycle can be sustained in the long term. Competitors such as Toshiba expanding the supply of advanced hard drives, rising production costs, and Western Digital's capital expenditure over the next two years potentially approaching the upper limit of its guided range as a percentage of revenue could all constrain further free cash flow growth. Some market participants are also focused on inventory increases, worrying whether the strong demand includes factors such as customers stocking up in advance.
In addition, tech stocks and AI concept stocks suffered a broad sell-off on the day of the earnings release, with the Nasdaq Composite Index falling 2.6%. Market concerns over the scale of AI infrastructure investment, financing costs, and short-term returns escalated, leading investors to prefer reducing risk exposure even when companies delivered better-than-expected results. Western Digital had already dropped 6.43% during regular trading hours, and the weak market sentiment further amplified after-hours volatility.
Source: TradingView
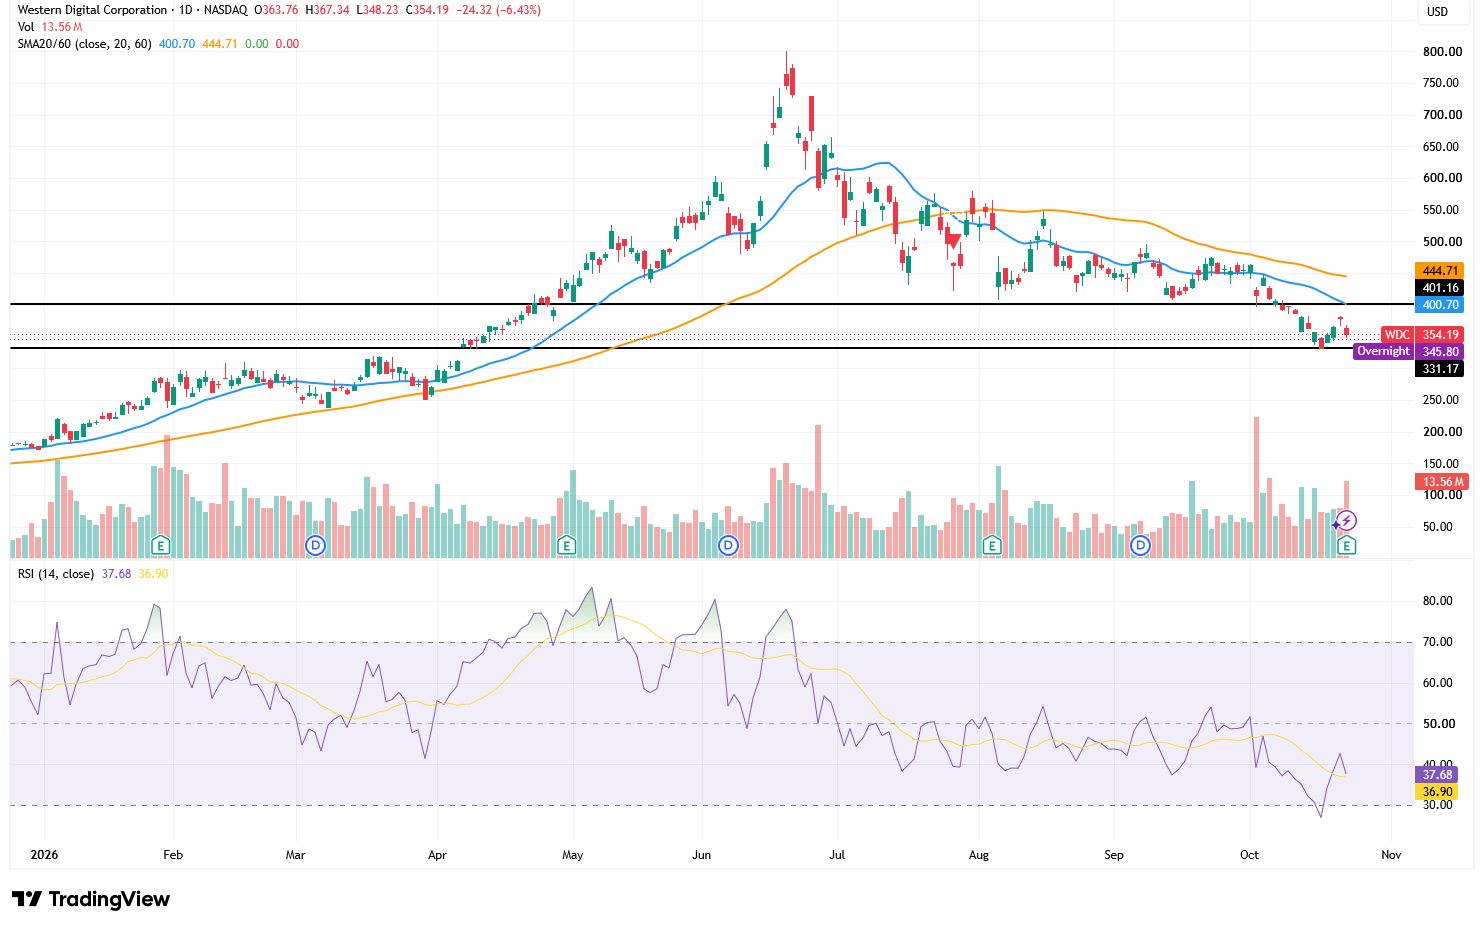
From the daily chart perspective, Western Digital remains in a clear bearish structure, with the stock closing at $354.19, having broken below the 20-day moving average of $400.70 and the 60-day moving average of $444.71. Meanwhile, the 20-day moving average sits below the 60-day moving average, and both moving averages are sloping downward, indicating that the medium- to short-term trend has yet to experience a substantive reversal.
The $330–$340 range is currently the most critical support zone, close to recent lows and serving as the starting point of the previous rally. After-hours prices have already fallen back to around $345, implying that the defensive space for bulls is shrinking. If the stock can hold above $330 and show a volume-backed bullish engulfing pattern or a long lower shadow, it could rebound in the short term to $360–$370; further resistance lies between $390 and $401, with the vicinity of $400 forming confluent resistance with the 20-day moving average.
Conversely, if the stock breaks below $330 on high volume and closes below it for consecutive sessions, the downtrend may continue, with the next target area to watch at $300–$310, and in extreme cases, a retest of the $275–$285 zone. An intraday breakdown alone does not constitute a valid breakdown; it should be confirmed by both the daily closing price and trading volume.
The RSI currently stands at around 37.7; although slightly above the signal line, it remains below the 50 neutral threshold and has not yet entered the oversold zone below 30. This suggests that the stock price is already weak but has not shown a very clear oversold reversal signal, leaving open the possibility of further downside in the short term.
Recommended Articles


