


Amgen Stock Forecast: Sjögren’s Trial Success Tests AMGN’s Pipeline Outlook
TradingKey - Amgen closed at $414.61 on September 25, a 2.11% gain. Their pipeline received an infusion of new positive data. The first is from the topline data of the Phase 3 study of dazodalibep for the treatment of Sjögren’s disease. Positive results from this study add a new catalyst to Amgen’s pipeline. IMDELLTRA and MariTide add longer term opportunities to Amgen’s pipeline. With positive results from the pipeline balancing biosimilar competition affecting older products, Amgen’s stock has rebounded from September lows.
Dazodalibep Adds a New Late-Stage Catalyst
Amgen announced the positive topline results from the Phase 3 study of dazodalibep (OASIZ 301) for the treatment of Sjögren’s disease on September 22.
Amgen reported that systemic disease activity was improved at the 48 week mark and that improvements were seen as early as the 4 week mark.
Since there are no Sjögren’s disease-specific drugs that are approved by the FDA, Amgen believes that these results are an important development.
At this time, I view Amgen’s announcement as a positive pipeline event, but not one that yet defines a commercial revenue profile for dazodalibep.
Amgen’s OASIZ 303 Phase 3 study (which is expected to complete in the fourth quarter of 2026) will evaluate patients with high symptom burden and low systemic disease activity, a different Sjögren’s population from OASIZ 301, and will provide further clarity.
The Market Has Already Rewarded the Trial Result
Amgen reported positive Phase 3 topline data for dazodalibep on September 22, and the stock increased 4.34% on that day alone. The stock ended up closing at $414.61 that week. Historically, the market reacts positively to demonstrations of improvement in a drug pipeline.
The challenge is whether Amgen can continue to capture the market's attention on dazodalibep and its other promising pipeline candidates.
OASIZ 301 is another study of dazodalibep, and if the full results do not align positively with the market's expectations as reflected in the topline data, Amgen's stock may experience a setback.
Positive results from OASIZ 303 may strengthen Amgen's beliefs around the separate high-symptom, low-systemic-disease patient population that may benefit from dazodalibep.
IMDELLTRA Adds Another Recent Oncology Catalyst
Positive Phase 3 data for IMDELLTRA was also reported by Amgen this September. The DeLLphi-305 study demonstrated that the combination of IMDELLTRA and AstraZeneca's (AZN) Imfinzi improved overall survival compared to Imfinzi as a stand-alone therapy in the first-line maintenance treatment of a particular type of small cell lung cancer (ES-SCLC).
The study also showed that the combination arm of the trial also showed improvements in progression-free-survival and objective response rate.
Based on the above results, the use of IMDELLTRA may be extended beyond the second-line treatment of ES-SCLC.
The FDA also recently altered IMDELLTRA’s prescribing guidelines to reduce the required monitoring time in an appropriate healthcare setting for the first two doses from 22 to 24 hours to 6 to 8 hours. A shorter monitoring period may improve the inconvenience of the treatment for patients and the treatment center. Whether this improvement positively impacts IMDELLTRA’s commercial potential is to be determined.
Q2 Shows Newer Products Are Already Doing More Work
Amgen's second quarter reported revenue was $10.1 billion, a 10% increase from the previous year. Worldwide product sales increased 9% from the previous year. GAAP earnings per share were $4.37, up from $2.65 the previous year. Adjusted earnings per share increased to $6.29 from $6.02 the previous year. Free cash flow increased to $3.5 billion from $1.9 billion the previous year; operating cash flow was $4.0 billion versus $2.3 billion.
The product mix is interesting.
Sales of Repatha increased 37% to $953 million.
Sales of EVENITY increased 38% to $714 million and sales of IMDELLTRA increased to $288 million from $134 million from the previous year.
Management stated the company’s six key growth drivers, which represent nearly 70% of total product sales, increased 26% from the previous year.
Positive product launches help mitigate declines in older product sales.
Legacy Products Remain a Meaningful Headwind
Sales of EVENITY increased 38% to $714 million and sales of IMDELLTRA increased to $288 million from $134 million from the previous year. Management stated the company’s six key growth drivers, which represent nearly 70% of total product sales, increased 26% from the previous year.
Positive product launches help mitigate declines in older product sales.
Declines in older products
The combination of declines in product sales of Otezla (21%), Enbrel (4%), and Prolia (32%) and XGEVA (34%) offset Amgen’s positive product launches.
MariTide Remains a High-Value but High-Risk Opportunity
Those declines will need to be countered by positive sales from more recently launched products, Repatha, EVENITY, and IMDELLTRA.
Amgen appears to be successfully replacing older products. The company has a narrower margin of positive product launches. Should one of Amgen’s largest products experience a significant decline, the positive impact on profits would not be sufficient to offset older, larger, declining products.
Olpasiran Faces a Higher Evidence Bar
Complications arose with Novartis’s Lp(a) program this month as well. Pelacarsen did not reach its cardiovascular endpoints in Lp(a)HORizON and Amgen’s olpasiran was not impacted by these results. The molecules and trial programs are different, but pelacarsen’s failure raises the evidence bar for the Lp(a) thesis. Amgen’s Phase 3 OCEAN(a)-Outcomes and OCEAN(a)-PreEvent programs still need to demonstrate that lowering Lp(a) translates into fewer cardiovascular events. Amgen has other drivers for their cardiovascular program.
Guidance Still Supports a Solid Earnings Base
Amgen has a solid base business. Guidance for 2026 is $38.2 - $39.4B in revenue and $15.80 - $17.08 in EPS (GAAP) and $22.30 - $23.50 (adjusted). Amgen reported $14B cash and $57.3B debt as of June 30. The debt load remains material, but it does not show that business cash flow is failing to cover capital spending: Q2 operating cash flow was $4.0 billion versus about $0.5 billion of capital expenditures. Amgen is trading at approximately 18.6 times the low end and 17.6 times the high end of the adjusted EPS range from 2026.
Amgen Technical Analysis: AMGN Reclaims $410 as $418.73 Breakout Comes Into Focus
Amgen rose to $414.61 in its latest completed trade after bouncing from $374.76 in September.
I think the recovery above $410.08 to $410.31 is constructive, and is all the more bullish as it took out both the major moving averages.
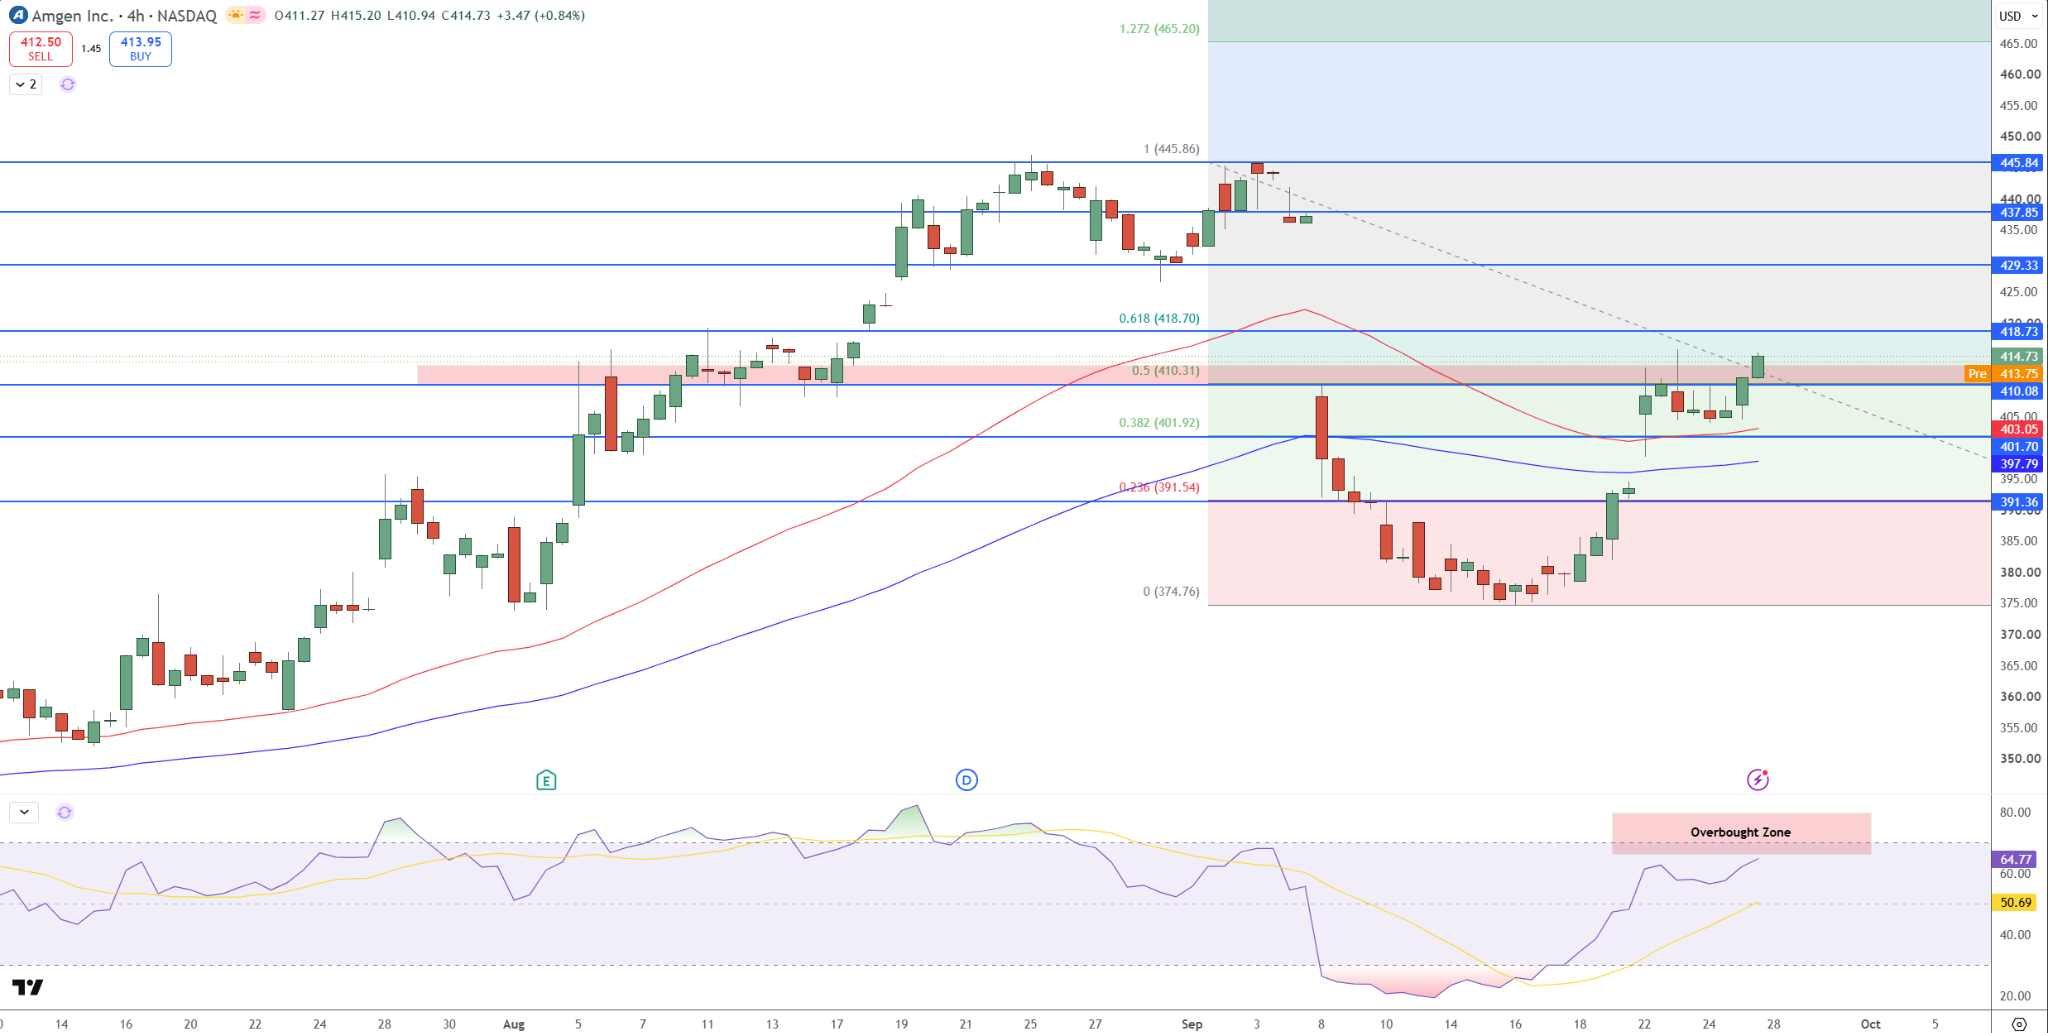
Amgen Stock Price Chart - Source: Tradingview
From a price structure perspective, the recovery looks good.
RSI at 65 is a bit above its signal line at 51, but is still well away from overbought territory at 70.
This suggests that the upside potential is not fully realized, and that the 418.70 to 418.73 area should see further upside.
A break above the 418.73 area should target the 429.33 and 437.85 levels next, and support a continuation of the bullish bias.
The 445.84 level should be in focus above.
Support should come in at 410.08 to 410.31, with a trading close back below this area negating the breakout targeting 429.33.
Looking for a lower objective would put the moving averages at 403.05 to 397.79 in focus, with 391.36 next below that.
So far, the bullish bias is working, and I am looking for a break of 418.73.
Why is Amgen stock in focus now?
The focus on Amgen is due to Phase 3 topline results for Sjögren’s disease, ongoing results from the clinical trial, IMDELLTRA, for the treatment of small-cell lung cancer, and the declines in older franchises being offset by products like Repatha.
What level confirms a stronger AMGN breakout?
A bullish reversal in the 4-hour timeframe above $418.73 would clear the next Fibonacci level resistance and call the $429.33 area into play. A failure to hold above $410.08 would negate the current bounce in the price of the stock.
Bottom Line
The AMGN stock bulls were given a boost in September with the progress made in the company's pipelines.
Dazodalibep and IMDELLTRA both have ongoing and upcoming clinical trials, respectively. In addition, MariTide is a potential long-acting antibody-peptide conjugate that activates the GLP-1 receptor and antagonizes the GIP receptor for the treatment of obesity.
The main risk is unknown.
Declining older drugs, more data from clinical trials for dazodalibep, and the potential failure of MariTide to meet expectations in its ongoing trials are the main unknowns.
From a technical analysis perspective, the stock remains bullish as long as it trades above $410.08. A clear break above $418.73 would give the trend a higher probability of advancing to $429.33, and a break below $410 would increase the probability of a deeper correction to 403-398.
Recommended Articles


