


Dell Stock Rallies Before Earnings as AI Demand Builds - Can DELL Break $472?
TradingKey - Dell Technologies (NYSE: DELL) is trading at around $451.50 as of August 26, having rebounded sharply ahead of the release of its fiscal second quarter 2027 results on September 1. This earnings setup is severe: Dell commenced the quarter with record momentum in AI and new infrastructure deals and set a full year goal to bring in $60 billion from AI servers. The stock has had a big rally in 2026. The next earnings report needs to demonstrate that backlog is not just revenue, but profit and cash flow.
AI Servers Have Turned Dell Into a Different Growth Story
Dell’s fiscal Q1 results surprised to the upside. The company reported record revenue of $43.8 billion, up 88% from the prior year, and non-GAAP EPS of $4.86, up 214% from the prior year. The Infrastructure Solutions Group provided revenue of $29.0 billion, including $16.1 billion from AI optimized servers. Dell also announced $24.4 billion of AI orders during the quarter and increased its fiscal 2027 goal for AI server revenue to approximately $60 billion.
This figure is important because Dell commenced fiscal 2027 with a booked AI backlog of $43 billion from AI- optimized server orders in excess of $64 billion during fiscal 2026. This provides management good runway for revenue, but also adds pressure on execution. Investors will be waiting for evidence that the server shipments are supporting margins, rather than eroding margins from high GPU content.
August Deals Expand the Opportunity Beyond GPU Servers
Dell has added several August catalysts before its earnings. Volta selected Dell to provide its PowerRack Systems and PowerEdge XE9812 servers with NVIDIA accelerators to support its 133 MW AI Factory in Norway. Volta expects its near-term pipeline to span beyond 1 GW across North America and Europe, posing more potential business for Dell in supporting the infrastructure.
Dell also developed its offering of agentic-AI, in partnership with NVIDIA, by integrating local enterprise infrastructure with Nemotron models and NeMo Switchyard routing. Independently, Dell ObjectScale now supports 245.76 TB KIOXIA SSDs, allowing up to 9.83 PB of raw capacity in 2U. These additions are important, as Dell is now looking to provide more of an AI stack, including compute, storage, deployment, and services, vs. before, when Dell would only compete on server hardware more.
Sept. 1 Earnings Need to Beat an Already High Bar
Dell has stated that its fiscal Q2 2027 results will occur on September 1 at 3:30 p.m. CDT. Market analysts currently project revenue to be around $44.9 billion and $4.89 of adjusted EPS. Dell's revenue guidance is $44 billion to $45 billion, while its non-GAAP EPS guidance is $4.80 in the mid-range. Evercore ISI has an Outperform view and an $550 price target. They believed that demand for AI-specific servers is greater than supply and that Dell could surprise earnings and raise its forward earnings expectations.
Current betting expects an earnings move of approximately 11%. Investors pay the most attention to AI-specific server orders, how much of the backlog is converted into sales, ISG operating margin, and how cash flow and the $60 billion goal of AI-specific server revenue are impacted. Strong revenue growth may not be enough if there is a steep increase in working capital or there is a decrease in profit margins.
The Main Risk Is Profitability, Not Demand
Demand for the products Dell sells is less difficult to analyze. AI-specific servers potentially provide lower margins, making profitability the more difficult dilemma.
The majority of the value of an AI-specific server is provided by other companies. At least in Q1, Dell's ISG operating income was $3.1 billion, which is up 206% from last year, and ISG segment margins grew to 10.5%.
Supply constraints continue to be problematic as AI infrastructure demand competes with other industries for available memory, processors, and networking equipment. While part of anticipatory inventory management, Dell will have to place orders for components earlier. This will result in a larger working capital requirement. Note that the strong quarter will require order growth resulting in stable margins and cash that is applicable to operations.
Key Levels
Dell is currently trading at $451.50, facing immediate resistance at $472.01, with an upside target zone between $500.00 and $513.09, and major resistance higher up at $536.29. On the downside, primary support rests at $425.12, followed by moving-average support around $417.58, and lower support at $390.81.
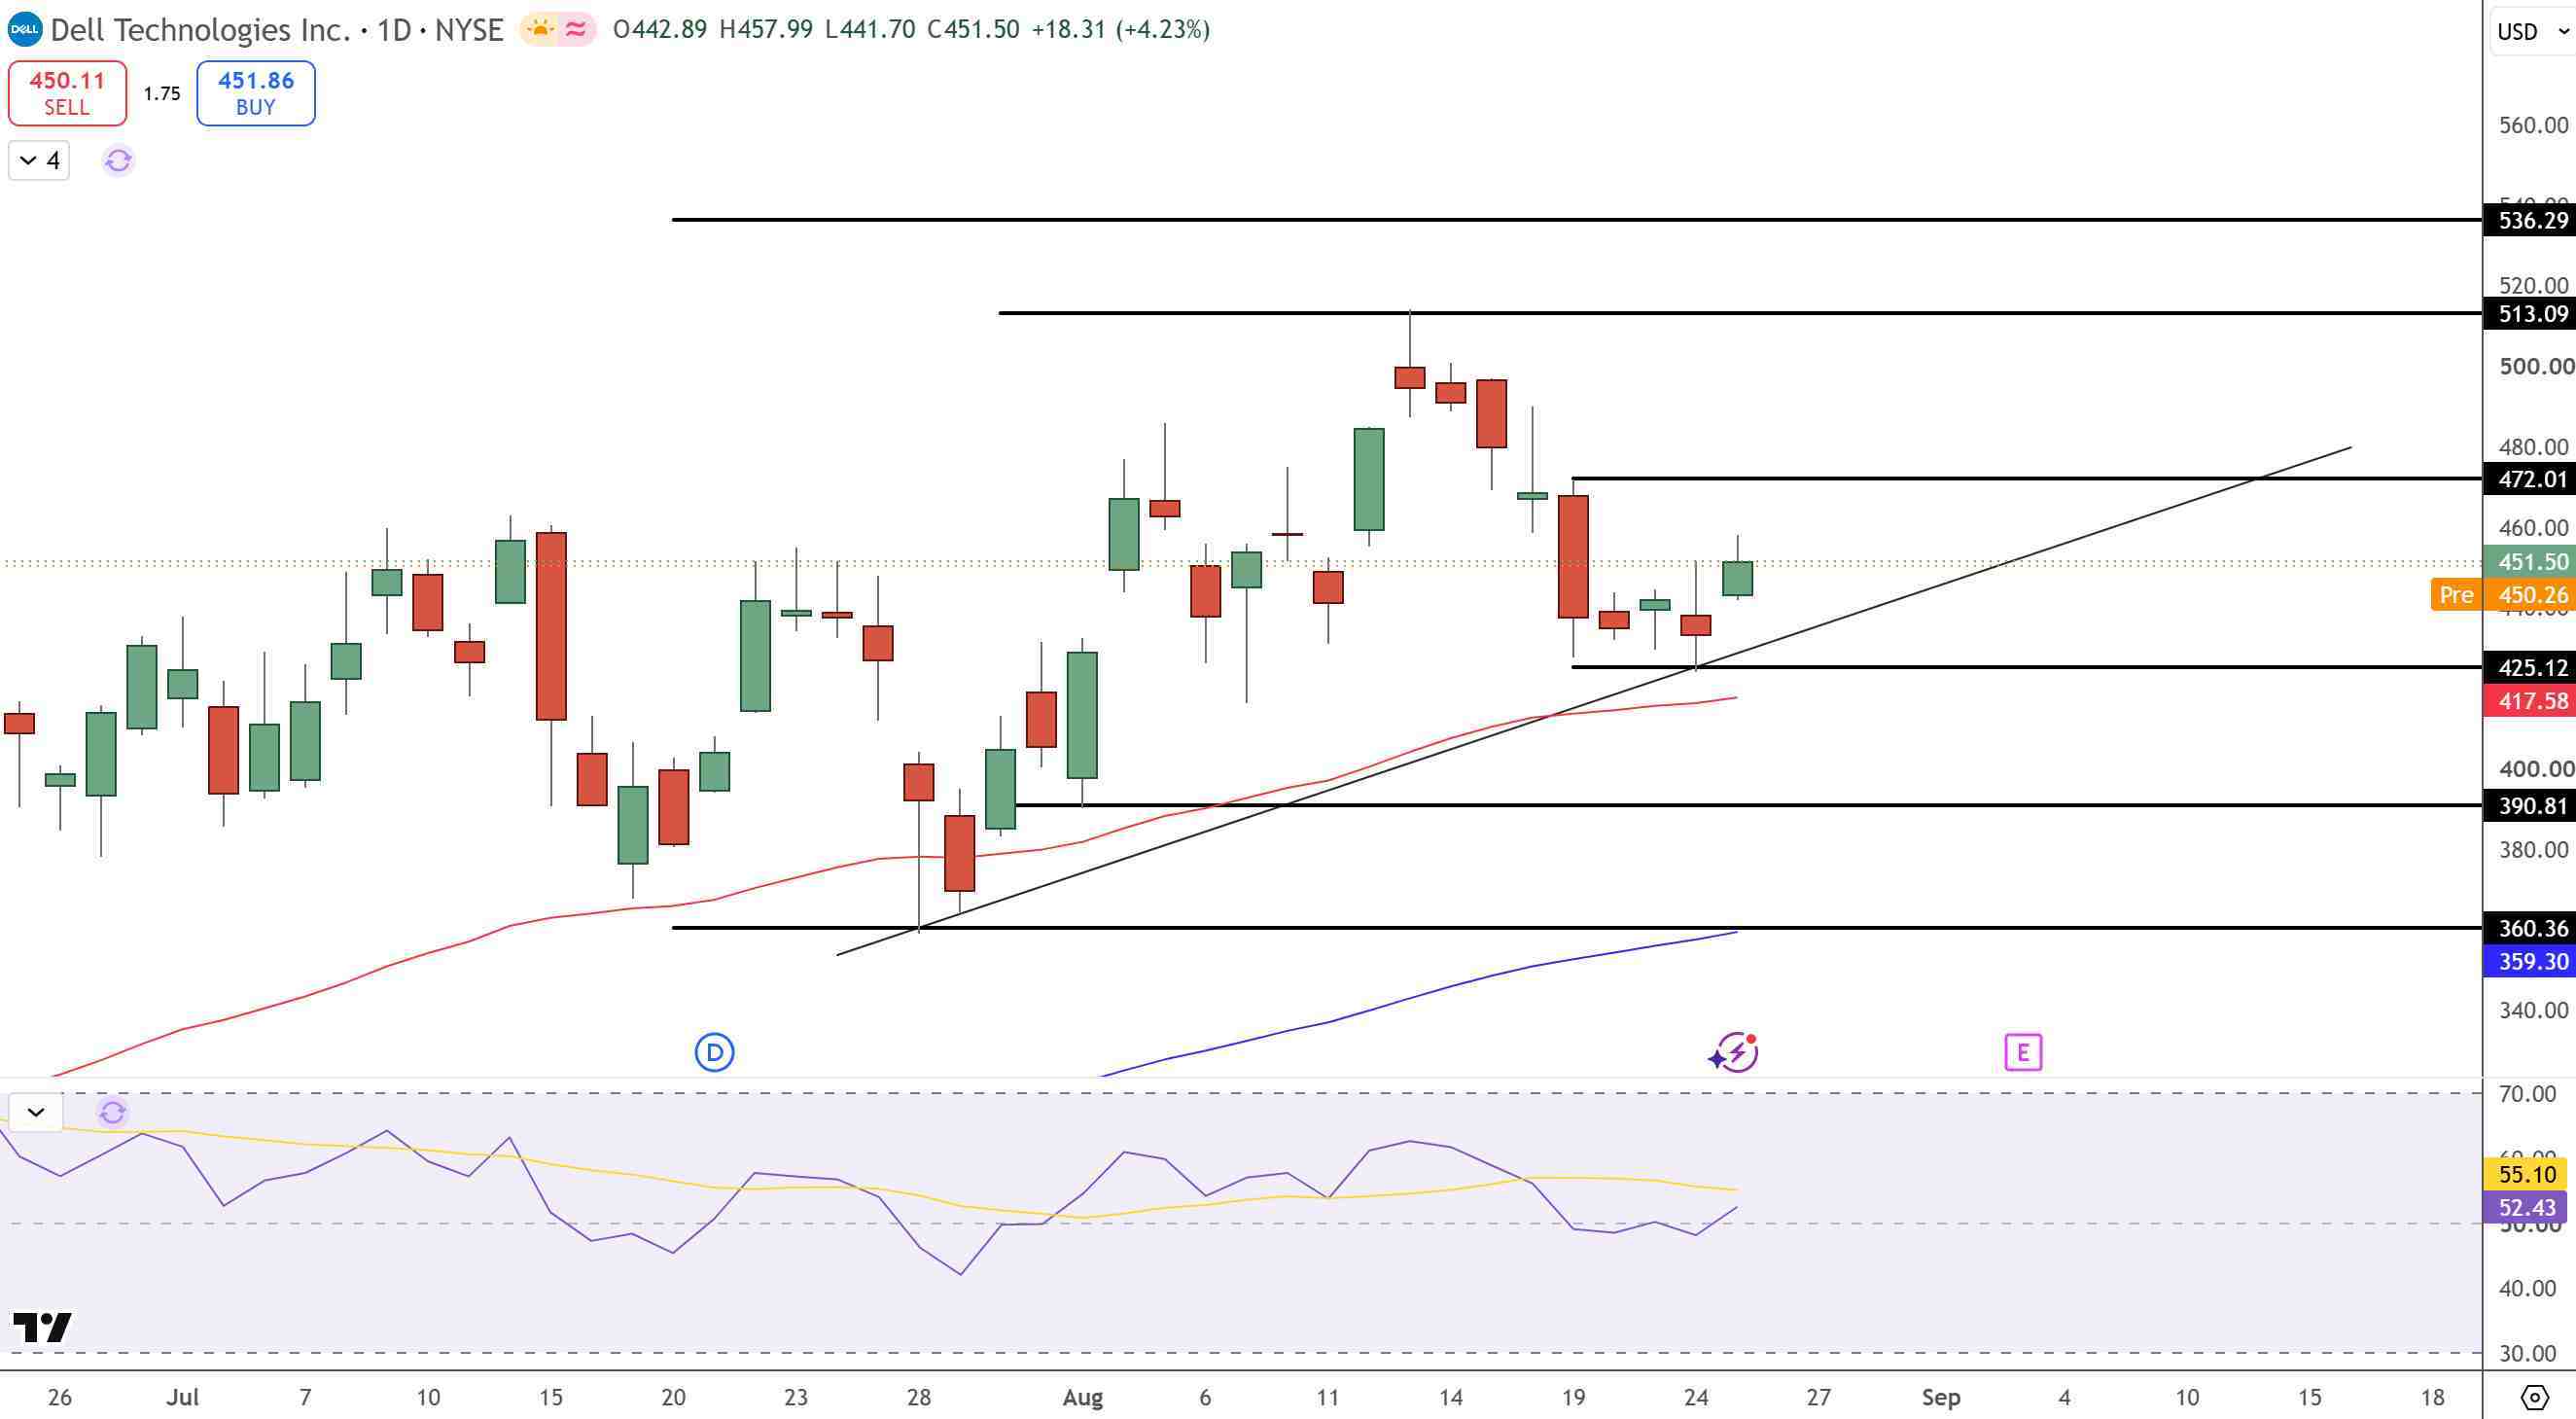
Dell Price Chart - Source: Tradingview
Technically, DELL has rebounded from $425.12 and remains above the rising trendline and moving-average support near $417.58. RSI around 52 is neutral rather than overbought, so the recovery still has room to develop. A daily close above $472.01 would strengthen the breakout case toward $500-$513.09, while a break below $425.12 would weaken the higher-low structure and put $417.58 back in play.
Why is Dell stock rising before earnings?
The latest rebound reflects renewed analyst optimism, strong AI-server demand and expectations that Dell can convert its large backlog into another quarter of rapid infrastructure growth. Fresh August announcements with Volta and NVIDIA have also reinforced the view that Dell is expanding beyond individual server sales into broader AI-factory and enterprise-AI deployments.
What matters most in Dell's Sept. 1 earnings report?
Investors should focus on AI-server revenue and orders, backlog conversion, ISG margins, operating cash flow and any change to the $60 billion fiscal 2027 AI-server revenue target. A guidance increase would support the bullish case, but weaker margins or poor cash conversion could offset a headline revenue beat.
Bottom Line
Dell enters September 1 earnings with stronger fundamentals than most traditional hardware peers, but expectations are now equally strong. The $43 billion opening AI backlog, $24.4 billion of Q1 AI orders and fresh infrastructure deals support continued growth. At about $451.50, the stock is recovering but still needs a clean break above $472.01 to confirm another technical leg higher. If earnings show rising AI revenue alongside resilient margins and cash flow, $500-$513 becomes a credible next zone. If execution slips, $425 is the level that separates a normal pullback from a deeper loss of momentum.
Recommended Articles


