

Palladium (XPDUSD) Volatility Intensified on Sep 29: What to Watch

Source Tradingkey

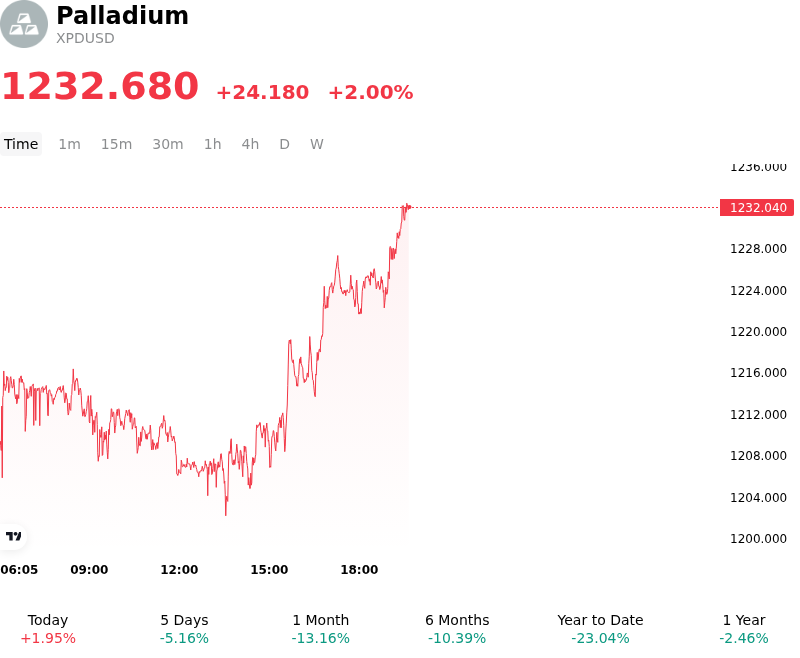
Palladium (XPDUSD) is up 2.00% at Sep 29 07:40(ET), now at $1232.68, with a 7-day down of 5.85%.
SummaryOverview

What is driving Palladium (XPDUSD)’s stock price up today?

Palladium prices recorded a solid intraday advance as a combination of technical short covering and persistent underlying supply concerns triggered a rebound following recent multi-month lows. Institutional traders moved to cover heavy speculative short positions as spot prices bounced off key technical support levels. The turn higher was supported by ongoing fragility across primary mining supply, particularly persistent operational and infrastructure hurdles in South Africa alongside trade uncertainties surrounding Russian origin material. While broader macroeconomic sentiment and fluctuating interest rate expectations had weighed on the complex in preceding sessions, physical tightness in prompt material availability encouraged opportunistic buying.

From a fundamental perspective, the market continues to navigate conflicting long-term and short-term signals. On the demand side, the structural transition toward electric vehicles presents a known long-term headwind for catalytic converter demand in the automotive sector. However, vehicle production numbers in key emerging regions and continued utilization of hybrid platforms have provided more resilient baseline consumption than pessimistic market forecasts had priced in. Concurrently, mine output from primary global producers remains constrained. Reduced primary production, coupled with depleted above-ground producer inventories following years of stockpile draws, has kept the physical market balance tighter than headline futures positioning suggests.

This session's upward movement primarily represents an event-driven technical relief rally amplified by stretched short positioning, rather than a fundamental shift in broader structural trends. With speculative positions heavily slanted to the short side on futures exchanges, even modest upticks in physical spot buying or subtle shifts in US dollar trajectory can spark rapid position squaring. Investors continue to monitor energy market developments, central bank monetary policy expectations, and real yield movements for macro directional cues. In the near term, palladium remains subject to elevated volatility as institutional market participants weigh terminal automotive demand risks against persistent supply vulnerabilities across core producing nations.

Technical Analysis of Palladium (XPDUSD)

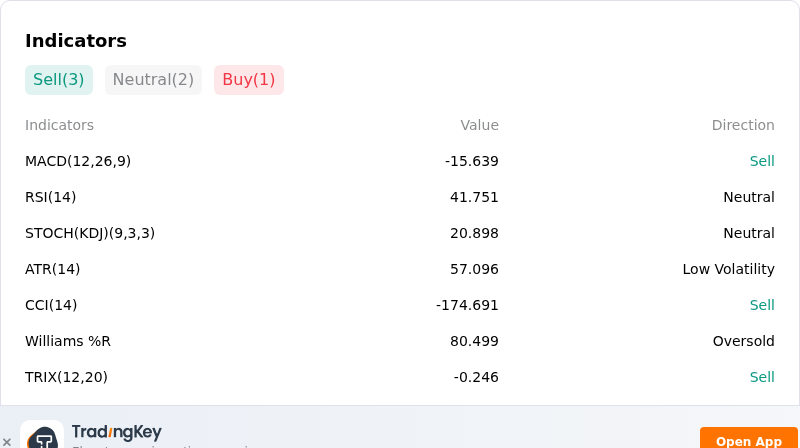
Technically, Palladium (XPDUSD) shows a MACD (12,26,9) value of -15.639, indicating a sell signal. The RSI at 41.751 suggests neutral condition and the Williams %R at 80.499 suggests oversold condition. Please monitor closely.
IndicatorAnalysis

More details about Palladium (XPDUSD)

Recent Events and Risks:

  • Automotive Demand Deterioration: Slowing global vehicle sales and the ongoing transition toward battery electric vehicles—which do not utilize catalytic converters—continue to erode primary industrial demand for palladium, creating sustained intraday downside risk for XPDUSD.
  • Platinum Substitution and Secondary Supply Growth: Automakers continue to substitute palladium with lower-cost platinum in gasoline exhaust systems, while expanding secondary supply from PGM scrap recovery dampens physical market deficit projections.
  • Easing Geopolitical and Production Risk Premiums: Relative stability in mine production and export flows from major PGM hubs, including South Africa and Russia, has unraveled short-term supply scarcity premiums and triggered technical selling near key resistance levels.
  • Macro Headwinds and Speculative Liquidation: Persistent U.S. dollar strength and elevated real Treasury yields increase holding costs for non-yielding precious metals, leaving thin-liquidity palladium futures vulnerable to systematic long liquidations and risk-off unwinds.
Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
【Daily Brief】10-year Treasury yield briefly tops 5%, S&P 500 slips to 7,602 and the dollar firms at 99.3 as the Fed's decision eve beginsThe 10-year Treasury yield touched 5.014% on Monday — its first print above 5% since October 2023 — while the S&P 500 closed 0.48% lower at 7,619.98 and the dollar index firmed to 99.3. Here is the full market wrap ahead of Wednesday's FOMC decision, the dot plot and the August retail sales report, plus today's CLARITY Act Senate vote.
Author  Irene Q.
Sep 15, Tue
The 10-year Treasury yield touched 5.014% on Monday — its first print above 5% since October 2023 — while the S&P 500 closed 0.48% lower at 7,619.98 and the dollar index firmed to 99.3. Here is the full market wrap ahead of Wednesday's FOMC decision, the dot plot and the August retail sales report, plus today's CLARITY Act Senate vote.
placeholder
October hike odds climb toward 60% as Goldman and BofA both flip — what Warsh's "dose of accommodation" really changedRate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
Author  Irene Q.
Sep 23, Wed
Rate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
placeholder
Four jobs reports in five days: what JOLTS, ADP, claims and the September payrolls mean for the October Fed decisionThe US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
Author  Mitrade
Sep 28, Mon
The US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
placeholder
Nvidia's $150 billion buyback landed — and the AI sector fell anyway. That's the signal worth tradingNvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
Author  Irene Q.
20 hours ago
Nvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
placeholder
The 30-year Treasury just hit a 22-year high — and the bond market is not pricing the Fed, it is pricing the deficitThe 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
Author  Irene Q.
19 hours ago
The 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
goTop
quote