


US September CPI preview: inflation set to hit 3.7% — will the Fed hike in December?
Mitrade Insights — Wednesday's US September CPI is the inflation print that decides where the Federal Reserve's next hike lands — and markets are already leaning toward December. The consensus sees headline inflation at 3.7% y/y, from 3.4%, with core holding at 0.2% m/m; CME FedWatch prices a December hike near 70%. The dollar closed Friday at 101.9 — its strongest level in six months. The stakes compound this week: bank earnings open Tuesday, CPI lands Wednesday, and retail sales follow Thursday.
What Wednesday's report will show
| Metric | September consensus | August |
|---|---|---|
| Headline CPI, y/y | 3.7% | 3.4% |
| Headline CPI, m/m | 0.6% | 0.4% |
| Core CPI, y/y | 2.5% | 2.4% |
| Core CPI, m/m | 0.2% | 0.3% |
The mix matters more than the headline. Barclays estimates energy prices rose about 5% m/m and gasoline nearly 9%, while core goods and shelter are expected to stay tame — a hot-looking headline with a calm core is precisely the combination the Fed can look through.
If energy alone drives the pickup, the Fed can treat it as an energy story and keep its options open; if rent, used cars or services re-accelerate, the sticky-core narrative comes back with force. In practice that makes one line of the BLS detail the single most important: gasoline, and whether it lands anywhere near Barclays' 9% monthly estimate.
Why December is the live meeting
The Fed lifted rates to 3.75% ~ 4.00% on September 16 by a unanimous 12-0 vote, and the September minutes, published on October 7, showed most participants judged that "one more increase by year-end" would be appropriate — without urgency for October. The pricing agrees: CME FedWatch has December near 70% and a hold on October 28 near 80%. Barclays expects exactly that path — hold in October, hike in December; Goldman Sachs leans December as well. That makes Wednesday's number the last clean read on inflation before the December decision (FOMC October 27–28, then December 8–9).
Positioning around the print is unusually clean. The Treasury market spent the week defending the 5% line on the 10-year, which closed at 5.244% after Wednesday's 5.364% spike — the highest since 2007; the dollar sits at a six-month high; and the S&P 500 is just 0.1% from its record. Each of those three prices embeds the same forecast: inflation cooling slowly enough to keep the Fed patient, not fast enough to force its hand. CPI is where that forecast gets audited.
Two paths diverge from here. A skip in October followed by a December hike would top the funds rate out at 4.00% ~ 4.25%, and the debate shifts to how long it stays there. If instead the core runs hot enough to put October back in play, the front end reprices violently — futures currently put only about a 20% probability on a hike on October 28.
The dollar is leaning hawkish
The dollar is where this trade expresses itself cleanly. The US Dollar Index closed Friday at 101.903, up 0.08%, after a high of 102.03 — its strongest zone in six months. The setup is asymmetric: with a December hike already about 70% priced, the dollar needs a hot print to break the 102.000 line decisively; a soft core would send it straight back toward 100.000. It is also the cleanest read across the majors: with USD/JPY pinned near 158 and AUD/USD hovering around 0.70, the surprise will set the tone for both into the weekend. Gold is the other half of the dollar trade — its first weekly gain in three weeks, a 1.47% Friday bounce to $4,194.645, needs a soft core to extend.
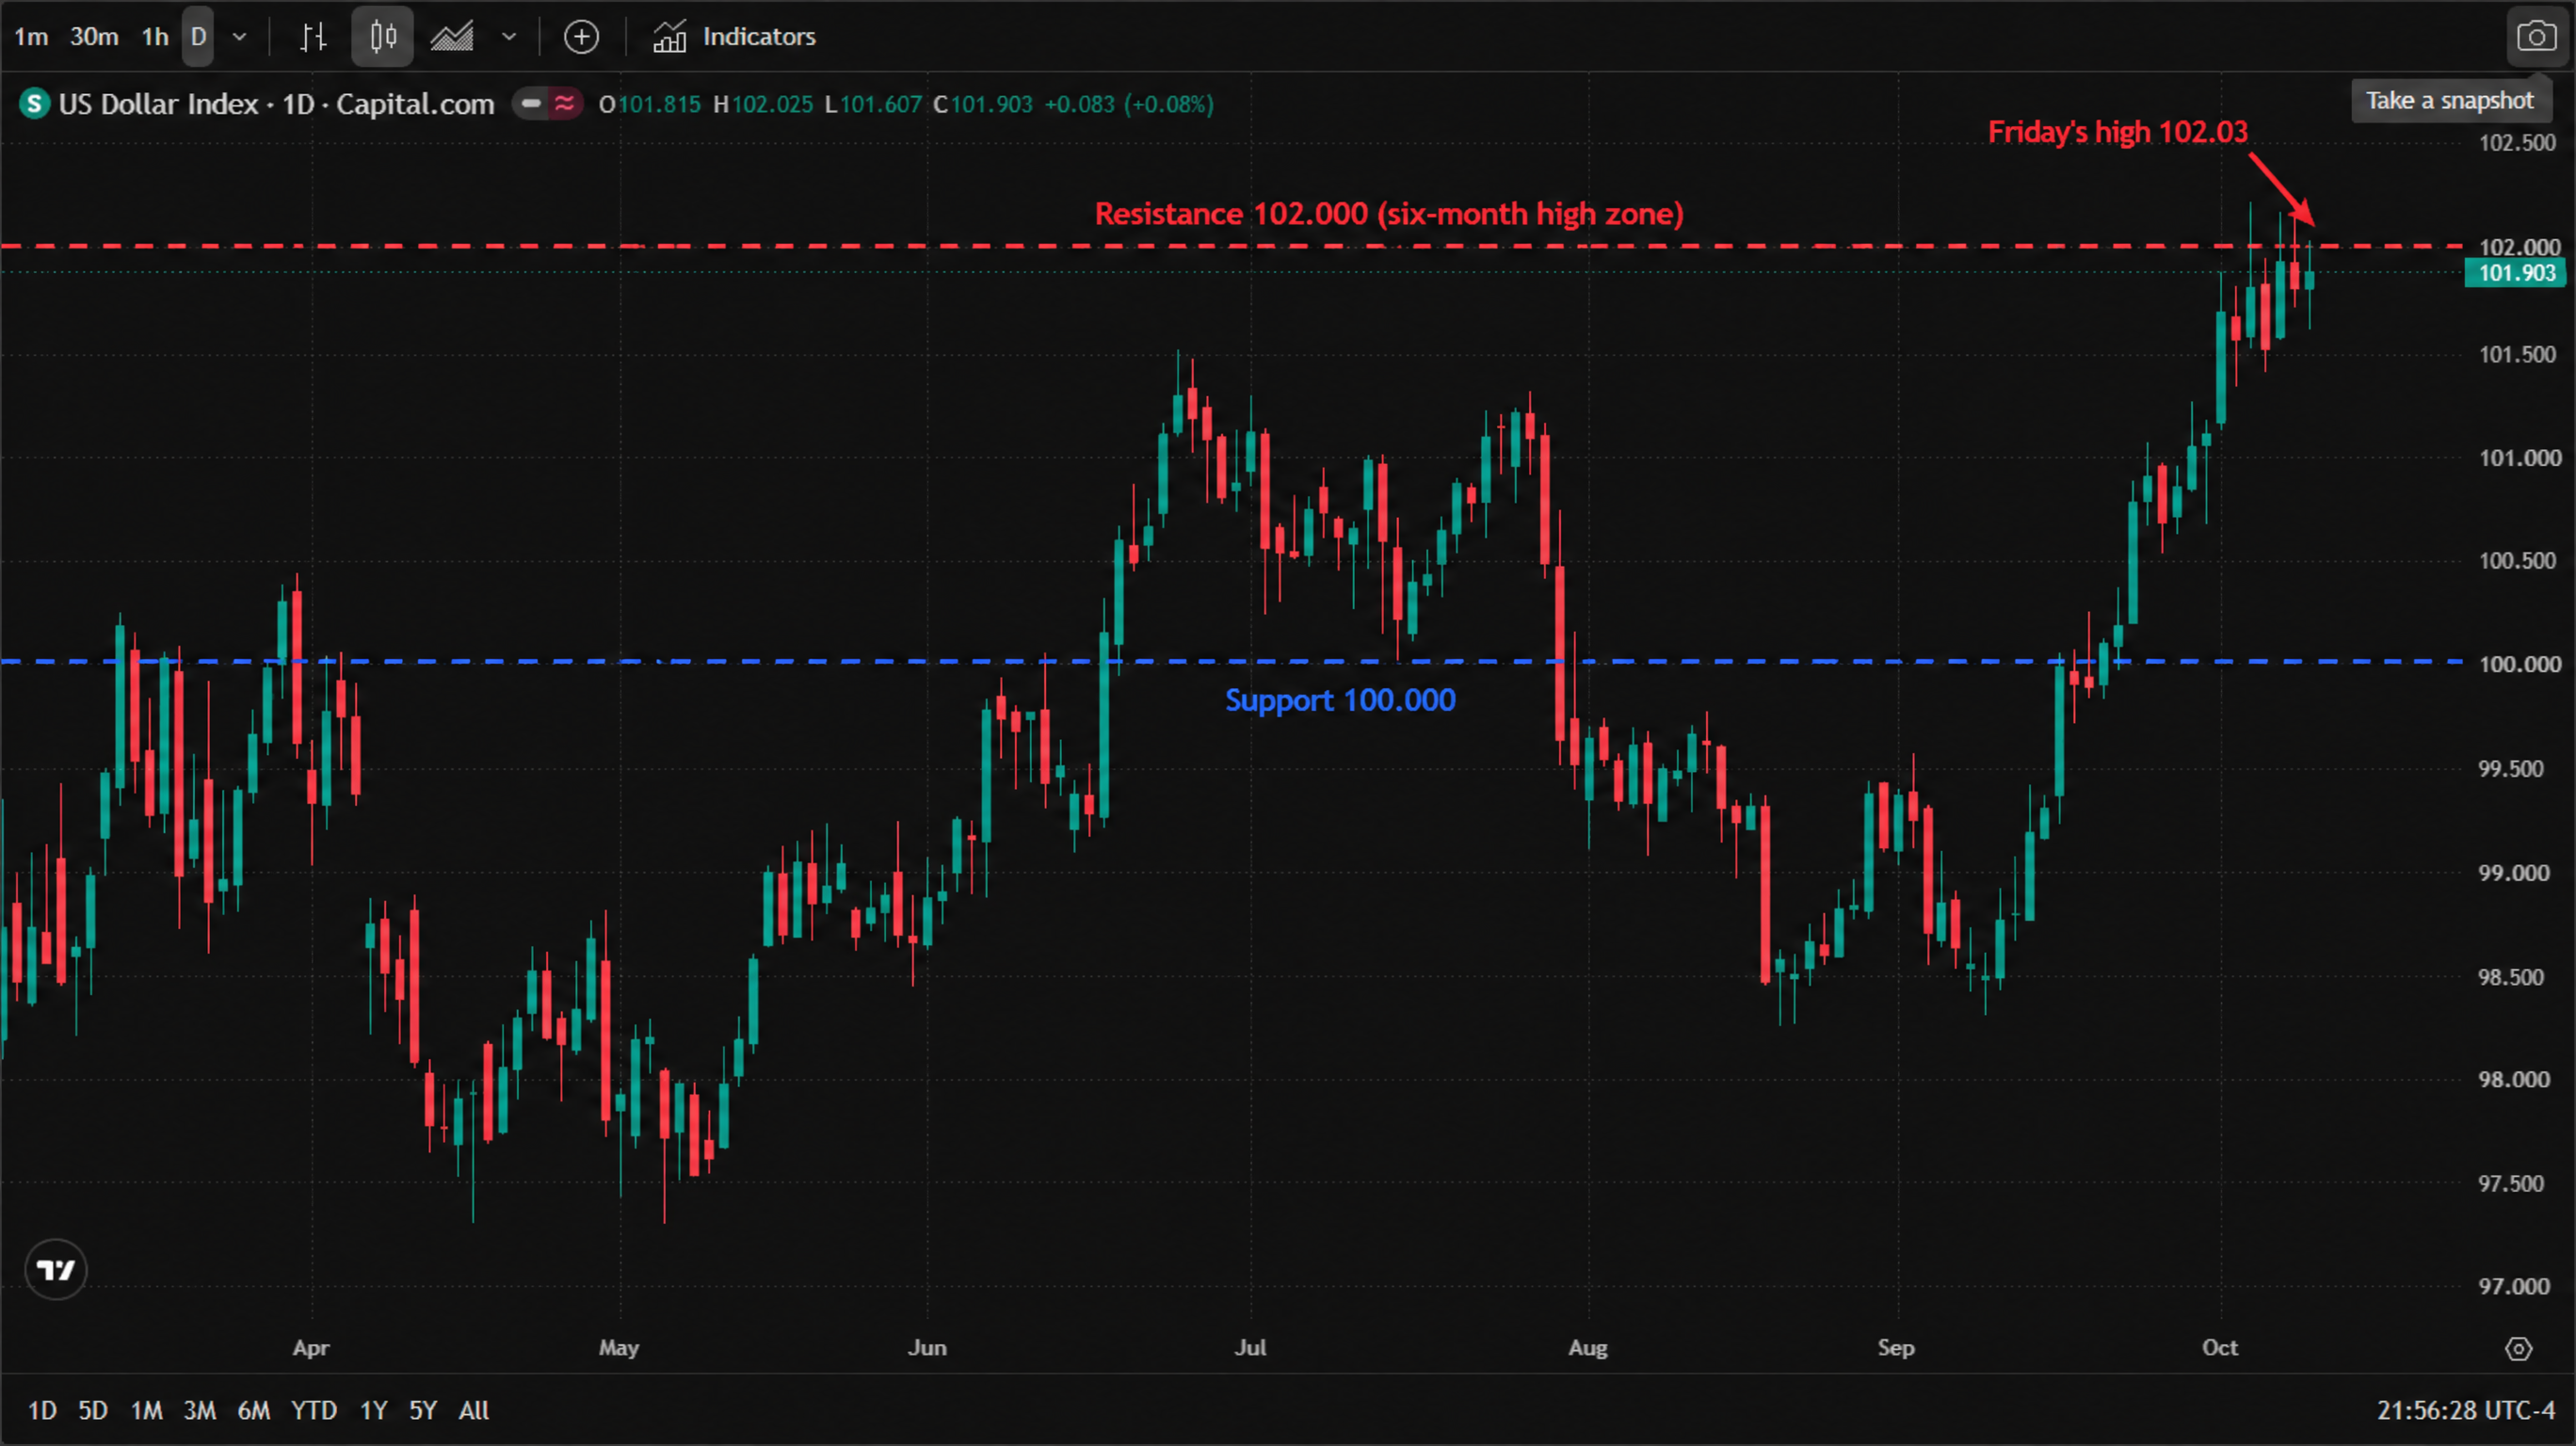
* Chart source: TradingView official chart screenshot, data feed Capital.com (US Dollar Index).
Two scenarios for CPI day
Scenario A — core at 0.2% m/m or below. The December hike stays priced but not nailed down; the dollar eases back toward 100.000, the 10-year yield slips under 5.00%, and rate-sensitive assets celebrate: gold extends its rebound above $4,200 and the S&P 500 takes another run at its 7,818.93 record close. A core at 0.2% or softer is the print that lets the rally broaden beyond tech.
Scenario B — core at 0.4% or hotter. December moves from "likely" to "locked in", the dollar clears 102.000, and the 10-year retests 5.36% — Wednesday's spike high, the highest since 2007. Gold's rebound stalls at $4,200, and equities give back the week's gains. Watch the 5.36% spike high on the 10-year — a clean break turns a repricing into a regime shift.
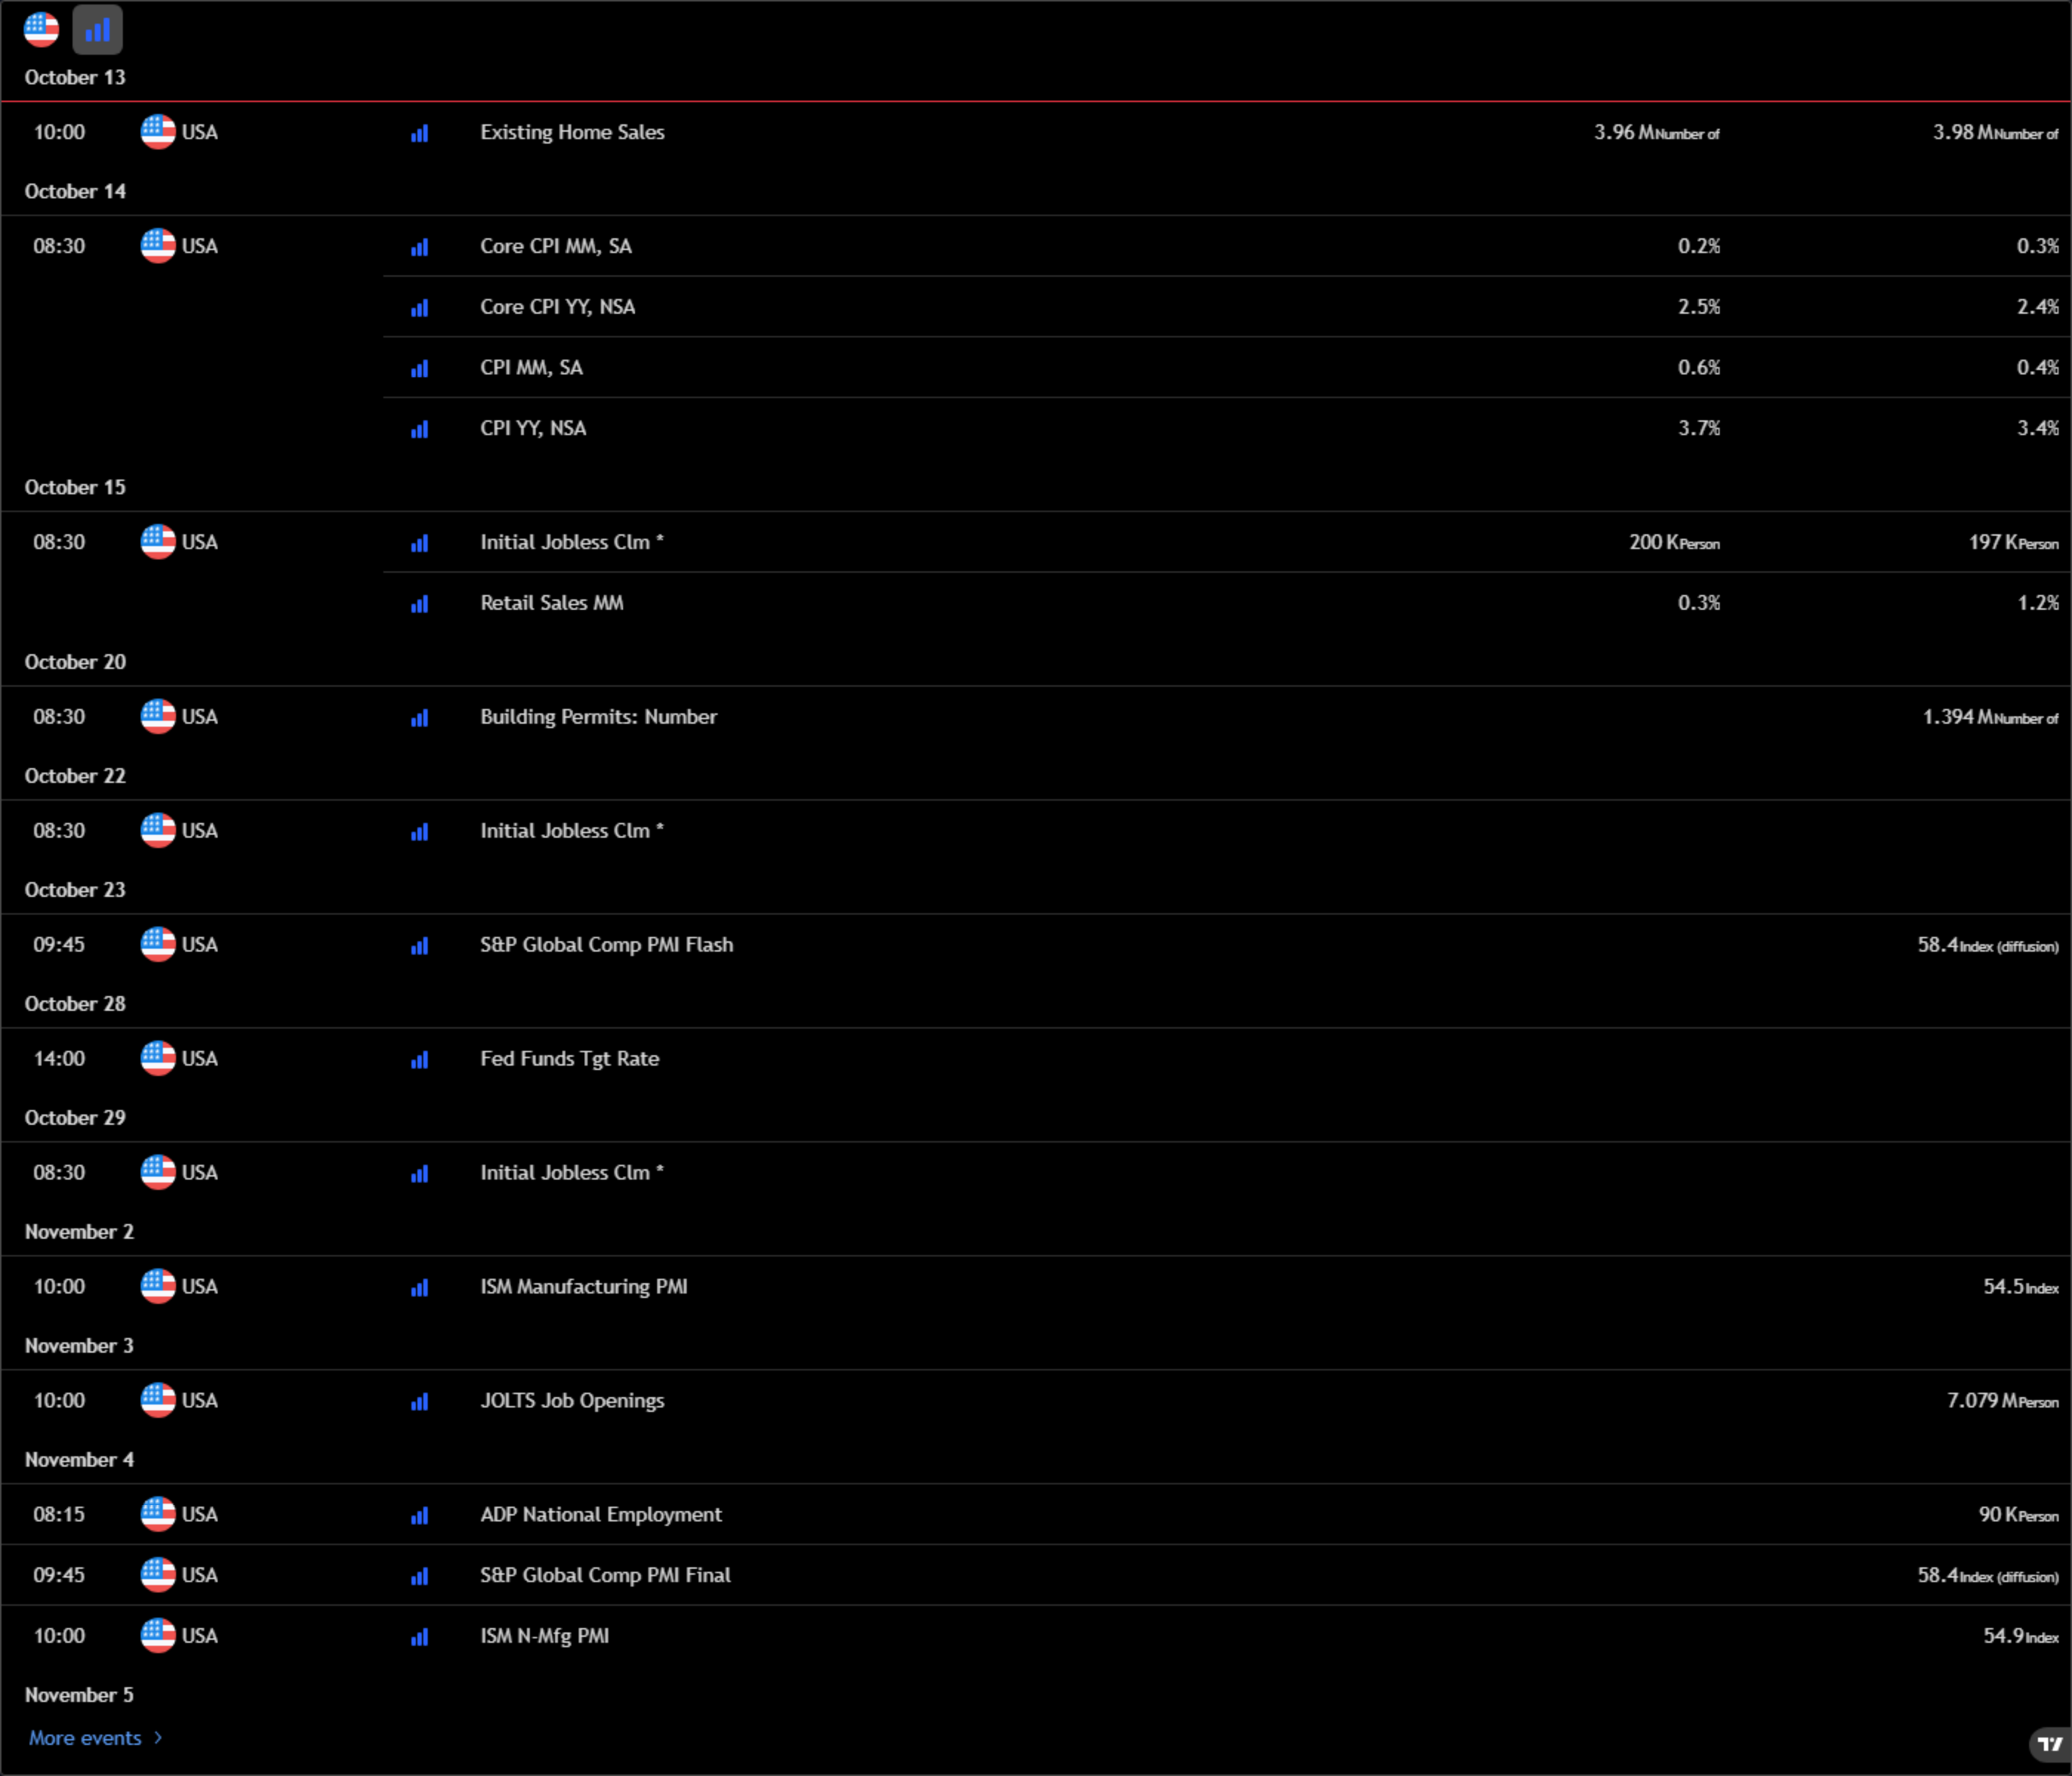
* Image source: TradingView official Economic Calendar screenshot.
Bottom line: the consensus says the headline re-accelerates while the core cools — a combination that keeps a December hike alive without forcing the Fed's hand. The dollar at a six-month high says the market believes it. Wednesday's number decides who blinks first. One print, three assets: the dollar, gold and the record-setting index all trade off the same 8:30 a.m. ET release.
Disclaimer: All data cited in this article is drawn from public exchange records, the US Treasury par yield curve, CME FedWatch, LSEG consensus estimates and news agency reporting, and is provided for information purposes only. It is not investment advice. CFD trading carries a high level of risk to your capital.
Related reads: Gold falls to a two-month low as real yields bite — can $4,000 hold? · US August CPI lands tonight: after a 5.4% PPI shock, will the Fed hike on September 16?
Read more
Before making any trading decisions, it is important to equip yourself with sufficient fundamental knowledge, have a comprehensive understanding of market trends, be aware of risks and hidden costs, carefully consider investment targets, level of experience, risk appetite, and seek professional advice if necessary.
Furthermore, the content of this article is solely the author's personal opinion and does not necessarily constitute investment advice. The content of this article is for reference purposes only, and readers should not use this article as a basis for any investment decisions.
Investors should not rely on this information as a substitute for independent judgment or make decisions solely based on this information. It does not constitute any trading activity and does not guarantee any profits in trading.
If you have any inquiries regarding the data, information, or content related to Mitrade in this article, please contact us via email: insights@mitrade.com. The Mitrade team will carefully review the content to continue improving the quality of the article.


