


Meet the Ultra-High-Yield Dividend Stock That Has Doubled the S&P 500's Returns This Year
Key Points
With a 5.8% yield, Altria is one of the highest-yielding stocks in the S&P 500.
Altria is a Dividend King, with 57 consecutive years of annual payout increases.
The tobacco company focuses more on growing earnings per share than revenue.
- 10 stocks we like better than Altria Group ›
Plenty of stocks pay dividends, but not all of those qualify as true dividend stocks. Tobacco giant Altria (NYSE: MO) does.
Altria is a poster child for dividend stocks, routinely boasting one of the highest yields in the S&P 500 (SNPINDEX: ^GSPC). This year, though, the stock has displayed more of the characteristics of a growth stock than a typical income stock. Through the market close on Oct. 12, Altria was up by 28% compared to the S&P 500's 13%.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
After that impressive run-up so far in 2026, is the stock still a good buy?
Image source: The Motley Fool.
A premier dividend stock
Despite its unusual price gains, the appeal of Altria's stock is undoubtedly based on its dividend. The company is well aware that those quarterly payouts are why some investors flock to the stock, so it prioritizes maintaining and increasing them.
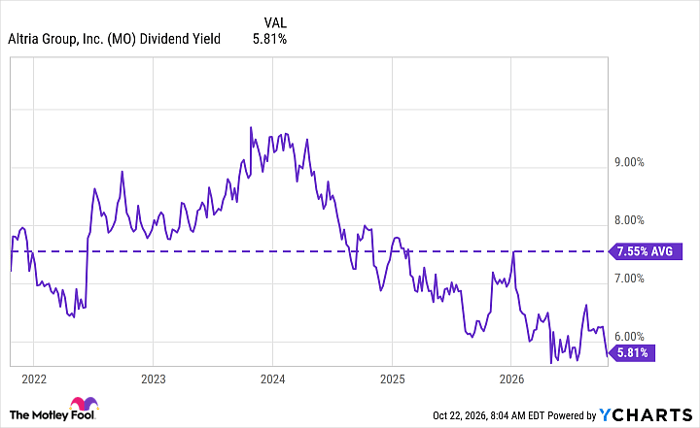
At the current share price, Altria's yield is 5.8%, which is more than 5.5 times what you'd get from an S&P 500 ETF today, but still less than its average over the past five years.
MO Dividend Yield data by YCharts.
High yield aside, Altria's dividend has been the definition of consistency. The company is a Dividend King (a company with at least 50 consecutive years of dividend increases). Its streak now stands at 57 straight years. Of the thousands of stocks trading on the U.S. market, only 25 have longer dividend-hiking streaks.
Using pricing power to keep the train rolling
Altria has been the country's leading tobacco company for quite some time, leaning on its iconic brands like Marlboro, Copenhagen, Black & Mild, and others.
The nature of its business has been a double-edged sword over the past decade or so. On one hand, people are smoking cigarettes much less. A recently published report shows the smoking rate among U.S. adults at 9.9%, the lowest percentage ever recorded. This inevitably affects the country's largest cigarette producer.
On the other hand, the tobacco industry comes with lots of pricing power because many smokers are brand loyal and buy their preferred brand regardless of price. So, while Altria's cigarette sales volumes have been falling, it has offset some of those declines by steadily raising prices.
Investors don't expect huge revenue growth from Altria, so flat or occasional declines aren't deal-breakers. As long as its business is healthy enough to keep the dividends coming, many investors are perfectly content.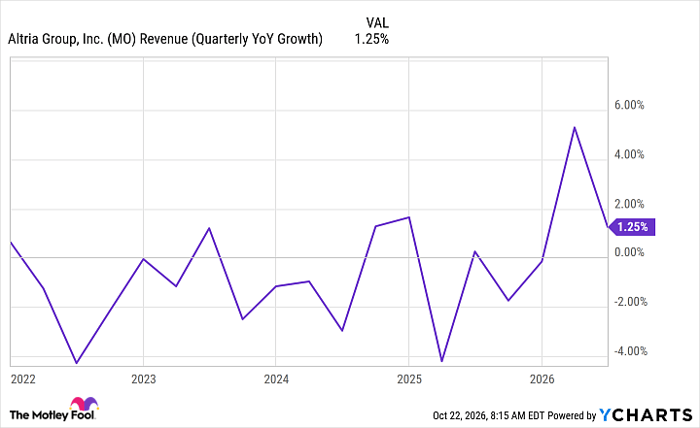
MO Revenue (Quarterly YoY Growth) data by YCharts.
Altria is generally more concerned with its earnings per share (EPS), because earnings are what fund its dividends and its stock buybacks. In the second quarter, its adjusted EPS grew 2.8% year over year, down from 7.3% growth in the first quarter. For a company of its size and maturity, though, that's solid.
Is Altria a buy?
Some people point to the declining smoking rates as the central hindrance to Altria's long-term success. That's a real problem for the company, no doubt, but I don't think it's as imminent a threat to its business as some may believe. It's true that "just keep raising prices" isn't a great long-term business model, but it does buy Altria time to become a true player in the smokeless nicotine space.
Altria's on! nicotine pouches have been getting good distribution, but they still don't compare to the popularity and success of Philip Morris International's Zyn nicotine pouches. Regardless, any progress is better than none, and after Altria's previous swings and misses in the space, investors should be glad for now.
If you're looking for a solid dividend stock, Altria is a great option. As mentioned, the company isn't oblivious to the fact that most shareholders only stick around for the dividend. If it lets the appeal of that dividend fade, it loses investors, which would present a bigger problem for management.
There are plenty of things Altria would do operationally before putting its dividend on the chopping block. That doesn't make the stock a foolproof investment, but if you're looking for a good income source, Altria provides that. I don't see that changing anytime in the foreseeable future.
Should you buy stock in Altria Group right now?
Before you buy stock in Altria Group, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Altria Group wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 25, 2026.
Stefon Walters has no position in any of the stocks mentioned. The Motley Fool recommends Philip Morris International. The Motley Fool has a disclosure policy.
Recommended Articles


