


1 Red Flag That Keeps Me From Buying AMD Stock
Key Points
About a year and a half of growth is priced into AMD's stock right now.
AMD is far more expensive than its peers.
- 10 stocks we like better than Advanced Micro Devices ›
AMD (NASDAQ: AMD) struggled in the early stages of the AI arms race. Its technology was lacking and behind its competition.
While I won't claim that AMD has caught up on the technological front, its products are far more competitive and serve as viable alternatives to other AI computing units, such as those from Nvidia.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
However, I'm still not planning on buying AMD stock anytime soon. Why? It's just too expensive. The reality is that a ton of growth has already been priced into the stock, and it's just too expensive to consider investing in right now.
Image source: The Motley Fool.
AMD is expensive by practically any valuation measure
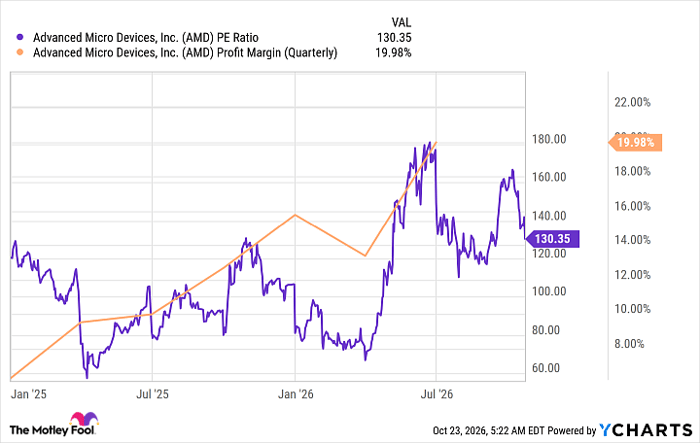
The most common way to value a stock is to use the price-to-earnings (P/E) ratio. This utilizes earnings over the past 12 months to value the stock, and for a big tech company like AMD involved in the AI arms race, you'd probably expect it to be valued between 25 and 35 times earnings. But that's far from the case.
AMD PE Ratio data by YCharts
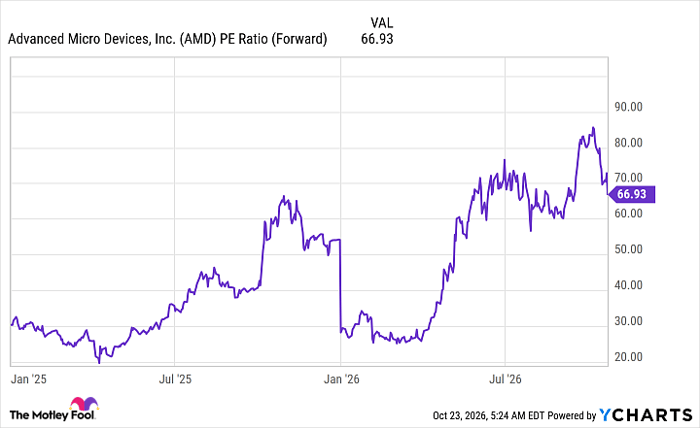
At 130 times earnings, AMD is a very expensive stock. However, one may argue that its profit margins are improving rapidly compared with a few quarters ago. I'll buy this argument, but if I value it based on forward earnings, which should include more optimized quarters, it's still very expensive.
AMD PE Ratio (Forward) data by YCharts
Consider that 67 times forward earnings is a very pricey tag, and it's far higher than AMD has previously been valued.
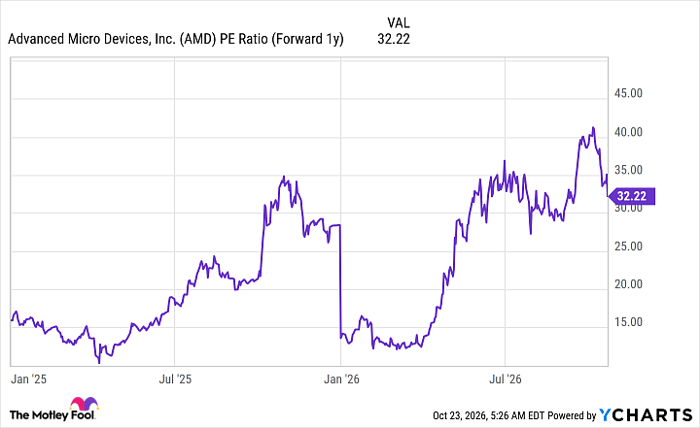
As a final argument, AMD bulls may point to how strong a year AMD expects in 2027. I don't disagree that it will be a great year for AMD as a company, but the reality is that all of 2027's growth is already priced into AMD's stock.
AMD PE Ratio (Forward 1y) data by YCharts
At 32 times next year's earnings, AMD basically has a year and a half of growth priced into its stock right now. So, if AMD hits all analyst expectations and its stock stays flat until next year's results are finalized, AMD will trade at a reasonable 32 times trailing earnings.
That's just too much growth to pay up for right now, especially considering that its primary competitor, Nvidia, trades at 27 times trailing earnings. I think AMD's stock is overextending and way out in front of its skis, and either two things will happen over the next year.
First, it could experience a sizable sell-off. Second, it could underperform as it grows into its valuation. Neither of those two options is attractive, so I'm staying away from AMD stock.
Should you buy stock in Advanced Micro Devices right now?
Before you buy stock in Advanced Micro Devices, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Advanced Micro Devices wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 24, 2026.
Keithen Drury has positions in Nvidia. The Motley Fool has positions in and recommends Advanced Micro Devices and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


