


Is Owning 3,968 Shares of Starbucks Worth It for $10,000 in Yearly Dividend Income?
Key Points
Starbucks is slowly but surely pushing its stock into the upper echelon of dividend payers.
Consistent dividend growth isn’t necessarily an indication that the underlying company is performing well, however.
Interested investors will want to weigh the risk and reward of all their options, including those that aren’t stocks.
- 10 stocks we like better than Starbucks ›
Based on nothing more than the most basic of numbers, Starbucks (NASDAQ: SBUX) is a decent dividend stock. Shares of the chain of coffee shops boast a forward-looking dividend yield of 2.6%, and better still, its quarterly dividend's not only been reliably paid for years, but been raised every year for the past 16 years. And by more than a little. You could certainly do worse.
But could you do better? The $395,000 stake (3,968 shares) you'd need to own in Starbucks just to generate $10,000 in annual dividend income is a lot of money to tie up that could be put to work in ways that make more sense for you, perhaps like the purchase of super-safe 10-year Treasuries, which are currently yielding around 5.1%.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Here's some food for thought.
It's still a stake in a for-profit company
Most blue chip dividend stocks are safe enough in the sense that there's no real risk of a complete wipeout of your money. Starbucks in no exception. Every dividend-paying stock is still also an equity stake in a particular company, however, and participation in that organization's fiscal performance.
That's where Starbucks and its stock have let investors down for the better part of the past five years. While it's technically continued growing its top line, the rate of this growth is markedly slower than its pre-pandemic pace. Profits have also stagnated, not to mention been erratic.
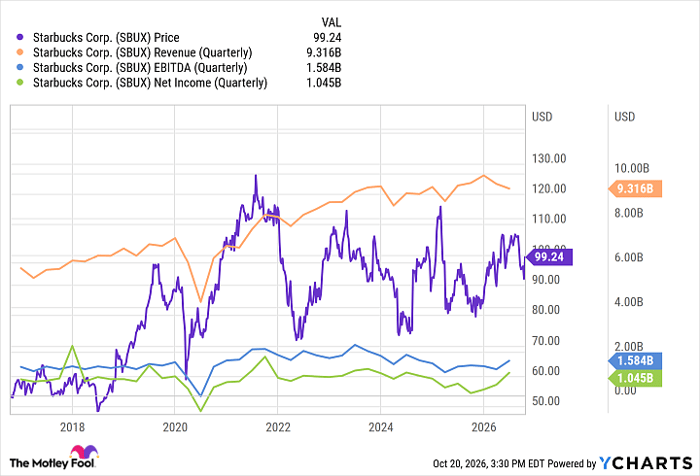
SBUX data by YCharts
Blame a combination of leadership turnover, labor woes, and market saturation, much of which is due to Starbucks' own overwhelming presence. As of the latest count, the company was operating 41,304 stores worldwide, with 16,933 of those units found in the United States alone. That doesn't leave a great deal of room for healthy continued expansion.
This doesn't necessarily make Starbucks a horrible income investment. As was noted, it's not only still paying a respectable dividend, but reliably growing it. We're also seeing glimmers of hope that its profit-crimping struggle since 2024 may finally be coming to a close. Last quarter's overall same-store sales were up 7.9%, capping off four consecutive quarters of such growth.
Image source: Getty Images.
There are still lingering concerns, though, like last quarter's slight 1% decline in revenue. It's going to take several quarters of total top-line progress to confirm that Starbucks is capable of making sustained net growth again. Until then, most interested investors are content to remain on the sidelines.
Better options are out there
In answer to the titular question, then, no, buying nearly $400,000 worth of Starbucks stock (that's far from guaranteed to perform) just to plug into its dividend isn't worth it.
That's even more so the case given all the other, safer options, like Coca-Cola (NYSE: KO). Despite this stock's 36% rally to record highs over the past 12 months, it's currently yielding a comparable 2.3% and has increased its dividend for 64 consecutive years.
Or there's the aforementioned option of longer-term Treasuries, which -- thanks to recent rate hikes -- now sport yields in excess of 5%. Although these instruments don't offer any capital growth potential, with yields twice those of Coca-Cola shares or an uncertain Starbucks, they might still make more near-term sense to income-minded investors.
Should you buy stock in Starbucks right now?
Before you buy stock in Starbucks, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Starbucks wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $361,596!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,303,935!*
Now, it’s worth noting Stock Advisor’s total average return is 910% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 23, 2026.
James Brumley has positions in Coca-Cola. The Motley Fool has positions in and recommends Starbucks. The Motley Fool has a disclosure policy.
Recommended Articles


