


Boeing's $715 Billion Backlog, Explained
Key Points
Boeing's backlog is large and growing, now at $715 billion.
Backlog conversion to revenue will take several years, with some uncertainty.
Operational improvements are underway, but certification and production risks remain.
- 10 stocks we like better than Boeing ›
Boeing's (NYSE: BA) backlog lies at the heart of the stock's investment case. It allows management to unlock significant value for investors. Simply put, the stock has upside potential if management can execute better operationally.
That hasn't always been the case at Boeing in recent years, but there are tangible signs of improvement under CEO Kelly Ortberg, and the company's trajectory is in the right direction.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Boeing.
Boeing's backlog
The overwhelming majority of the backlog is at Boeing Commercial Airplanes (BCA), which represents more than 6,200 aircraft. It's a huge number, and despite increased 737 MAX production in 2026, the backlog rose by $33 billion in the first half of 2026. The BCA backlog accounted for slightly more than $29 billion of that overall increase.
Boeing continues to win orders and grow its backlog. Moreover, Wall Street expects Boeing to generate $97.9 billion in revenue this year.
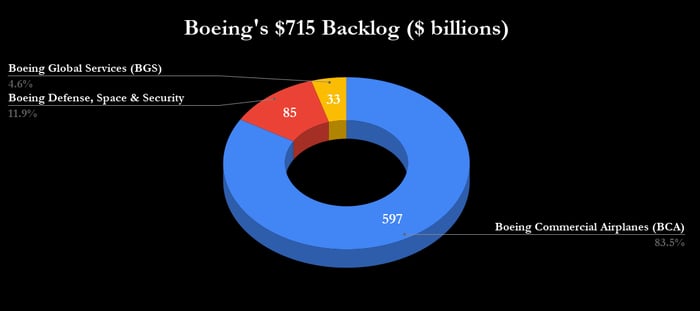
Data source: Boeing presentations. Chart by author.
The backlog is positive and negative
The backlog presents an opportunity for Boeing, but its duration speaks volumes about the company's difficulties in recent years. Its filings at the Securities and Exchange Commission (SEC) said: "We expect approximately 21% to be converted to revenue through 2027 and approximately 62% through 2030, with the remainder thereafter. Significant uncertainty remains about when backlog will convert into revenue."
That's a relatively long duration, meaning that it will take time to convert into earnings and cash flow. It's concerning for two reasons:
- It contains some aircraft that aren't even certified yet, such as the wide-body 777X and the longer 737-10 narrow-body.
- The long duration reflects the bottlenecks and challenges that Boeing has in ramping up aircraft production.
What it means for investors
Boeing's backlog is not without risk, but the fact that 737 MAX production has gone from the low 30s per month at the start of 2025 to a target of stabilizing at 47 per month is a very positive sign. As long as Boeing can keep making progress on this front, investors will have reason to believe it can deliver on its backlog.
Should you buy stock in Boeing right now?
Before you buy stock in Boeing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Boeing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $370,440!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,470,022!*
Now, it’s worth noting Stock Advisor’s total average return is 955% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 8, 2026.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Boeing. The Motley Fool has a disclosure policy.
Recommended Articles


