


My Top Dividend Stock to Buy in October Yields 6% and Cuts Shareholders a Monthly Check
Key Points
Realty Income stock has undergone a considerable sell-off in the last month.
Realty Income’s operations and balance sheet are sensitive to interest rates.
High-yield real estate investment trusts (REITs) aren’t as appealing when 10-year Treasury rates are elevated.
- 10 stocks we like better than Realty Income ›
10-year Treasury rates are at 5.28% at the time of this writing -- the highest level since 2002. In September, the Federal Reserve increased rates for the first time since 2023. And investors are concerned that further interest rate hikes could be on the horizon to curb inflation.
Meanwhile, Realty Income (NYSE: O) is down 11.6% over the last month, pushing its dividend yield to 6% -- its highest level in nearly three years. Here's what's driving the sell-off in Realty Income and other real estate investment trusts (REITs) and why Realty Income stands out as a top dividend stock to buy now.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Getty Images.
Realty Income has a 98.8% occupancy rate
Realty Income operates a portfolio of over 15,500 commercial properties under long-term lease agreements in North America and Europe. It has a 98.8% occupancy rate, meaning existing tenants and properties are relatively insulated from rising rates.
Realty Income's bread and butter is single-unit commercial properties -- especially in the retail industry, which makes up 78.3% of annualized contractual rent. Grocery stores, convenience stores, dollar stores, and drugstores make up a combined 30.6% of annualized contractual rent.
Realty Income partners with customers across multiple properties. Dollar General is the largest client, followed by 7-Eleven, Walgreens, Family Dollar, and Life Time Group (formerly known as Life Time Fitness). But no individual client accounts for more than 3.3% of annual contractual rent.
Rising rates increase borrowing costs, making new deals less attractive as the spread between interest rates and property yields narrows. Higher rates also make it more expensive to refinance older debt -- especially because much of that debt was taken on at rates far lower than today.
Realty Income is down 11.6% in 1 month
Realty Income isn't the only REIT under pressure. Many of its peers have also sold off in lockstep with rapidly rising interest rates.
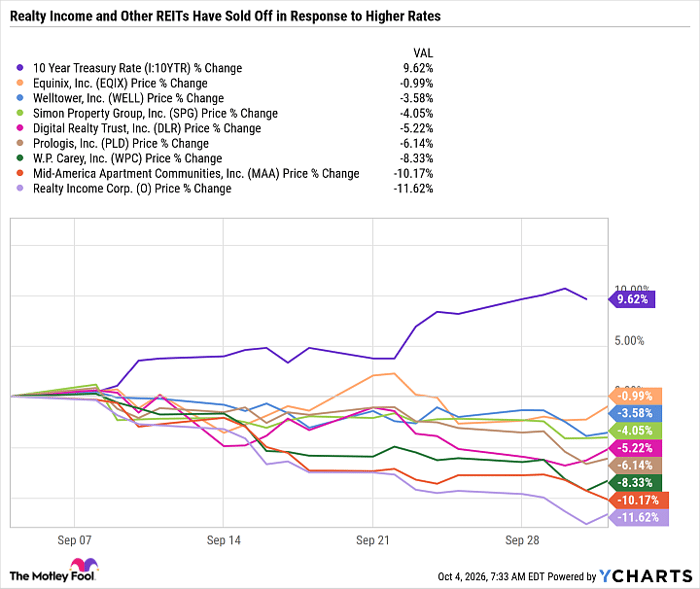
10 Year Treasury Rate data by YCharts
Unlike companies that use excess free cash flow to pay down debt, Realty Income tends to gradually grow its book of business while keeping debt on the balance sheet. The strategy works as its property count and contractual rent grow, but it does make Realty Income more sensitive to rising rates.
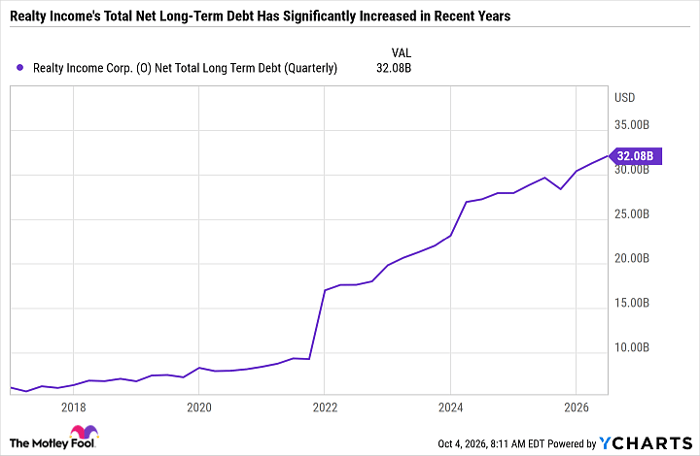
O Net Total Long Term Debt (Quarterly) data by YCharts
Given its heightened exposure to commercial real estate, it makes sense that Realty Income is undergoing a steeper sell-off than REITs with a balanced exposure to industrial and residential customers.
136 dividend increases since 1994
Historically, Realty Income sells off when rates are higher because it's a more challenging operating environment for its business model and because higher Treasury rates are an opportunity cost for dividend stocks. 10-year Treasury notes are typically viewed as risk-free because they are backed by the U.S. government. So 10-year rates at 5.3% compared to Realty Income's 6% yield is a very different setup than if Realty Income were yielding, say, double the risk-free rate.
However, Treasury notes offer a fixed return, whereas the real estate dividend stock offers yield and share price appreciation. It also tends to gradually increase its adjusted funds from operations (AFFO) over time. AFFO measures recurring cash flow that supports dividend payments.
On Sept. 8, Realty Income announced its 136th common stock monthly dividend increase since it was listed on the New York Stock Exchange in 1994. Realty Income pays a monthly dividend, providing a higher-frequency passive-income stream than most stocks that pay quarterly dividends or 10-year Treasury notes, which tend to feature semi-annual interest payments.
To add further security to Realty Income's dividend reliability, the company received an 'A' credit rating from Fitch Ratings in August, making it the fourth U.S. REIT to have at least one 'A' or equivalent rating from either Fitch, Moody's, or S&P Global. The high credit rating is a testament to Realty Income's ability to manage its debt, even though its debt balance has increased substantially in recent years.
A reliable high-yield stock for income investors
Realty Income is a great buy for long-term investors willing to look beyond the present high interest rates. The company has a diversified and high-quality portfolio. Its elite occupancy rate and contract structures create a long runway for steady returns. Realty Income also has an impressive track record of growing its monthly dividend, which is particularly appealing to investors looking to supplement retirement income.
That said, I'd expect the Realty Income sell-off to worsen if interest rates continue rising, so investors should only consider the stock if they're investing with at least a five-year time horizon.
Should you buy stock in Realty Income right now?
Before you buy stock in Realty Income, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Realty Income wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $370,440!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,470,022!*
Now, it’s worth noting Stock Advisor’s total average return is 955% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 8, 2026.
Daniel Foelber has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Dollar General, Equinix, Life Time Group, Mid-America Apartment Communities, Moody's, Prologis, Realty Income, S&P Global, and Simon Property Group. The Motley Fool recommends Digital Realty Trust. The Motley Fool has a disclosure policy.
Recommended Articles


