


Prediction: Micron Stock Will Double Before 2028. Here Are 1.7 Trillion Reasons Why.
Key Points
Demand for high-bandwidth memory (HBM) and high-capacity DRAM from the hyperscalers is fueling Micron's data center and cloud businesses.
Micron's management says memory shortages are expected to last until 2028.
Wall Street analysts are forecasting demand for HBM and DRAM to accelerate over the next couple of years, supporting Micron's growth prospects.
- 10 stocks we like better than Micron Technology ›
Prior to the artificial intelligence (AI) revolution, Micron Technology (NASDAQ: MU) was doing its best to claw back from the usual down cycles of the memory market. Late last year the stock started to move higher, and the momentum carried over into 2026. So far this year, Micron stock has ripped 278%, launching the company into the trillion-dollar club.
What changed is simple: AI data centers started devouring high-bandwidth memory (HBM) and high-capacity DRAM faster than suppliers could produce. The question now is whether Micron's rally still has legs. There are 1.7 trillion reasons to think it does.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »

Image source: Micron Technology.
Micron is converting record sales into record profits
Micron's financial performance in fiscal 2026 was absurd on every level. Full-year revenue hit $133 billion, up 256% from the prior year, while earnings per share (EPS) jumped nearly 900% to $74.
During the fourth quarter alone, the company delivered $54.2 billion in sales and $33 in EPS, with gross margin at 87%. Every segment of the business is going full throttle. The core data center unit generated $18 billion during the fourth quarter at a 90% gross margin. Cloud memory added another $16.3 billion at an 83% margin. Mobile and client, plus automotive and embedded, both cleared 84% margins or better.
The mix shift toward HBM and premium DRAM is the engine fueling Micron right now. Those products carry higher prices and better unit economics, so incremental revenue drops straight to the bottom line. Operating cash flow for the year reached nearly $90 billion and while adjusted free cash flow came in at $62 billion – nearly 20x higher than the year prior. With more than 75% of next year's shipments already under contract or allocation, Micron's cash machine does not look like it is about to stall.
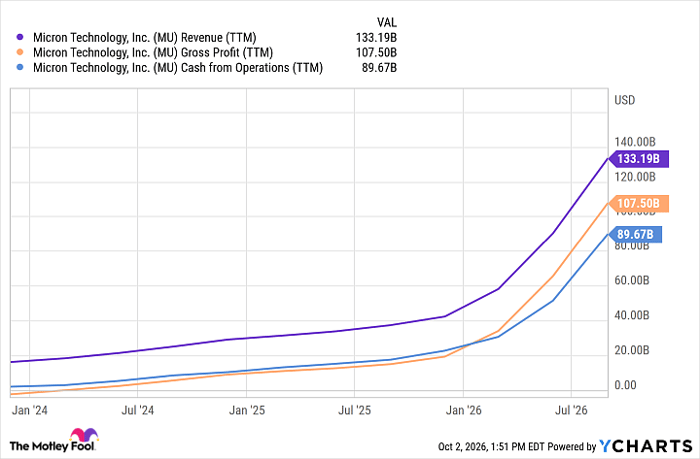
MU Revenue (TTM) data by YCharts
Memory supply could be tight until 2028
Micron's CEO Sanjay Mehrotra suggested memory and storage will be tighter throughout fiscal 2027 and 2028 than they are today. The company's COO, Manish Bhatia, explained the structural brakes around memory, discussing how new technology transitions are delivering diminishing bit growth as HBM nodes take a rising share of industry wafers. Bhatia went on to say Micron simply does not have a clear line to "when supply and demand balances."
Wall Street seems to agree with Micron's management. Citi sees the memory shortfall widening through 2031 as DRAM growth accelerates 30% next year and another 35% in 2028. Meanwhile, JPMorgan's forecast values the memory market at $1.7 trillion by 2028, largely attributable to rising CPU demand alongside memory-intensive GPU systems.
How can Micron stock double?
As of this writing (Oct. 2), Micron stock trades at roughly $1,080 per share. With a forward price-to-earnings (P/E) ratio near 6, this implies the market is modeling somewhere around $176 in earnings for the current fiscal year. Management's guidance for the first quarter points to about $38 in EPS on $61.5 billion of revenue. This implies the earnings run-rate is already there if profit margins hold.
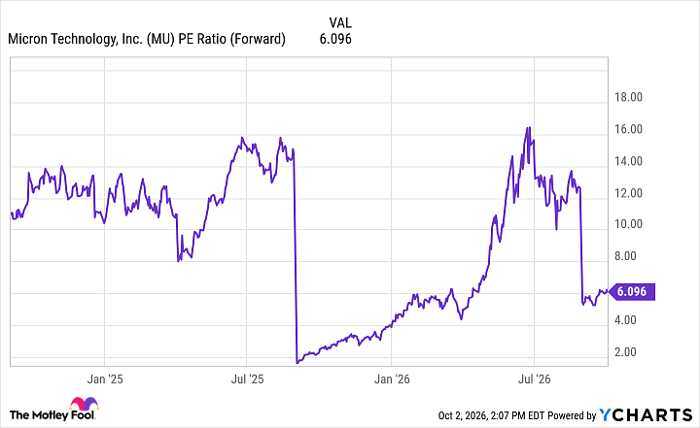
MU PE Ratio (Forward) data by YCharts
Tight supply through 2028 gives Micron room to keep premium prices firm as its product mix continues shifting toward higher-value HBM4 and HBM4E. If earnings simply grow another 20 to 30% on top of the 2027 estimate, you are looking at about $220 in annual EPS by 2028. If I apply even a modest multiple expansion to 10 or 11 times earnings -- still well below historical peaks -- Micron stock could clear $2,000 without needing a massive rerating.
Given today's modest valuation profile multiple, the company's contracted backlog, and the multi-year supply gap, I think Micron stock could reasonably double before 2028 even happens. To me, this level of share price appreciation looks less like wishful thinking and more like a base case scenario so long as the memory shortage simply persists.
Should you buy stock in Micron Technology right now?
Before you buy stock in Micron Technology, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Micron Technology wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $361,650!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,437,517!*
Now, it’s worth noting Stock Advisor’s total average return is 936% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 6, 2026.
Citigroup is an advertising partner of Motley Fool Money. JPMorgan Chase is an advertising partner of Motley Fool Money. Adam Spatacco has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends JPMorgan Chase and Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


