


3 Reasons Why Energy Transfer Is One of My Largest Positions
Key Points
Energy Transfer has some of the best growth prospects in the midstream space.
The company has the cheapest valuation among large-cap pipeline MLPs.
The stock has a secure and growing distribution.
- 10 stocks we like better than Energy Transfer ›
Among individual stocks, Energy Transfer (NYSE: ET) is my largest position. I first bought the stock back in 2019, and my position became significantly larger when the company acquired another of my largest holdings, Crestwood Equity Partners, back in November 2023. Despite the outsize position, I have never sold any shares (technically units) in the master limited partnership (MLP).
Here are three reasons why Energy Transfer remains one of my favorite stocks today.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A midstream empire
In the past, Energy Transfer has gotten a bad rap for focusing more on empire building than on unitholders. However, that empire building has created one of the largest and most powerful midstream companies in the country and one uniquely positioned to benefit from the current AI data center build-out.
In fact, the company would actually be even better positioned today if its general partner hadn't walked away from a $33 billion merger with Williams Companies back in 2016. Williams has become an $87 billion market cap company today and owns one of the most valuable natural gas pipeline systems in the country with Transco. If the deal has closed, Energy Transfer would be the unquestioned leader in natural gas transportation with takeaway capacity from both Appalachia and the Permian.
Nonetheless, the company's strong position in the Permian -- the U.S.'s most prolific oil basin and home to some of the country's cheapest natural gas -- has given it a large backlog of high-return growth projects. The company plans to spend up to $5.9 billion on growth projects this year with long-term locked-in commitments at attractive five- to six-times earnings before interest, taxes, depreciation, and amortization (EBITDA) build rates. That's a very attractive return for a pipeline company, and positions it to be one of the fastest-growing companies among midstream MLPs in the coming years.
Image source: The Motley Fool.
A cheap valuation
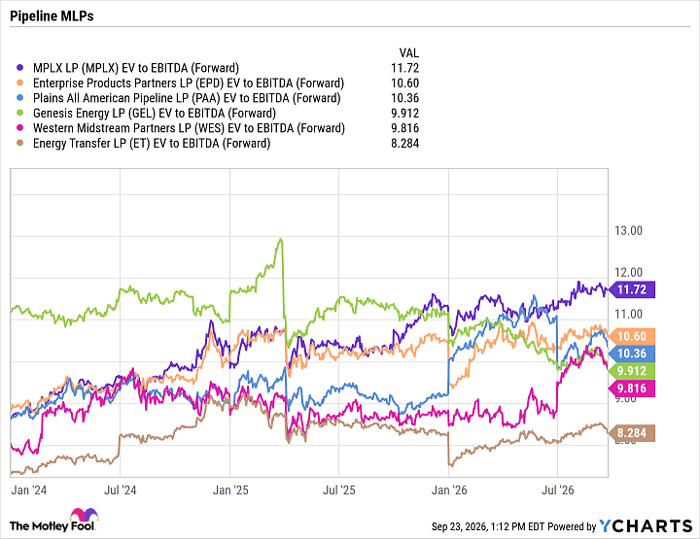
While Energy Transfer has some of the best growth prospects in the midstream space, it also has the cheapest valuation among midstream MLPs. Midstream companies are typically valued based on an enterprise value (EV)-to-EBITDA basis. This is because they carry a fair amount of debt, which gets captured in their enterprise value, while EBITDA captures their current earnings power while stripping away non-cash depreciation costs.
On this basis, Energy Transfer trades at a forward EV-to-EBITDA ratio of 8.3. That's actually the cheapest valuation among pipeline MLPs by far, despite its generally stronger growth outlook.
ET EV to EBITDA (Forward) data by YCharts
Notably, it's also inexpensive on a historical basis. Between 2011 and 2016, midstream MLPs traded at an average EV-to-EBITDA ratio of 13.7, despite having worse balance sheets and often unfavorable incentive distribution rights (IDRs) under the industry's old model.
A safe, attractive, and growing distribution
In addition to its valuation and growth prospects, a third attraction about Energy Transfer is its robust and growing distribution. The stock currently carries a 6.7% yield, while it plans to grow its distribution at a 3% to 5% yearly pace going forward. It has increased its distribution for 19 straight quarters.
Energy Transfer's distribution is well covered by its distribution cash flow (DCF), which is its operating cash flow minus its maintenance capex. Last quarter, its DCF coverage ratio was a robust 2.2. The company has also done a nice job reducing leverage since it got a little over its skis back in 2020. At that time, it cut its payout in half to reduce leverage, which it quickly accomplished, and has since grown its distribution to well above pre-cut levels.
In addition, about 90% of Energy Transfer's EBITDA comes from fee-based businesses that are not impacted by commodity prices or spreads. However, it has frequently been able to take advantage of energy market dislocations to generate bonus cash flow. It also has a high percentage of take-or-pay contracts, which adds to visibility.
Overall, the combination of growth, a high yield, and an attractive valuation makes Energy Transfer one of my favorite stocks to own.
Should you buy stock in Energy Transfer right now?
Before you buy stock in Energy Transfer, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Energy Transfer wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $386,781!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,379,943!*
Now, it’s worth noting Stock Advisor’s total average return is 936% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 25, 2026.
Geoffrey Seiler has positions in Energy Transfer, Enterprise Products Partners, Genesis Energy, and Western Midstream Partners. The Motley Fool recommends Enterprise Products Partners. The Motley Fool has a disclosure policy.
Recommended Articles


