


Gold gains as US Dollar and yields pause, but weekly loss remains in sight
- Gold rebounds modestly from a one-week low as the US Dollar and Treasury yields ease.
- Hawkish Fed expectations remain a key headwind, with markets pricing a stronger chance of an October rate hike.
- Focus shifts to next week’s PCE inflation, ISM Manufacturing PMI and Nonfarm Payrolls data.
Gold (XAU/USD) edges higher on Friday as the US Dollar (USD) and Treasury yields take a breather following their strong rally this week. At the time of writing, XAU/USD trades around $4,310 after slipping to a one-week low of $4,244 on Thursday. Still, the broader fundamental and technical backdrop remains bearish, leaving the precious metal on track for a weekly loss.
Growing expectations that the Federal Reserve (Fed) may raise interest rates again remain a key headwind for Gold. The central bank delivered a 25-basis-point (bps) rate hike last week, lifting the federal funds rate to 3.75%-4.00%, while its updated projections showed that 16 of 18 policymakers expect at least one more increase this year.
Bets on another rate increase as early as next month gained traction throughout the week after strong US Purchasing Managers’ Index (PMI) data and hawkish comments from Fed officials. New York Fed President John Williams said, “We need to get inflation back to target in a timely manner,” adding that it is “reasonable to see another rate hike by end of the year.” Richmond Fed President Tom Barkin said inflation pressures are spreading beyond energy and tariff-related shocks.
The CME FedWatch Tool now shows around a 71% probability of a hike at the October meeting. The repricing has driven a sharp rise in the US Dollar and Treasury yields across the curve. A stronger US Dollar makes Gold more expensive for foreign buyers, while higher yields increase the opportunity cost of holding the non-yielding metal.
As of writing, the US Dollar Index (DXY), which tracks the Greenback’s value against a basket of six major currencies, trades around 101 after reaching 101.40 on Thursday, its highest level in nearly two months. Meanwhile, the benchmark 10-year US Treasury yield holds near 5.17%, below Thursday’s peak of 5.22%, its highest level since 2007.
Meanwhile, higher Oil prices caused by the war in the Middle East are adding to inflation pressures, complicating the Fed’s efforts to bring inflation down to the 2% target. Iran has offered to reopen the Strait of Hormuz within seven days if Washington eases military pressure and lifts its blockade. US and Iranian officials are also discussing a phased deal, but the two sides remain far apart and have not reached a breakthrough, Reuters reported.
On the data front, traders await the final University of Michigan Consumer Sentiment Index for September later on Friday. The US economic calendar becomes much heavier next week. Personal Consumption Expenditures (PCE) inflation data is due on Wednesday, followed by the ISM Manufacturing PMI on Thursday and the Nonfarm Payrolls (NFP) report on Friday. These releases could play a major role in shaping expectations for the Fed’s October meeting.
Technical Analysis: XAU/USD hovers above the Bollinger middle band
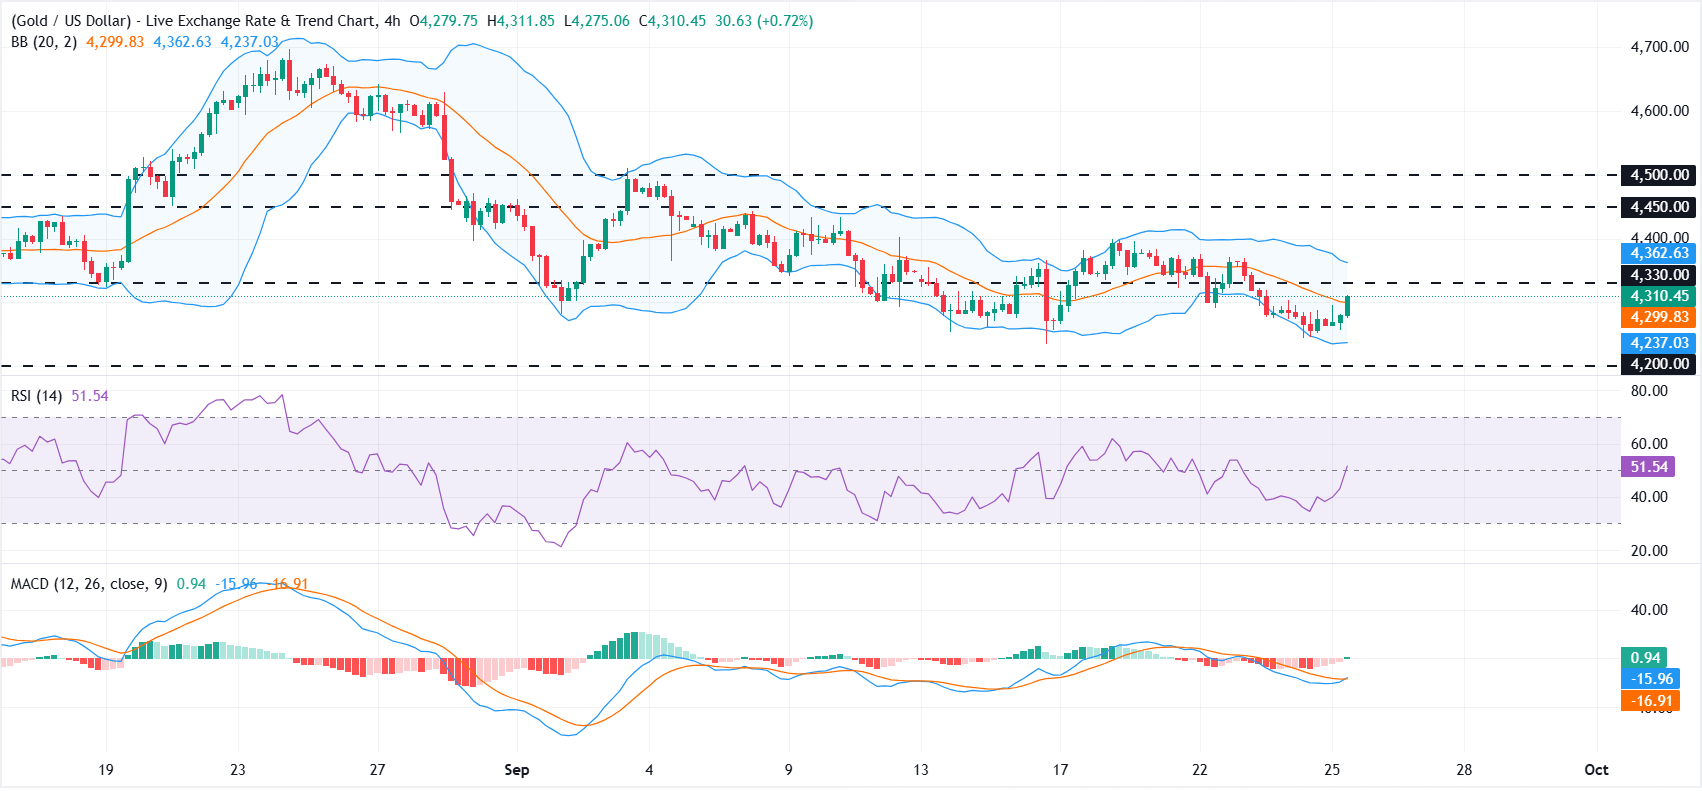
On the 4-hour chart, XAU/USD maintains a constructive near-term tone as it holds above the 20-period Simple Moving Average (SMA) at $4,299 from the Bollinger Bands and the lower band support near $4,237. The pair is pushing into the upper half of the recent volatility envelope, while the Relative Strength Index (RSI) around 51 hints at neutral-to-firm momentum and the Moving Average Convergence Divergence (MACD) turning slightly positive reinforces a mild bullish bias.
On the topside, immediate resistance is seen at the horizontal barrier around $4,330, followed by the Bollinger upper band near $4,362. A sustained break above this area could expose the next resistance zone between $4,450 and $4,500. On the downside, initial support is provided by the Bollinger middle band at $4,299, followed by the lower band near $4,237. A deeper pullback could bring the $4,150-$4,200 support zone into focus.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Recommended Articles


