


BP PLC Stock (BP) Moved Up by 3.50% on Oct 8: What Investors Need To Know
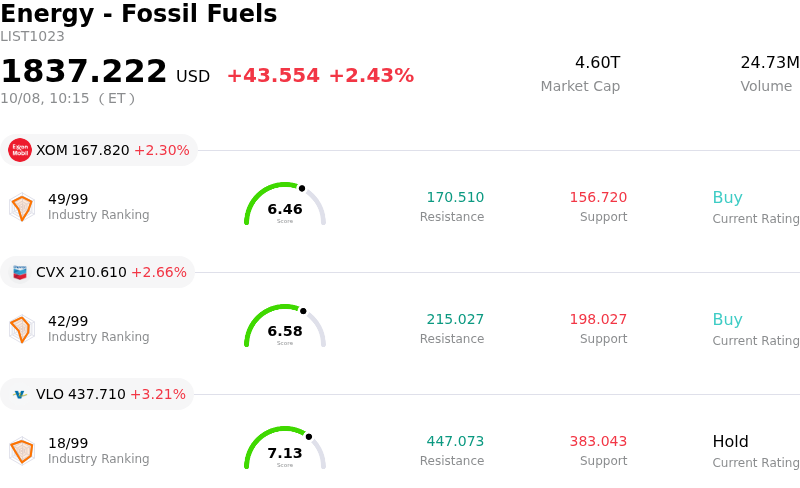
BP PLC (BP) moved up by 3.50%. The Energy - Fossil Fuels sector is up by 2.43%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Exxon Mobil Corp (XOM) up 2.25%; Chevron Corp (CVX) up 2.64%; Valero Energy Corp (VLO) up 3.14%.
What is driving BP PLC (BP)’s stock price up today?
The upward momentum in BP's equity valuation is primarily driven by a sharp rally in global crude oil benchmarks, as escalating Middle East geopolitical tensions and shipping vulnerabilities through the Strait of Hormuz continue to inject a substantial risk premium into energy markets. Additional supply concerns stemming from weather-related production curtailments in the Gulf of Mexico have further reinforced crude prices above key psychological thresholds. As an integrated global energy leader with substantial upstream operational scale, BP stands as a direct beneficiary of higher realized selling prices, which significantly enhance cash flow expectations across its core production portfolio.
Beyond macroeconomic tailwinds, firm-specific operational dynamics and favorable institutional sentiment have provided strong support for the equity. Ahead of the company's upcoming quarterly financial reporting, Wall Street consensus has trended higher, reflecting growing confidence in management's strategic refocus on high-return hydrocarbon assets and corporate deleveraging. Multi-broker upgrades point to robust cash generation that is accelerating net debt reduction toward long-term targets faster than initially anticipated. Furthermore, structural portfolio optimization, including planned proceeds from non-core divestments such as the Castrol transaction, is strengthening the balance sheet and improving operational efficiency under new leadership.
From a market structure perspective, BP remains attractive to value-oriented institutional capital due to its compelling valuation discount relative to major U.S. integrated peers. Strong refining margins and solid performance across its global trading arm provide defensive cash flow buffers against broader market volatility. While persistent geopolitical uncertainty and input cost pressure represent ongoing operational considerations, the combination of strong commodity tailwinds, disciplined capital allocation, and a sustainable dividend framework underpins solid investor demand.
Technical Analysis of BP PLC (BP)
Technically, BP PLC (BP) shows a MACD (12,26,9) value of 0.110, indicating a buy signal. The RSI at 60.439 suggests neutral condition and the Williams %R at 7.179 suggests overbought condition. Please monitor closely.
Fundamental Analysis of BP PLC (BP)
BP PLC (BP) is in the Energy - Fossil Fuels industry. Its latest annual revenue is $189.34B, ranking 3 in the industry. The net profit is $54.00M, ranking 63 in the industry. Company Profile
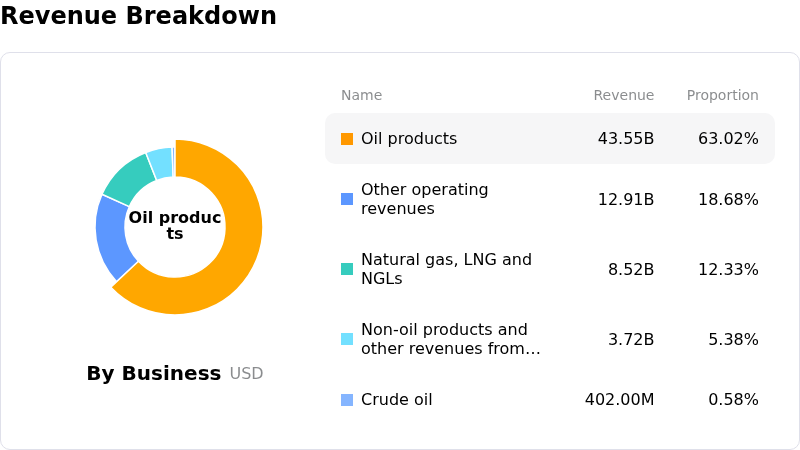
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $50.52, a high of $64.00, and a low of $41.00.
More details about BP PLC (BP)
Company Specific Risks:
- Persistent High Debt Load and Deferred Buyback Resumption: BP continues to struggle with elevated net debt of over $22 billion, forcing executive leadership to suspend share repurchases while refusing to provide a clear timeline for resumption, creating ongoing friction with institutional investors seeking immediate capital returns.
- Sequential Refining Volume Declines and Tax Headwinds: Q3 guidance reflects lower downstream refinery throughput projected between 1,300 and 1,360 thousand barrels per day alongside an increased effective corporate tax rate of 35% to 40%, following operational hits from reduced upstream plant reliability and over $1 billion in net impairment charges.
- Execution Reliance on Heavy Asset Divestments: The company's balance sheet reset and long-term net debt reduction targets depend heavily on completing $8 billion to $9 billion in non-core asset sales—including the $6 billion Castrol transaction—leaving financial guidance vulnerable to transaction delays or valuation haircuts.
- Governance Uncertainty and Leadership Turnover: Structural instability and C-suite friction, highlighted by executive board turnover and the abrupt ousting of Chairman Albert Manifold over governance and conduct issues, fuel institutional concern regarding corporate oversight and long-term strategy execution.
Recommended Articles


