

Wheaton Precious Metals Corp Stock (WPM) Closed Down by 5.11% on Sep 28: What Investors Need To Know

Source Tradingkey

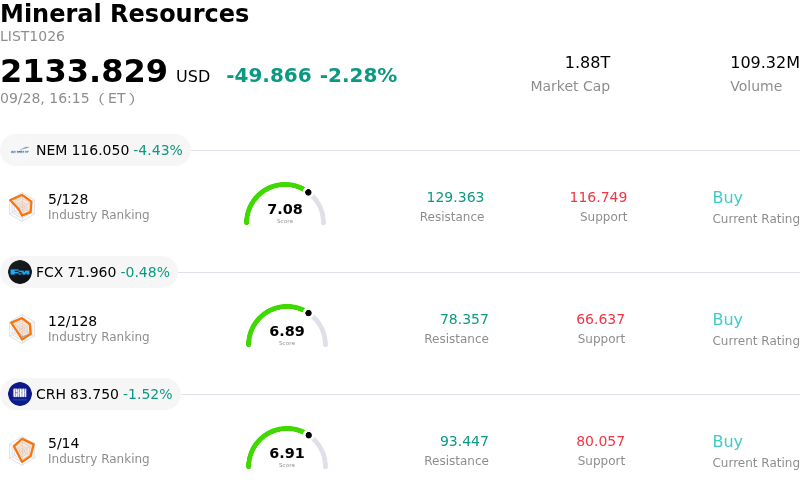
Wheaton Precious Metals Corp (WPM) closed down by 5.11%. The Mineral Resources sector is down by 2.28%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Newmont Corporation (NEM) down 4.43%; Freeport-McMoRan Inc (FCX) down 0.48%; CRH PLC (CRH) down 1.52%.
SummaryOverview

What is driving Wheaton Precious Metals Corp (WPM)’s stock price down today?

Wheaton Precious Metals experienced significant downside pressure driven primarily by a sharp retreat in underlying precious metal spot prices. A surging U.S. dollar index alongside elevated Treasury yields has dampened demand for non-yielding assets, causing gold and silver bullion prices to slide simultaneously. Because Wheaton operates as a streaming company whose revenues and cash flows depend heavily on fixed-price purchase agreements for physical gold, silver, and other metals, sustained softness in spot commodity benchmarks directly impairs the company's immediate top-line projections.

Market sentiment across the precious metals space has been further weighed down by hawkish central bank commentary and persistent inflation concerns, which have heightened expectations of prolonged tight monetary policy. In addition, end-of-quarter portfolio rebalancing by institutional fund managers has accelerated capital outflows from commodity-linked equities toward higher-yielding debt instruments and alternative risk assets. As institutional investors trimmed allocations to inflation-hedge equities, precious metal streamers faced broader sector-wide selling pressure regardless of individual operational execution.

From a fundamental standpoint, while Wheaton maintains an asset-light model with attractive long-term production growth and margin protection relative to traditional miners, recent upfront capital commitments for streaming agreements have heightened short-term market sensitivity to cash flow variability. Investors remain cautious as lower realization prices temporarily compress near-term margins and free cash flow generation. Nevertheless, the company's structural advantage of capped operating costs positions it to weather commodity volatility, though near-term share price performance will remain closely tethered to shifts in macroeconomic monetary policy and spot metal price stability.

Technical Analysis of Wheaton Precious Metals Corp (WPM)

Technically, Wheaton Precious Metals Corp (WPM) shows a MACD (12,26,9) value of -5.156, indicating a neutral signal. The RSI at 39.910 suggests neutral condition and the Williams %R at 94.629 suggests oversold condition. Please monitor closely.

Fundamental Analysis of Wheaton Precious Metals Corp (WPM)

Wheaton Precious Metals Corp (WPM) is in the Mineral Resources industry. Its latest annual revenue is $2.31B, ranking 39 in the industry. The net profit is $1.47B, ranking 15 in the industry. Company Profile

Over the past month, multiple analysts have rated the company as Buy, with an average price target of $175.67, a high of $250.00, and a low of $149.87.

More details about Wheaton Precious Metals Corp (WPM)

Company Specific Risks:

  • Near-Term Earnings Estimate Revisions: Equity research analysts at Zacks Research recently lowered Q3 earnings per share estimates for WPM from $1.05 to $1.00, triggering institutional re-evaluations and placing downside pressure on near-term valuation multiples.
  • Commodity Price Sensitivity and Spot Silver Pullback: WPM’s top-line revenue is directly linked to underlying precious metals spot prices, leaving contract margins exposed to broader commodity pullbacks and volatility in spot silver and gold trading.
  • Counterparty and Operational Execution Exposure: As a streaming company, Wheaton does not control mine operations and remains exposed to production delays, geopolitical headwinds, and technical disruptions across third-party partner sites such as the Antamina project.
  • Capital Allocation and Upfront Stream Funding Pressures: Securing new long-term metal streaming agreements requires substantial upfront cash investments, creating balance sheet deployment risks and potential liquidity strain during volatile market conditions.
Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
October hike odds climb toward 60% as Goldman and BofA both flip — what Warsh's "dose of accommodation" really changedRate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
Author  Irene Q.
Sep 23, Wed
Rate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
placeholder
Four jobs reports in five days: what JOLTS, ADP, claims and the September payrolls mean for the October Fed decisionThe US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
Author  Mitrade
Sep 28, Mon
The US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
placeholder
RBA set to hike interest rate to 4.60% in September as inflation remains elevatedThe Reserve Bank of Australia (RBA) is widely expected to raise the Official Cash Rate (OCR) by 25 basis points (bps) to 4.60% from 4.35% on Tuesday, after keeping rates unchanged at its previous two meetings
Author  FXStreet
Yesterday 01: 40
The Reserve Bank of Australia (RBA) is widely expected to raise the Official Cash Rate (OCR) by 25 basis points (bps) to 4.60% from 4.35% on Tuesday, after keeping rates unchanged at its previous two meetings
placeholder
Nvidia's $150 billion buyback landed — and the AI sector fell anyway. That's the signal worth tradingNvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
Author  Irene Q.
Yesterday 06: 31
Nvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
placeholder
The 30-year Treasury just hit a 22-year high — and the bond market is not pricing the Fed, it is pricing the deficitThe 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
Author  Irene Q.
Yesterday 07: 08
The 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
goTop
quote