


US August Nonfarm Payrolls Preview: Will the Labor Market Quell Fed Rate Hike Expectations? US Stocks, Dollar, and Gold Face Key Test
TradingKey - The U.S. Bureau of Labor Statistics will release the August nonfarm payrolls report at 8:30 a.m. ET on September 4. Following hawkish signals delivered by Fed Chair Warsh at Jackson Hole and rising international oil prices reigniting inflation concerns, this jobs report will be one of the most critical macro data points ahead of the September FOMC meeting.
August Nonfarm Payrolls Expected to Resume Growth, but US Labor Market Remains in Slow Expansion
The U.S. labor market has cooled noticeably of late. Nonfarm payrolls unexpectedly fell by 23,000 in July, while the unemployment rate remained at 4.1%. Meanwhile, nonfarm payrolls for May and June were revised down by a combined 103,000, showing that the labor market's actual performance was weaker than initially reported. Average hourly earnings rose 3.2% year-over-year in July, while the labor force participation rate held steady at 61.4%.
For the upcoming August report, a recent Reuters survey expects nonfarm payrolls to increase by about 56,000, compared with around 58,000 in a survey conducted a week earlier, with the unemployment rate expected to remain at 4.1%. The data shows that even if August nonfarm payrolls meet expectations, the U.S. labor market is still making only a mild recovery from July's contraction. Compared with job growth in recent years, which routinely added over 100,000 or even hundreds of thousands of jobs, current job creation has slowed noticeably.
The newly released ADP data further reinforces this assessment. U.S. private sector employment increased by just 38,000 in August, below market expectations of 48,000 and lower than July's revised 46,000, marking the slowest pace of growth since January this year. Among these, education and health services added 45,000 jobs, but manufacturing lost 17,000, and professional and business services declined by 16,000, showing that corporate hiring intent remains cautious.
Notably, Warsh stressed at the Jackson Hole conference that if the Federal Reserve cannot be confident that underlying inflation is returning to 2% quickly enough, policymakers still need to take further action. Following the speech, the market significantly raised expectations for a September rate hike. As of this week, interest rate markets still price in roughly a 60% probability of a 25-basis-point rate hike in September.
Meanwhile, the U.S.-Iran conflict has driven international crude oil prices up again, and long-term U.S. Treasury yields had previously climbed rapidly. Therefore, whether August nonfarm payrolls can prove that the labor market retains sufficient resilience will directly impact whether the Federal Reserve has room to hike interest rates further in September.
If August nonfarm payrolls come in significantly higher than expected—for example, with job creation exceeding 100,000 while the unemployment rate remains at 4.1% or even declines—it would imply that July's employment drop was likely more of a short-term fluctuation. Labor market resilience combined with high inflation would further increase the likelihood of a September rate hike.
If job creation comes in near the market expectation of roughly 50,000 to 60,000, it would indicate that the labor market is still expanding, but at a very mild pace. Such a result may not be enough on its own to determine the direction of September policy, and the Fed would still need to evaluate it alongside the subsequent release of August PPI and CPI data.
If nonfarm payrolls again approach zero growth or continue to decline, while the unemployment rate rises to 4.2% or higher, it would mean the labor market is cooling faster than the Fed expected. Even if inflation remains high, the threshold for the Fed to continue hiking rates would increase significantly.
How Non-Farm Payroll Data Affects US Stocks, the Dollar, and Gold?
For U.S. stocks, the S&P 500 Index is currently still up over 12% year-to-date, with corporate earnings and AI capital expenditures continuing to provide support for tech stocks, though U.S. Treasury yields and Federal Reserve rate hike expectations are suppressing valuations. If nonfarm payrolls are significantly higher than expected, the market may further bet on a September rate hike, and rising Treasury yields will put pressure on high-valuation tech stocks, making the Nasdaq Index potentially more sensitive than the Dow. Conversely, if job growth is slightly below expectations without showing clear recession signals, declining rate hike expectations could drive yields lower, which would instead be relatively positive for growth and tech stocks. What truly requires caution is a sharp negative turn in nonfarm payrolls accompanied by a rising unemployment rate; in that case, the market may worry about an economic recession and corporate earnings, putting U.S. stocks under pressure.
For the U.S. dollar, the impact of nonfarm payrolls on short-term trends is relatively direct. Stronger-than-expected employment data means the Federal Reserve has more room to continue controlling inflation, and expectations for a September rate hike may warm up further, offering support to the U.S. Dollar Index. If job growth falls significantly below 50,000 or even turns negative again, the market may scale back its current roughly 60% rate hike bets, and declining short-term Treasury yields will put pressure on the dollar.
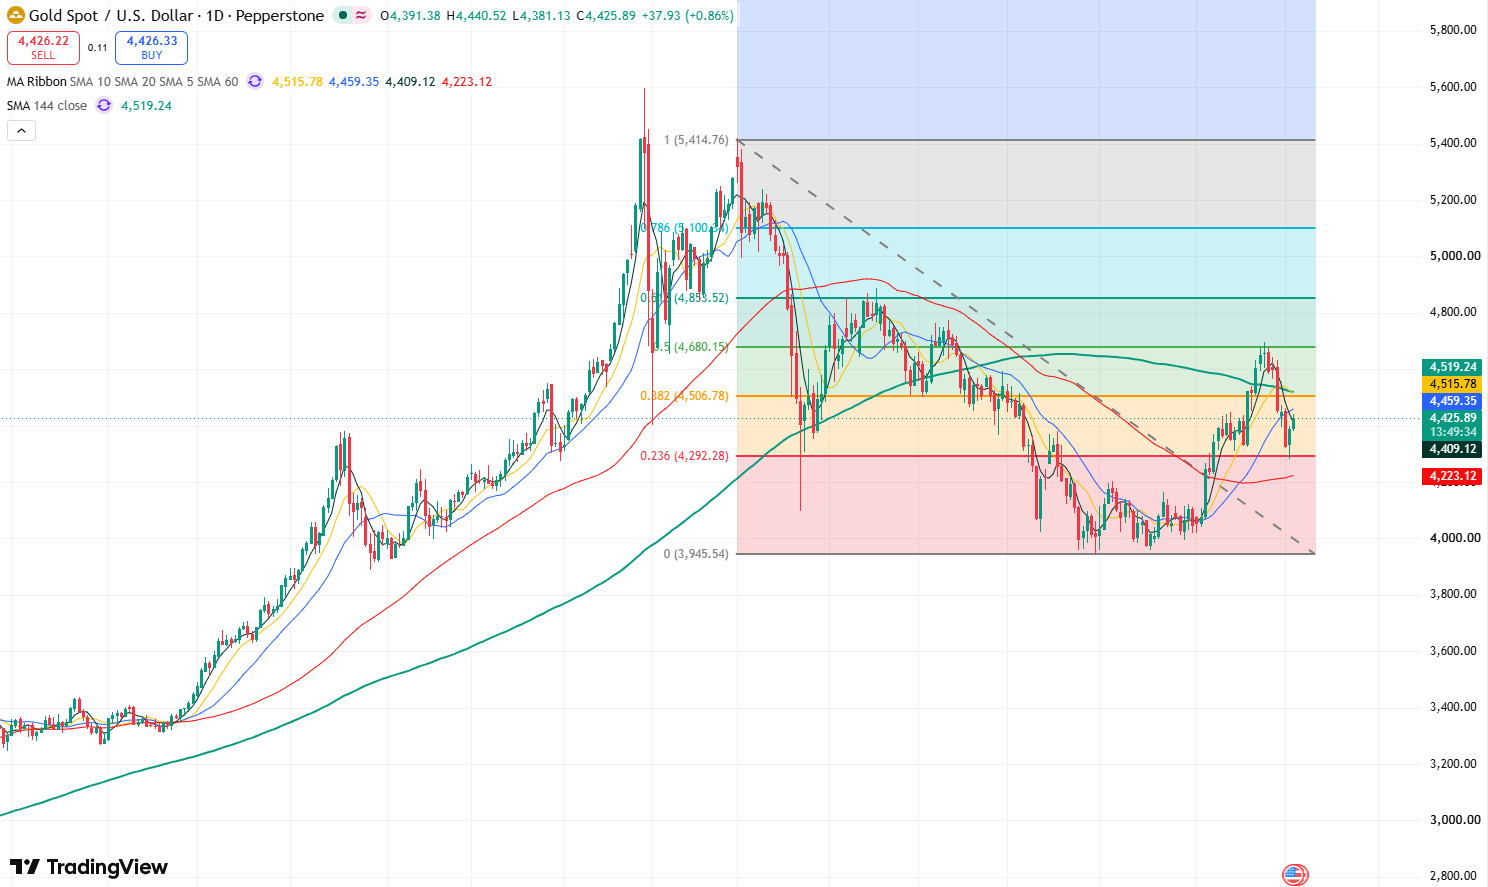
Gold price daily chart, Source: TradingView
For gold (XAUUSD), the key factor for nonfarm payrolls remains its impact on Federal Reserve rate hike expectations and Treasury yields. As of September 3, spot gold returned to around $4,420, mainly driven by a pullback in the U.S. dollar and Treasury yields; meanwhile, the market still expects the probability of a September rate hike to exceed 60%. If nonfarm payrolls are significantly stronger than expected, especially if job growth exceeds 100,000 accompanied by accelerated wage growth, Treasury yields and the dollar may rise again, leaving gold facing selling pressure once more to test the support level at $4,290 on the downside. Conversely, if job growth is significantly below expectations and the market scales back September rate hike bets, gold may benefit from declining yields and rebound further, with the potential to test $4,700 on the upside.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


