


Prediction: A $1,000 Investment in TSMC Stock Will More Than Double by 2030. Here’s Why You Should Buy It Before Oct. 15.
Key Points
TSMC's accelerating revenue growth indicates that its guidance could exceed expectations.
The company's price hikes and increasing production capacity point to a stronger 2027.
The secular growth of the semiconductor market and TSMC's dominant position in the foundry market should translate into healthy earnings growth for the company.
TSMC stock could more than double by the end of the decade, suggesting it isn't too late to buy.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Taiwan Semiconductor Manufacturing (NYSE:TSM), popularly known as TSMC, has been one of the biggest beneficiaries of the global chip boom, primarily due to its position as the largest semiconductor foundry that manufactures chips for major consumer electronics companies and chip designers that serve multiple end markets.
TSMC has capitalized on the artificial intelligence (AI) boom in recent years, thanks mainly to its advanced process nodes, which enable customers to manufacture cutting-edge chips. Not surprisingly, TSMC stock has gained nearly 384% over the past three years, outperforming the 246% gain in the PHLX Semiconductor Sector index over the same period.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
I won't be surprised to see this semiconductor stock head higher after it releases its third-quarter results on Oct. 15. Let's look at the reasons why TSMC is primed for more upside, potentially doubling by 2030.

Image source: The Motley Fool.
TSMC's accelerating growth suggests that its bull run is far from over
This has been a strong year for TSMC. The company's revenue has increased by 41% in the first nine months of 2026, suggesting it is on track to exceed its 2025 revenue growth of 36%.
Notably, TSMC's revenue growth has accelerated in recent months. Its September revenue increased nearly 55% from the same month in 2025, while August 2026 revenue was up by 53% over the same month last year. TSMC's Q3 revenue increased by 50% from the same period last year to $46.71 billion, beating estimates and exceeding the company's guidance range of $44.6 billion to $45.8 billion.
What's more, the company's net profit is expected to increase by 64% from the year-ago period, as noted by Reuters. In fact, Reuters points out that TSMC is on track to report its sixth consecutive quarter of record profits due to the huge investments in AI infrastructure. The good part is that the AI infrastructure boom is far from over.
Nvidia, for instance, expects to double its chip sales next year. On the other hand, Advanced Micro Devices expects it can substantially boost supply in 2027, as it sees strong demand for advanced chips driven by AI. Both Nvidia and AMD are TSMC's customers.
As a result, it is easy to see why TSMC is reportedly planning to increase the production capacity of its advanced chip nodes next year. Market research firm TrendForce reports that TSMC's 2-nanometer (nm) chip production capacity could jump 22% by mid-2027 compared to the end of 2026. Additionally, the semiconductor giant is reportedly planning a 16% increase in 3nm production capacity over the same period.
TSMC gets a third of its revenue from these two process nodes, so higher production bodes well for the company's performance next year. Also, TSMC is reportedly set to increase prices for its advanced nodes by 5%-10% next year, according to Taiwan's national news agency.
So, TSMC should ideally witness a strong increase in both volumes and margins in 2027, which should allow it to sustain its robust revenue and earnings growth. Moreover, I won't be surprised to see TSMC offer a stronger-than-expected outlook when it reports results on Oct. 15, as AI customers such as Nvidia and AMD build up inventory to meet strong end-market demand.
TSMC's sunny guidance could pave the way for more upside. Moreover, TSMC increased its global semiconductor revenue forecast for 2030 to $1.5 trillion in May this year, up from the earlier estimate of $1 trillion. So, the strong jump in TSMC's revenue and earnings is sustainable beyond 2027, and that's what analysts are expecting.
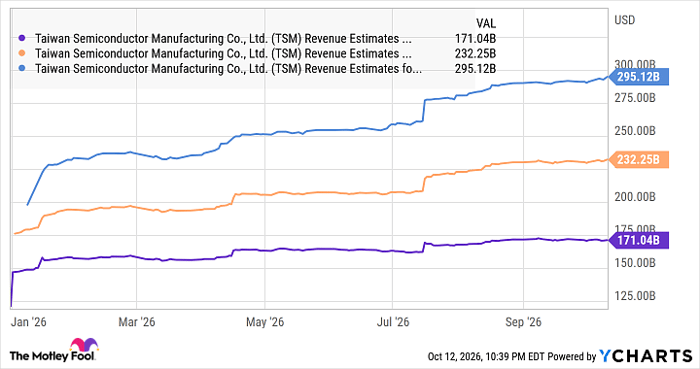
TSM Revenue Estimates for Current Fiscal Year data by YCharts
A $1,000 investment in TSMC stock is going to be a smart move
If you have $1,000 in investible cash after meeting your expenses, saving for tough times, and clearing expensive loans, you can consider buying this AI stock with that money. The reason why I say this is that analysts have become quite bullish about TSMC's earnings growth prospects this year.
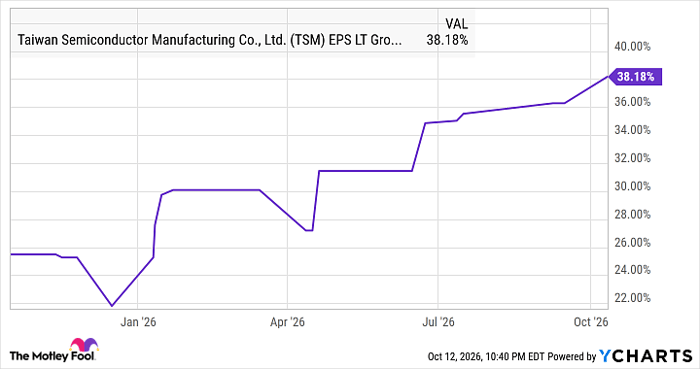
TSM EPS LT Growth Estimates data by YCharts
Specifically, TSMC's earnings are anticipated to increase by 60% in 2026 to $17.04 per share. The forecast for the next couple of years points to solid 30% increases.
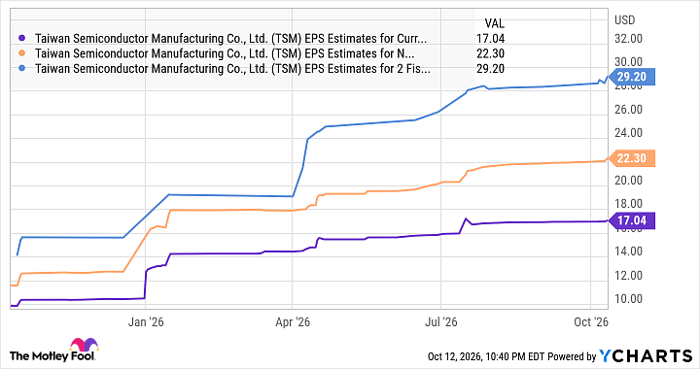
TSM EPS Estimates for Current Fiscal Year data by YCharts
Assuming TSMC's bottom line increases by even 20% in 2029 and 2030, its earnings per share could hit $42.05 by the end of the decade. If TSMC trades at 30 times earnings at that time, a slight discount to the Nasdaq-100 index's earnings multiple of 31.5, its stock price could reach $1,261. That's 184% higher than where TSMC stock is right now.
So, a $1,000 investment in TSMC could be worth more than $2,800 in 2030, which is why investors should consider buying this multibagger stock before it soars higher following its Oct. 15 report.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $379,123!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,408,822!*
Now, it’s worth noting Stock Advisor’s total average return is 950% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 13, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Advanced Micro Devices, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


