


1 AI Stock Poised to Outperform Micron and Sandisk on the Next Infrastructure Surge
Key Points
TSMC's growth rate has been improving due to the healthy demand for AI accelerators.
The company could outperform analysts' expectations and surge significantly over the next three years.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Artificial intelligence (AI) infrastructure spending isn't slowing down, and that's not surprising, as major hyperscalers and AI companies need to fulfill massive contractual backlogs.
Oracle, for instance, recently reported a contractual backlog of a whopping $664 billion. Meanwhile, Alphabet notes that its Google Cloud backlog hit a whopping $514 billion in the second quarter. These massive numbers explain why market research firm Dell'Oro Group projects AI infrastructure spending to exceed $3 trillion by 2030. For comparison, Goldman Sachs expects over $1 trillion in AI investments this year.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Dell'Oro Group's latest estimate is almost double the forecast it issued in January this year. This is great news for Micron Technology and Sandisk, two companies that have benefited significantly from heavy AI data center spending. Micron and Sandisk manufacture compute and storage memory that's solving a critical bottleneck in AI data centers by quickly transporting huge data sets to accelerator chips.
Not surprisingly, both semiconductor stocks have surged impressively over the past year. However, investors have been rotating out of memory stocks lately. Concerns about a potential oversupply in the memory market and the already impressive margins of Micron and Sandisk are the reasons why investors seem to be losing confidence in memory stocks.
That's why it is a good time to take a closer look at Taiwan Semiconductor Manufacturing (NYSE: TSM), another critical cog in the AI infrastructure ecosystem. Let's see why this foundry giant could outperform Micron and Sandisk as AI infrastructure spending accelerates.
Image source: Getty Images.
AI accelerator demand will give TSMC's growth a nice shot in the arm
TSMC is a pure-play foundry company that manufactures chips for other companies. Its customers include Nvidia, Advanced Micro Devices, Qualcomm, Sony, Apple, and many others. TSMC serves multiple industries, including data centers, smartphones, personal computers, and automotive.
AI is currently TSMC's biggest catalyst. The company noted in April that it expects its AI accelerator revenue to increase at a high 50% compound annual growth rate (CAGR) through 2029. However, management noted on the July earnings call that it expects AI accelerator revenue to grow faster than previously estimated. Though TSMC didn't provide a specific number, it seems its AI revenue CAGR could accelerate into the 60%+ range.
A closer look at the company's August revenue growth tells us just why that's likely to be the case. TSMC posted a 53% year-over-year increase in revenue last month. This was well above the 39% revenue growth the company has clocked in the first eight months of 2026. Nvidia CEO Jensen Huang estimates that AI infrastructure spending could hit a range of $3 trillion to $4 trillion by 2030. That's well above the $800 billion capex that TSMC customer Nvidia expects from the top five hyperscalers in 2026.
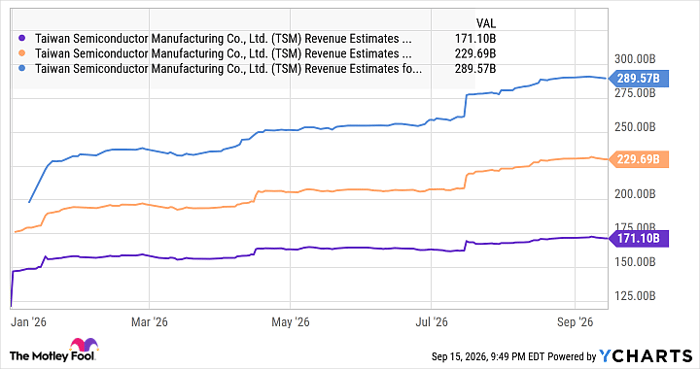
So, TSMC's AI accelerator revenue is likely to increase at a robust pace in the long run, lifting the company's overall growth rate in the process. Analysts have gradually become bullish on TSMC's revenue growth rate over the next three years.
Data by YCharts
The company's top line could increase by 43% this year, according to consensus estimates on Yahoo! Finance. The chart above makes it clear that the forecast for 2027 and 2028 points to robust double-digit growth, though I won't be surprised to see TSMC exceeding expectations owing to the robust AI infrastructure spending environment.
Moreover, TSMC stands to capitalize on the growth in other niches. For instance, the company can benefit from a rebound in the global smartphone market starting in 2028, when shipments could increase by 5%. Counterpoint Research estimates that smartphone shipments could drop 14% in 2026 and 1% next year due to high component costs. The pick-up in smartphone sales in 2028 would enhance TSMC's growth opportunity, considering that it counts the likes of Apple, Qualcomm, and MediaTek as customers.
Also, TSMC controls 72.5% of the global foundry market, according to market research firm TrendForce. This gives the company impressive pricing power, which is why it is anticipated to increase prices by up to 10% from 2027. This bodes well for TSMC's bottom line.
The stock is poised to skyrocket
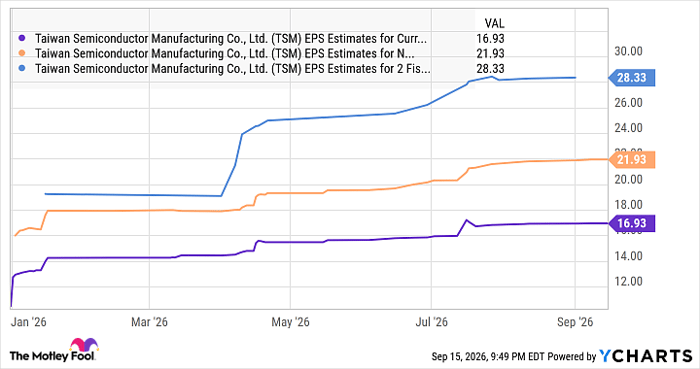
TSMC stock has appreciated 36% in 2026, underperforming Sandisk and Micron by a huge margin. However, that could change owing to the company's impressive earnings growth potential. Analysts expect a 59% spike in TSMC's earnings in 2026. However, its growth rate is anticipated to drop over the next couple of years.
Data by YCharts
Don't be surprised to see TSMC outpacing analysts' expectations, fueled by the rapid growth of the AI accelerator market and its expansive client base. Given that TSMC trades at just 20 times forward earnings, a discount to the tech-focused Nasdaq-100 index's forward earnings multiple of 24.5, its stock could jump significantly as its growth accelerates.
Assuming TSMC's earnings reach $28.33 per share in 2028, and it trades at 30 times earnings at that time, a premium that a potentially stronger increase in earnings could justify, its stock price will jump to $850. That's just over double where this AI stock is right now.
So, investors looking to capitalize on the next leg of the AI infrastructure boom and hunting for an alternative to Micron and Sandisk would do well to take a closer look at TSMC before it steps on the gas.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $420,109!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,303,689!*
Now, it’s worth noting Stock Advisor’s total average return is 938% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 17, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Advanced Micro Devices, Alphabet, Apple, Goldman Sachs Group, Micron Technology, Nvidia, Oracle, Qualcomm, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


