


Micron vs. Sandisk: Which AI Memory Stock Benefits More From Nvidia's $279 Billion Warning?
Key Points
Nvidia is currently budgeting to spend $279 billion on memory through 2032.
Micron and Sandisk are top suppliers of high bandwidth memory, DRAM, NAND, and enterprise solid-state drives.
Micron is better positioned to capture infrastructure spend from the hyperscalers given its place in AI chip stacks.
- 10 stocks we like better than Micron Technology ›
The artificial intelligence (AI) memory landscape is in the middle of a messy, albeit very profitable, squeeze. Training runs are getting bigger, inference is moving into production, and every new rack of accelerators needs more bandwidth and bits sitting closer to the graphics processing unit (GPU). That is the setup fueling the memory supercycle.
The shortage is not a mystery. Wafer capacity is limited, and converting factory lines to high bandwidth memory (HBM) is tedious and costly. NAND supply is also tight, but for a different reason -- hyperscale storage requirements are being flooded by tokens that have to live somewhere after they leave the GPU.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Micron Technology (NASDAQ: MU) is cashing in on both sides of this story. The company produces the HBM that sits on top of the GPU package, as well as the server DRAM that fills the rest of the stack. Sandisk (NASDAQ: SNDK) is riding the same wave, but from the storage side, shipping enterprise flash into the same data centers.
Both companies are making more money than ever. But when Nvidia (NASDAQ: NVDA) dropped a blunt warning about the memory market during its recent earnings call, an interesting question came to mind: Which of these two stocks, Micron or Sandisk, actually sits closer to the memory bottleneck?
Image source: Getty Images.
What did Nvidia say about the memory trade?
During its fiscal second-quarter earnings call, Nvidia made it clear that memory is no longer a background cost -- it is a strategic constraint. CFO Colette Kress said the company is witnessing "extreme pricing conditions in memory," as price increases have already exceeded internal forecasts and are headed even higher going into next year.
As a result, Kress guided Nvidia's gross margin to slip and bottom in the low-70 percentage range before price increases eventually kick in. The trough should be around 71% in Q4 of fiscal 2027.
Nvidia also published a table breaking out supply and capacity commitments through fiscal 2032 -- totaling $279 billion -- and management is saying the spend is primarily related to the procurement of memory. Roughly $92 billion of this budget is due in the rest of fiscal 2027, with another $87 billion and $88 billion lined up for the following two years. This is an explicit sign that Nvidia is reserving a huge slice of the memory market through fiscal 2029 because it does not trust the current market dynamics to supply Blackwell and Vera Rubin on time.
Nvidia CEO Jensen Huang was even more direct when he explained that unconstrained demand implies growth in excess of the 70% Nvidia is willing to guide. Supply, which includes memory components, is the governing factor. All told, Nvidia did not just place a casual purchase order. The company put a multi-year claim on one of the scarcest assets in the chip value chain: memory bits.
What do hyperscalers need more of?
Hyperscalers do not buy "memory" as one component. In reality, they are buying parts to achieve three different jobs.
HBM is the scarcest layer of the memory stack. It sits on top of GPU packages and determines how fast a model can train. Without HBM, accelerators are basically just expensive chip clusters. DRAM is the workhorse around this package, feeding system memory for central processing units (CPUs) and inference hosts. Meanwhile, NAND supports the storage warehouse: training data, checkpoints, and logs. While all three components matter, they do not matter equally according to Nvidia's warning.
Nvidia is locking supply because GPU shipments depend on available stacked memory and DRAM, not because the company cannot find solid-state drives (SSDs). Micron is one of only three HBM suppliers and top-tier DRAM vendors that can supply this capacity.
Indeed, Sandisk is a serious NAND name, and AI factories will certainly continue to buy flash. In reality, flash sits further downstream in data center architectures. If a GPU cannot ship, then an order for SSDs can wait. If the HBM is not available on time, the whole rack slips. This is why Nvidia's $279 billion memory budget is a louder signal for Micron than for Sandisk.
Why Micron looks like the better buy over Sandisk
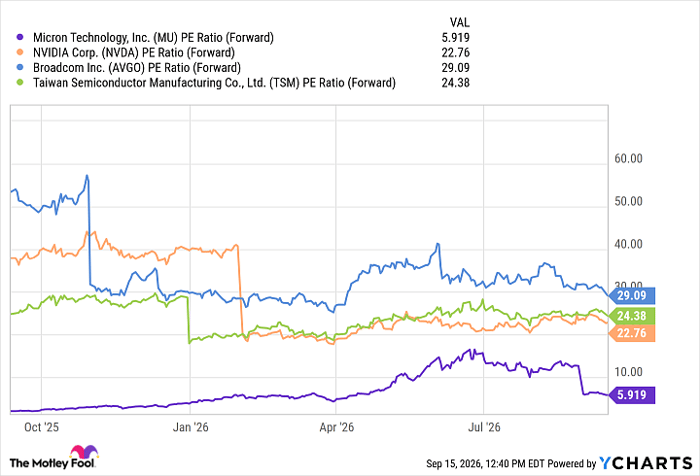
Despite its emerging role in hyperscaler data centers, Micron is not priced like a compounding growth stock. Although shares have already experienced a monster run over the last year, Micron's forward price-to-earnings (P/E) ratio hovers around 6. This is modest relative to other category-leading chip stocks like Nvidia, Broadcom, or Taiwan Semiconductor Manufacturing. The disparity in valuation multiples stems from the market treating memory as a boom-bust commodity.
MU PE Ratio (Forward) data by YCharts.
Micron is in a position to benefit from a number of secular tailwinds throughout the AI infrastructure era. Hyperscaler capex is increasingly treating memory as a first-order constraint, inference deployments are scaling (which burns more bits per token), and contractual demand provides visibility over the next few years.
Ultimately, this setup supports an environment where earnings can stay high long enough for the market to rerate valuation expansion and stop applying a deep cyclical discount.
While Sandisk will keep benefiting due to higher flash prices and a heavier mix toward enterprise data center revenue, NAND will remain a second-order winner. Nvidia did not write a quarter-trillion-dollar check because SSDs are hard to find. It did it because memory scarcity is the bottleneck that decides how many AI systems will actually get built on time. That is Micron's opportunity, which makes it the better stock to buy and hold for the memory boom.
Should you buy stock in Micron Technology right now?
Before you buy stock in Micron Technology, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Micron Technology wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $420,109!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,303,689!*
Now, it’s worth noting Stock Advisor’s total average return is 938% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 16, 2026.
Adam Spatacco has positions in Nvidia. The Motley Fool has positions in and recommends Broadcom, Micron Technology, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


