


Philadelphia Semiconductor Index Forecast: Morgan Stanley Sees Semiconductor Sector Falling Another 15%, Correction May End in Mid-November
TradingKey - Mike Wilson, Chief U.S. Equity Strategist at Morgan Stanley, maintains his forecast for the S&P 500 Index to reach 8,000 by year-end, but believes a short-term drop to 7,100–7,200 remains possible. The semiconductor sector could fall another 10% to 15%, with sector adjustments expected to end in mid-November. Based on Morgan Stanley's projections, the Philadelphia Semiconductor Index could drop to near 9,500,
His cautious outlook stems first from AI financing pressures. The market has begun questioning the timing and scale of AI revenue monetization, while government financing and non-AI capital expenditures are also competing for funds, heightening investor concerns over financing costs and capital availability for related companies. Combining technical analysis with previous trends in the silver market, Wilson's team believes that semiconductors still need to seek support at lower levels.
Tightening liquidity has further amplified the pressure. The team noted that the Federal Reserve has slowed the pace of balance sheet expansion by roughly half, leading to a marked tightening of financial conditions. Meanwhile, market demand for capital continues to rise, further reinforcing their preference for quality stocks.
However, Wilson expects concerns over AI investments to peak over the next three to four weeks, while midterm election uncertainty will also gradually fade. Historically, the S&P 500 has risen an average of about 17% in the 12 months following midterm elections. He believes that the release of these risks and shifts in liquidity will be crucial for the market to form a bottom.
Also supporting his expectation of a year-end rally are corporate earnings and internal market metrics: third-quarter corporate earnings are expected to grow 27% year-over-year, market breadth has begun to improve, and Morgan Stanley's combined sentiment indicator stands at neutral. Based on this, Wilson believes that more attractive buying opportunities are likely to emerge once risks are gradually digested over the coming weeks.
From a technical standpoint, the Philadelphia Semiconductor Index is currently hovering around 11,150. After pulling back from its October high of 13,349.96 to 10,445.44, the index staged a strong rebound, reclaiming the 0.786 Fibonacci retracement level (11,067.01), but it remains below the 0.618 Fibonacci retracement level (11,554.97).
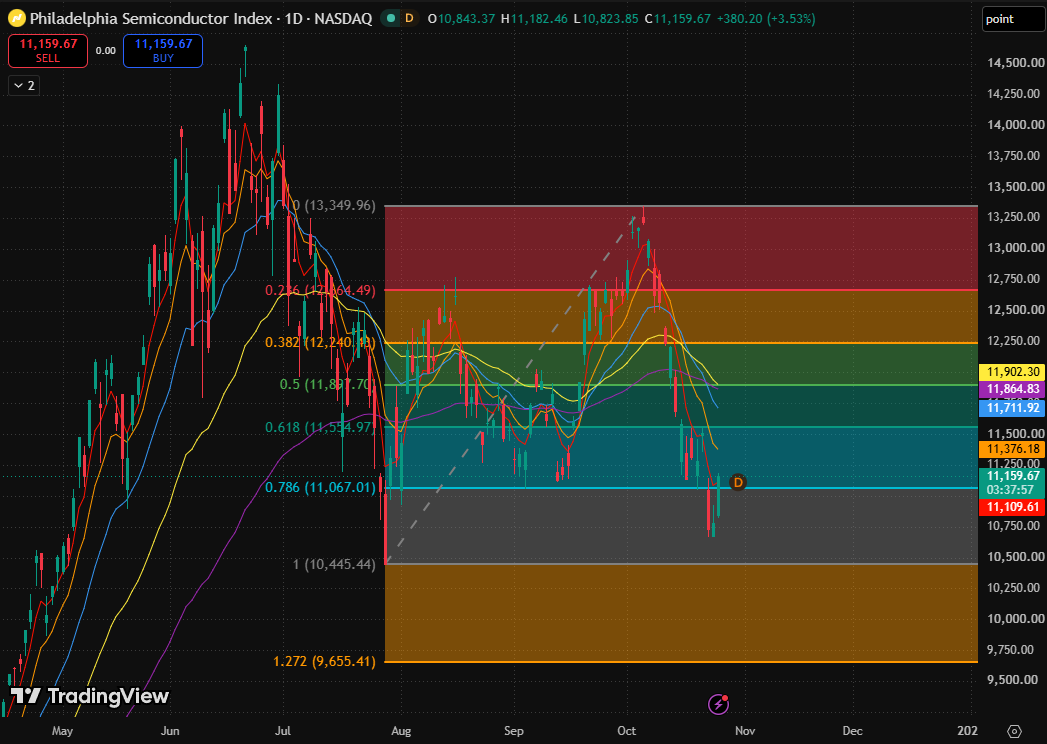
Philadelphia Semiconductor Index, Source: TradingView
The current move represents an oversold rebound following a deep pullback, with 11,067.01 serving as a key pivot for determining whether this bounce can continue. If the index can hold above the 0.786 Fibonacci retracement level (11,067.01), the rebound may go on to test the 0.618 Fibonacci retracement level (11,554.97). Further above lies a resistance zone between 11,711.92 and 11,902.30, formed by a cluster of the 20-day, 80-day, and 160-day exponential moving averages.
However, before reclaiming 11,554.97, the movement should still be viewed as a technical bounce after a decline. If the subsequent rebound stalls in the 11,376.18–11,554.97 region and fails to recover the 0.618 Fibonacci retracement level,
Since medium- to long-term moving averages remain concentrated higher up, failure to gradually reclaim these moving averages during the rally means the price action could still be just a technical bounce following a steep drop. The index might fall further to the 1.272 Fibonacci extension level (9,655.41), which aligns with Morgan Stanley's projected magnitude of further declines in the semiconductor sector.
Recommended Articles


