


Own Starbucks by Nov. 13 to Qualify for Its Nov. 27 Dividend. Here's How Many Shares You'd Need for $500 in Yearly Dividends.
Key Points
Starbucks became too transactional, eroding its brand and its role as a “third place.”
Starbucks’s turnaround is showing measurable signs of progress.
The company’s focus on high-margin growth makes it ideally suited for dividend investors.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Earlier this month, Starbucks (NASDAQ: SBUX) raised its dividend for the 16th consecutive year, boosting the payout by a modest one cent per share per quarter. Investors who own the stock by Nov. 13 will receive the new $0.63 quarterly dividend on Nov. 27. Annualized, that's $2.52 per share -- good for a forward yield of 2.6%.
Investors would need to own 199 shares to receive at least $500 in yearly dividends. That's a whopping $19,406 investment, based on Starbucks's stock price of $97.52 per share at the time of this writing.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Here's why Starbucks' investment thesis has fundamentally changed in recent years, and why Starbucks has transformed from a high-octane growth stock into a rock-solid dividend stock to buy now.
Image source: Starbucks.
Globalizing the "third place"
Howard Schultz was instrumental in elevating Starbucks from a regional coffee bean and equipment merchant into a global sensation featuring quick-service, customizable coffee and tea drinks. Schultz was inspired by a trip to Italy, where local coffeehouses served as a third place, alongside home and work/school.
Starbucks grew rapidly and expanded into new markets by pairing the third-place concept alongside a caffeine-rich, customizable menu. Schultz viewed China as Starbucks's biggest opportunity yet, even predicting in December 2017 that China could one day have twice as many stores as the U.S. However, as of June 28, 2026, Starbucks's total international store count is 22,933, including about 8,000 stores in China, compared to 18,371 in North America.
SBUX data by YCharts
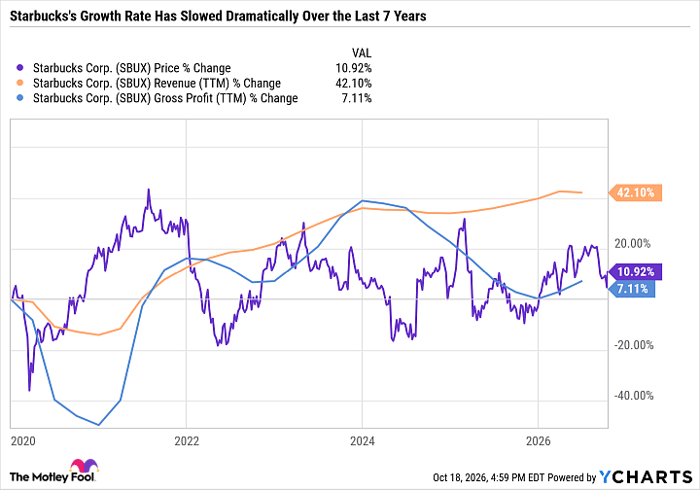
It's been a choppy period for the coffee stock -- to say the least. Over the last seven years, the stock price and gross profit have been virtually flat while revenue is up just 42.1%.
Reclaiming the third place
Starbucks reached saturation in the U.S., and international markets like China have proven more challenging to sustain growth in. Starbucks continues to have success leveraging its rewards program and cutting wait times with mobile order and pay. But those concepts also turned Starbucks into a kind of transaction-based coffee factory that churned out as many drinks as possible rather than one focused on an inviting customer experience. Mobile ordering was instrumental in limiting the pandemic-induced slowdown in order volumes. But even post-pandemic, Starbucks eventually realized that it had leaned too heavily into convenience and transactions rather than friendly service and the in-store coffeehouse experience, which had damaged its brand among partners and customers.
In Starbucks's Leadership Experience event in June 2025, Schulz and CEO Brian Niccol discussed the need to reclaim Starbucks's role as a third place for communities and become a coffee-first company. Since then, Starbucks has implemented a nationwide makeover by bringing back coffeehouse aesthetics with inviting furniture and layouts and restoring a focus on personalization and customer interaction. The strategy is working. On its third-quarter fiscal 2026 earnings call in August, Starbucks said that it had completed 1,000 North America store remodels and was showing a vast improvement in same-store sales in the U.S. and internationally. Starbucks also reduced its company-operated stores in the U.S. by 2.7% year-over-year. And its international company-owned stores dropped from 10,277 to just 2,464 because it converted 7,991 stores in China to licensed stores as part of its diversification of Starbucks retail operations in China. In April, Starbucks finalized a joint venture with Chinese private equity firm Boyu Capital that included selling a 60% stake in Starbucks China retail operations and converting company-operated stores in China to licensed stores. Starbucks hopes to grow its store count in China to 20,000 over time as part of this capital-light licensing model.
Starbucks is guiding for 6% U.S. same-store sales growth
Starbucks' new strategy is centered on improving the quality of its stores for partners and customers, managing costs, and growing margins, rather than rapidly growing revenue through new store openings. Its deal with Boyu Capital provides upside potential from expansion in China without the capital intensity of managing company-owned rather than licensed stores.
Starbucks' new strategy is already paying off. Its updated fiscal 2026 guidance now calls for over 6% U.S. same-store sales growth and global comps nearing 6%. Full-year revenue is expected to be flat or slightly up, given a lower U.S. store count and its new operating structure in China. Margins are improving too, with the overall company forecast margin considerably higher at over 11%.
Buying quality companies with growing dividends is an excellent way to participate in the stock market while boosting your passive income stream. Starbucks has been a disappointing stock to own for years, but that could change under its more focused corporate strategy that is already demonstrating tangible results. With an emphasis on operating efficiency over pure-play growth, Starbucks is well-positioned to become a top-tier dividend stock.
Should you buy stock in Starbucks right now?
Before you buy stock in Starbucks, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Starbucks wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $370,440!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,330,110!*
Now, it’s worth noting Stock Advisor’s total average return is 924% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 22, 2026.
Daniel Foelber has positions in Starbucks. The Motley Fool has positions in and recommends Starbucks. The Motley Fool has a disclosure policy.
Recommended Articles


