


History Says This Happens to Taiwan Semiconductor Stock After Oct. 15
Key Points
In three of the last four earnings reports, Taiwan Semiconductor's stock either declined or was weak following earnings.
Taiwan Semiconductor is expected to deliver its fastest growth rate in three years during Q3.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Taiwan Semiconductor (NYSE: TSM) has a big day coming up on Oct. 15: its third-quarter earnings announcement. This is one of only four times in the year to receive an update on how one of the world's most important companies is doing, and Wall Street is expecting quite the quarter. However, Taiwan Semiconductor has a habit of exceeding expectations, which could ignite another rally in the stock.
So, what does history have to say about Taiwan Semiconductor's potential following earnings? Let's find out.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
An immediate reaction isn't always the case with Taiwan Semiconductor
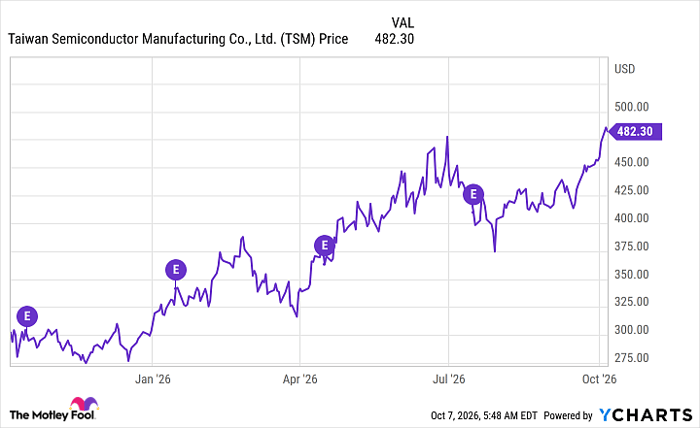
The chart shows Taiwan Semiconductor's price action after earnings.
TSM data by YCharts.
As you can see, in three of the last four earnings reports, Taiwan Semiconductor's stock either declined or was weak following earnings. That's odd, considering it beat consensus earnings-per-share estimates, and it may be a telling sign of what's to come when it reports.
However, there's a longer-term picture here: Taiwan Semiconductor's stock has always done well about a month or two after reporting earnings. I think this just points to the overall trend in the artificial intelligence (AI) semiconductor industry, so even if TSMC's quarterly results fail to deliver a one-day price spike, there could still be substantial room to run.
The future looks bright for Taiwan Semiconductor
Taiwan Semiconductor is a logic chip manufacturer and makes chips for nearly every big tech company out there. Taiwan Semiconductor's size is unmatched, providing it with a competitive advantage over its peers. As a result of its connected status, it's a great heartbeat on the AI industry as a whole, and as AI spending ramps up, so will Taiwan Semiconductor's revenue growth.
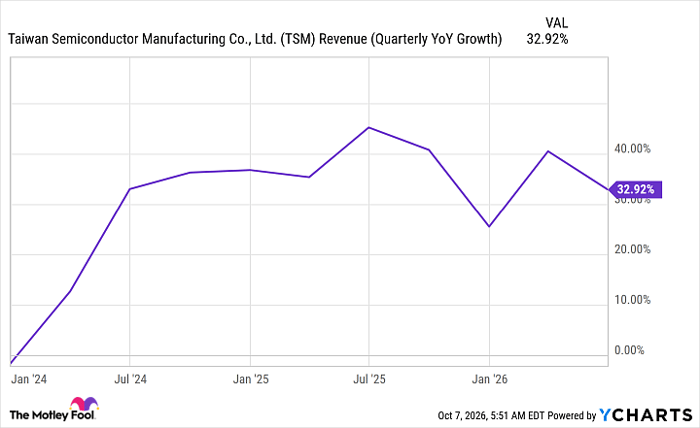
For Q3, Wall Street analysts expect 47% revenue growth. For Q4, that figure climbs to 54%. Those would be the fastest rates TSMC has delivered over the past three years, which could make TSMC a great investment pick moving forward, as the market may not be ready for the growth it's expected to deliver.
TSM Revenue (Quarterly YoY Growth) data by YCharts.
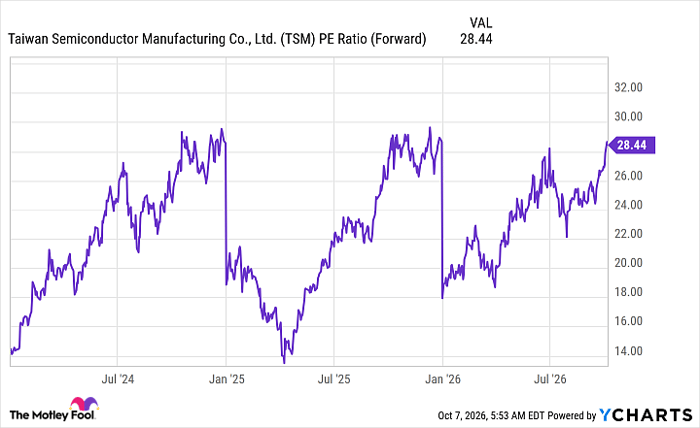
Right now, TSMC is trading within its normal valuation range, at about 28 times forward earnings.
TSM PE Ratio (Forward) data by YCharts.
While that's "normal," TSMC is also expected to grow faster than normal, so this valuation may actually be cheap. One of TSMC's largest clients, Nvidia, noted that next year data center capital expenditures from the big five AI hyperscalers are expected to rise from nearly $800 billion in 2026 to $1.3 trillion in 2027. With TSMC supplying chips to nearly every computing unit maker, this should result in strong future growth for it. As a result, Taiwan Semiconductor could be well-positioned to deliver strong end-of-year gains following its Q3 earnings report. While history doesn't support a one-day spike following earnings, a strong couple of months to close out the year could be in the cards.
Taiwan Semiconductor also has another catalyst in hand -- the company is raising foundry prices by 5% to 10% starting in 2027. While that won't help its third-quarter earnings, the price increase will add to TSMC's already impressive bottom line next year, particularly as its clients have nowhere else to go given TSMC's immense scale.
So, whether Taiwan Semiconductor's stock rallies immediately after earnings or a few months later, I think the long-term outlook for the stock is clear: Taiwan Semiconductor is a great buy today due to its leadership in chip fabrication. Without Taiwan Semiconductor, AI wouldn't look the same, and its status makes it a must-own stock.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $379,986!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,404,152!*
Now, it’s worth noting Stock Advisor’s total average return is 948% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 14, 2026.
Keithen Drury has positions in Nvidia and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Nvidia and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


