

Strong profits, falling shares: bank earnings day one meets a memory-chip rout — with CPI and ASML ahead
coverImg
Source: DepositPhotos

Mitrade Insights — Earnings season's opening day delivered its lesson early: at these prices, good numbers are not good enough. Goldman Sachs smashed forecasts (EPS $17.01 vs $13.09 expected, profit +33% to $5.1bn), JPMorgan missed ($5.75 vs $5.93), Citigroup beat and Wells Fargo slipped 3% — and the S&P 500 still finished almost exactly flat at 7,805.45 (−0.02%), pinned roughly 13 points below its 7,818.93 record close as a memory-chip rout ran through the tape (Micron now trades under $1,000). The stakes compound tonight: US September CPI lands at 8:30 ET, followed before the open by Bank of America, Morgan Stanley, BlackRock and ASML.

The move: one flat close, four very different banks

BankQ3 resultStock reaction
Goldman SachsEPS $17.01 vs $13.09 expected; revenue +23% to $18.7bn; equities-trading bonanzaMixed prints across sources (~−0.2% to +1.4% intraday)
JPMorganEPS $5.75 vs $5.93 expected; revenue $50.17bn vs $51.23bn; FICC −4%, first decline in 2+ years; raised 2026 NII guidance~−0.9%
CitigroupEPS $2.85, net income $5.2bn, revenue +8% to $23.8bn; best FICC third quarter in a decadeDeclined (equities desk trailed Goldman)
Wells FargoEPS $1.87 beat; revenue $21.87bn missed−3%

The indices tell the same story of a market absorbing conflicting signals: the Dow fell 0.35% to 51,670, the Nasdaq eased 0.15% to 27,204, and the S&P 500 held the line — but beneath the surface, memory-chip names kept bleeding after Monday's Philadelphia Semiconductor Index slide of 2.67%.

Why: the bar was set at "spectacular"

Three forces turned strong results into a shrug.

Expectations. FactSet-tracked consensus put S&P 500 Q3 earnings growth near 30% year-over-year — a bar so high that banks "still reported strong numbers, but expectations were high," as Walser Wealth's Rebecca Walser put it. When the bar is spectacular, merely strong is a miss.

Trading normalisation. JPMorgan's FICC revenue fell 4%, its first decline in more than two years, and Jamie Dimon flagged a more cautious underwriting stance. The trading boom that carried bank earnings all year is cooling — and the market pays for pace, not level.

The AI trade's wobble. The memory complex remains the pressure point: China's CXMT unveiled progress on a 4F² DRAM architecture with plans to mass-produce server DDR5 RDIMM modules by year-end, reviving supply fears on top of Broadcom's warning that some AI infrastructure deals resemble "gambling". Goldman Sachs' verdict is blunt — "memory remains the epicenter" — with peak-earnings worries compressing valuations even as fundamentals stay strong. Add a 10-year Treasury yield near 5.30%, its highest since 2002, and the multiple has nowhere to hide.

The bull case vs the bear case

The bull case. The quarter's engine is intact: Goldman's equities franchise posted a blowout, JPMorgan raised its 2026 net-interest-income guidance, and Citigroup delivered its best FICC third quarter in a decade — a signal that credit and capital-markets activity remain healthy. Fed speakers are also softening: both John Williams and Christopher Waller signalled this week that one more hike may suffice for the year, with none needed next year. A soft CPI tonight would amplify that pivot and give equities room to challenge the record.

The bear case. Expectations stay punishing all season; the FICC miss shows the trading tailwind fading; the memory rout threatens to spread from chips to the broader AI complex; and December hike odds near 88–90% keep the discount rate elevated. With the index sitting at record levels, every piece of bad news gets an outsized vote.

Levels: 7,818.93 is the gate
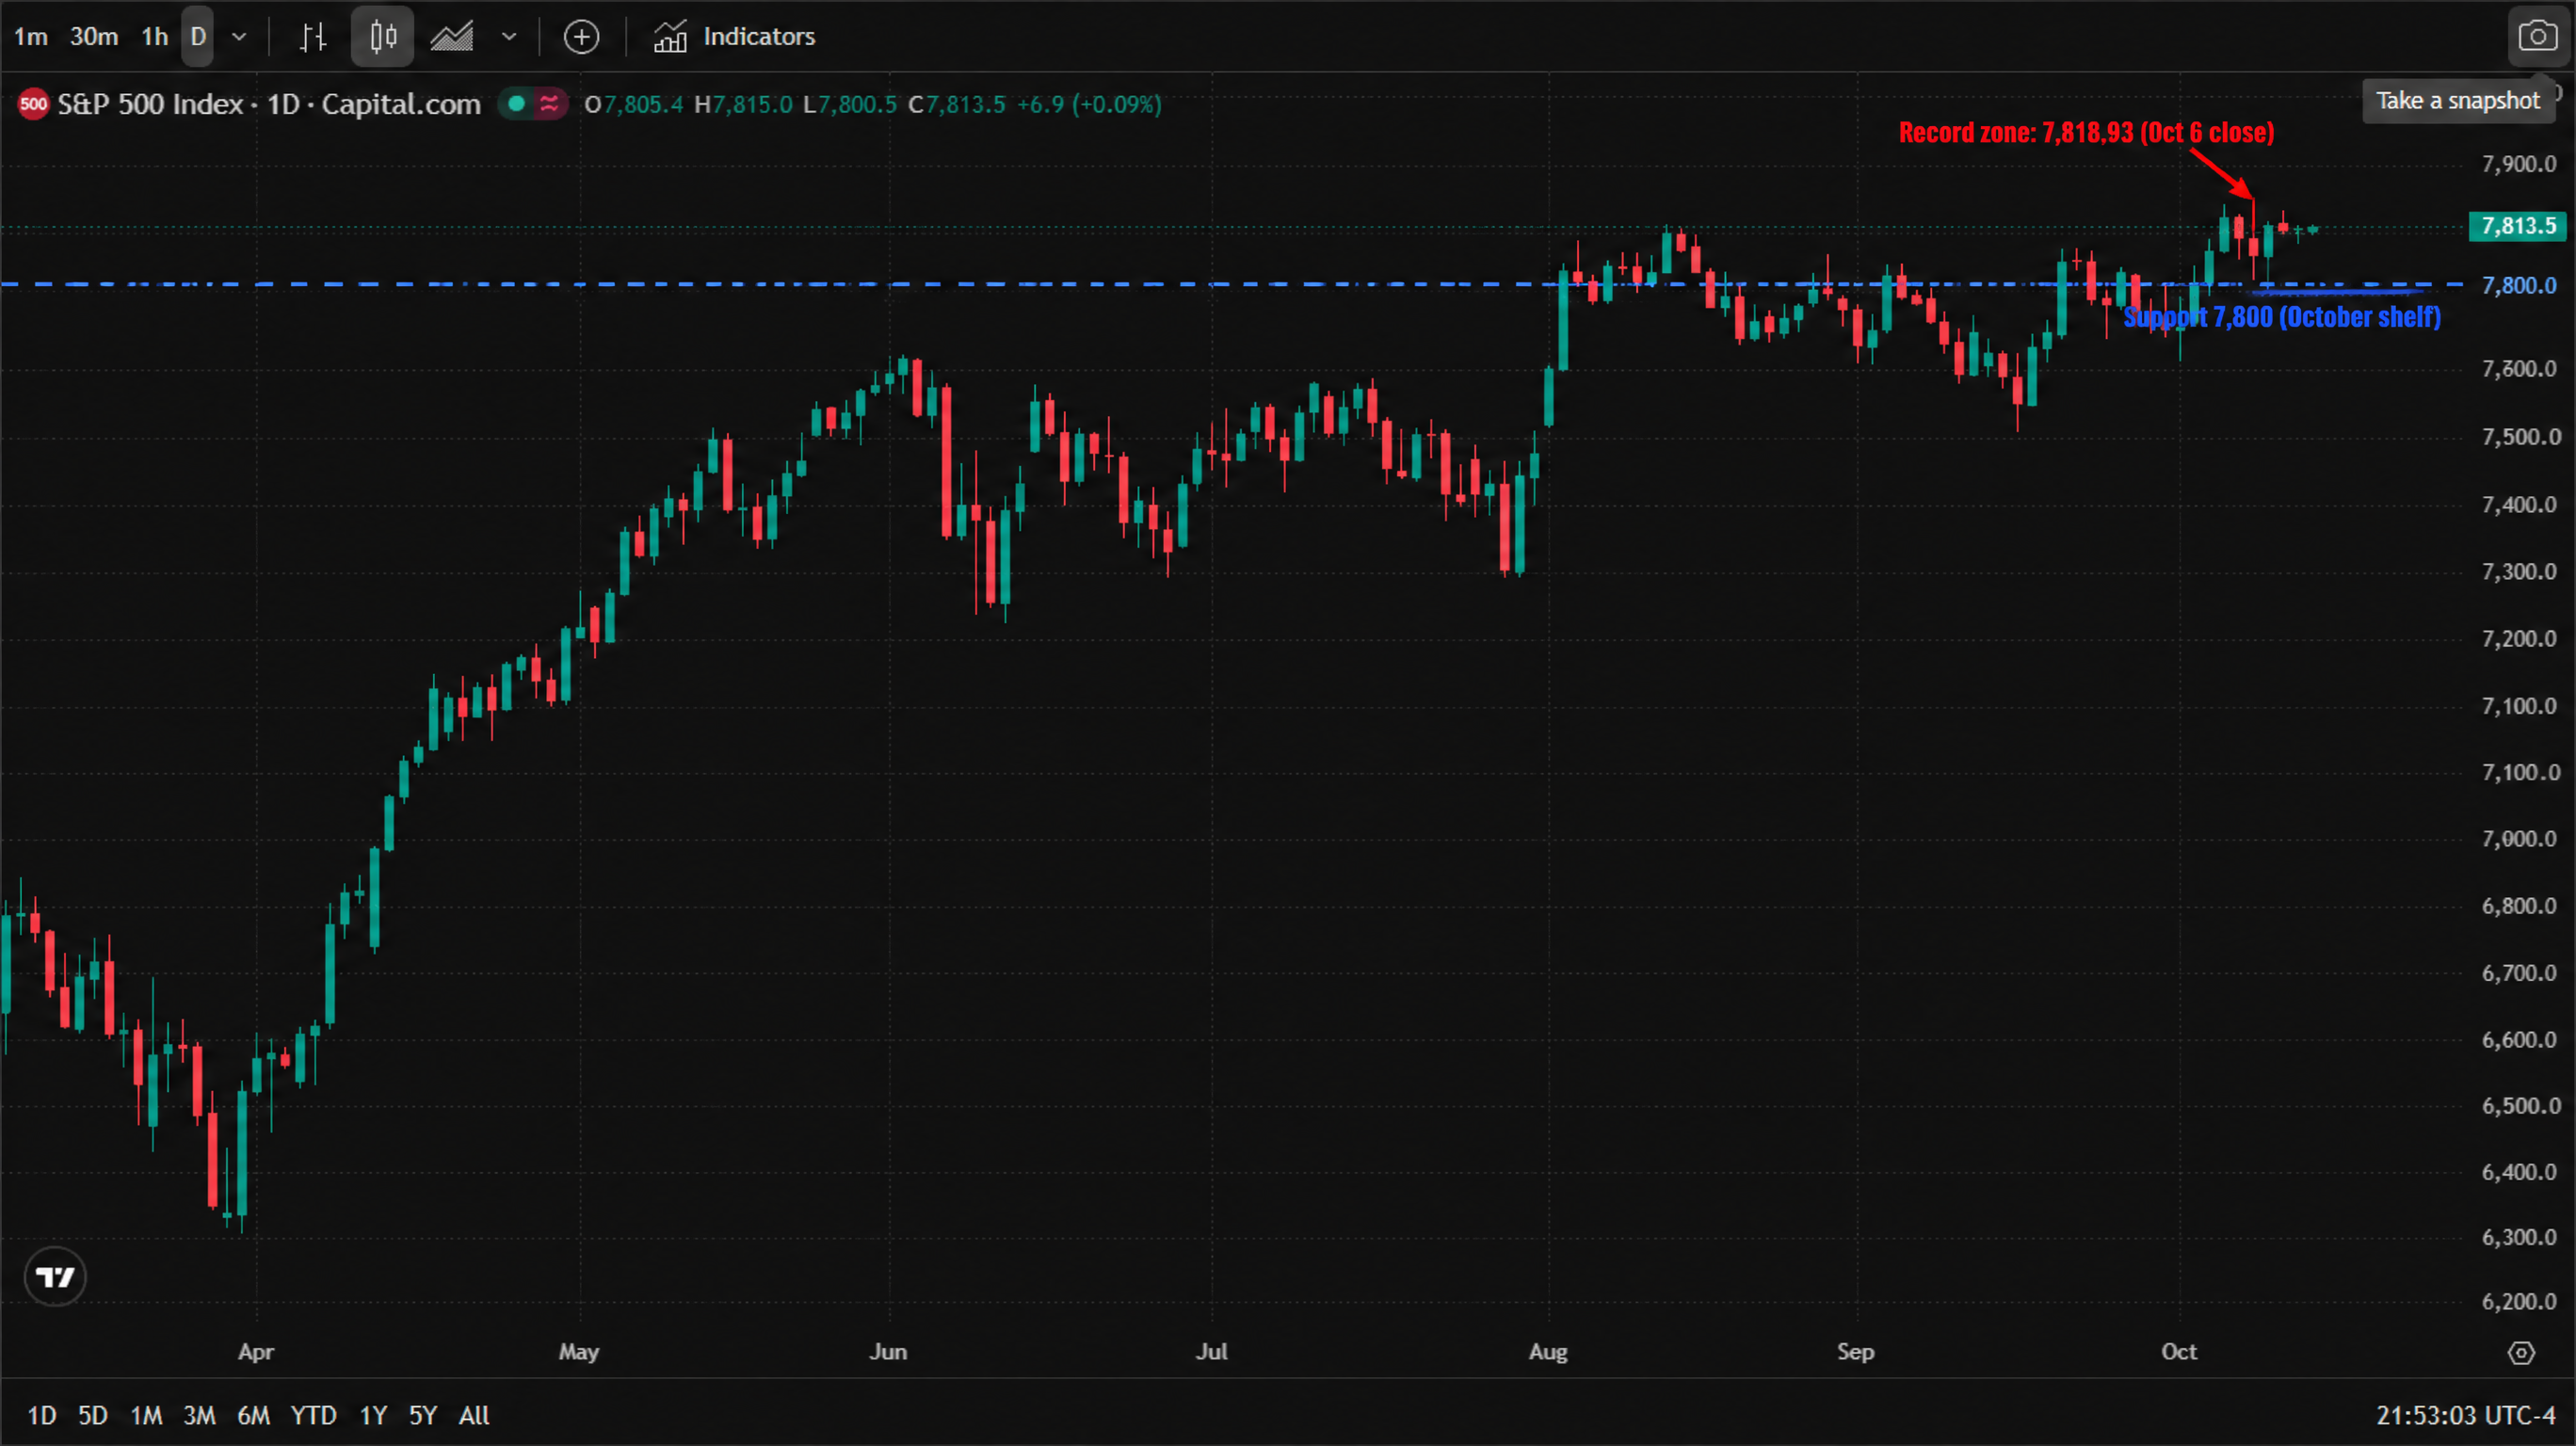
S&P 500 Index (Capital.com quote) daily candlestick chart, April to October 2026 — April bottomed near 6,420; a V-shaped recovery lifted the index through May and June to a ~7,640 June high; July consolidated between 7,300 and 7,560; August broke higher toward 7,780; September ranged between 7,560 and 7,760; October pressed back into the record zone above 7,800, last at 7,813.5 (+0.09%). The chart marks support at 7,800 (blue line) and flags the record-close zone at 7,818.93 (red arrow, Oct 6).

* Chart source: TradingView official chart screenshot, data source Capital.com (S&P 500 Index).

The structure to respect: the record close at 7,818.93 is the gate — a decisive close above it opens blue sky, while the 7,800 round number is the shelf that has held every October dip; below it, 7,750 marks the mid-October floor. The tape is coiled between support and record, waiting for a referee.

What to watch: CPI first, then four more earnings

  1. 8:30 ET — US September CPI. Headline is expected at 3.6–3.7% year-over-year (from 3.4%) on a record $4.33-a-gallon September gasoline average; the decider is the core monthly print: ~0.2% keeps the Fed on hold, 0.3% revives October hike bets and hits both bonds and stocks.

  2. Before the open — Bank of America, Morgan Stanley, BlackRock. The second wave of bank results tests whether JPMorgan's FICC caution was company-specific or sector-wide.

  3. ASML's Q3 report. Watch net bookings and 2027 capacity comments — the first hard evidence on whether AI's memory-driven capex cycle is still accelerating.

  4. Thursday — US PPI and the semiconductor earnings relay. Together with tonight's CPI, they frame the final stretch into the October 27–28 FOMC.

The tell for the week: if CPI lands soft and ASML's bookings hold up, Tuesday's flat close will look like resilience; if either disappoints, the record zone starts to look like a ceiling instead of a launchpad.

Read more

  • Gold Price Forecast: Gold Tumbles Below $3,900 as Trump Says No Need for Iran Deal; Can October PPI Spur a Rebound?
  • Gold hit a one-year low while central banks bought 321 tonnes — the sellers were never the ones you think
  • Note: If you want to share the article 《Strong profits, falling shares: bank earnings day one meets a memory-chip rout — with CPI and ASML ahead》, make sure you retain the original link. For more information, please visit Insights or browse www.mitrade.com.

    * The content presented above, whether from a third party or not, is considered as general advice only.  This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.

    goTop
    quote
    Related Articles
    placeholder
    Weekly Report: The index rose 2.5% while Nvidia fell 12.7% — two equity divergences, one should closeThe S&P 500 rose 2.51% to 7,561.67 and the QQQ rose 3.63% to 679.89 last week, while Nvidia fell 12.75% to 162.85 — a sixth straight weekly loss and 32% below its October record. In the same five sessions, energy equities rose 5.42% while WTI fell 2.52%. Both pairs normally move together (60-day correlations of +0.64 and +0.58). This report ranks which divergence closes first, with the trigger for each.
    Author  Irene Q.
    1 hour ago
    The S&P 500 rose 2.51% to 7,561.67 and the QQQ rose 3.63% to 679.89 last week, while Nvidia fell 12.75% to 162.85 — a sixth straight weekly loss and 32% below its October record. In the same five sessions, energy equities rose 5.42% while WTI fell 2.52%. Both pairs normally move together (60-day correlations of +0.64 and +0.58). This report ranks which divergence closes first, with the trigger for each.
    placeholder
    Anthropic is six times oversubscribed at $1.4 trillion while Nvidia is down 32% — the AI trade has two pricesAnthropic lists on Nasdaq as ANT on Thursday at $70 ~ $78 a share, raising up to $64.4 billion at a target valuation near $1.4 trillion, and the book is reportedly six times covered. In the same six weeks, Nvidia has fallen 32% and the QQQ is 10.9% below its October peak. Private capital and public markets are marking the same AI complex at two very different prices. This piece separates the two books: what the S-1 shows, who is anchoring the $26 billion private placement, and what Thursday's debut would have to do to change the public tape.
    Author  Irene Q.
    1 hour ago
    Anthropic lists on Nasdaq as ANT on Thursday at $70 ~ $78 a share, raising up to $64.4 billion at a target valuation near $1.4 trillion, and the book is reportedly six times covered. In the same six weeks, Nvidia has fallen 32% and the QQQ is 10.9% below its October peak. Private capital and public markets are marking the same AI complex at two very different prices. This piece separates the two books: what the S-1 shows, who is anchoring the $26 billion private placement, and what Thursday's debut would have to do to change the public tape.
    placeholder
    Nvidia reports tomorrow with an interim CEO — $108 billion is the easy numberNvidia closed at 162.85 on Friday, down 12.75% on the week and 32% below its 6 October record, with market value down to $3.92 trillion. The Q3 bar is $108 billion ±2%, and consensus already sits at $108.7 ~ 108.8 billion, so the revenue line is not where the surprise lives. The number that decides the reaction is the 71 ~ 72% Q4 gross-margin trough, followed by a Q4 guide against a $124.9 billion consensus. This piece prices the print, marks the 158.39 line and lays out the three scenarios in a table.
    Author  Irene Q.
    1 hour ago
    Nvidia closed at 162.85 on Friday, down 12.75% on the week and 32% below its 6 October record, with market value down to $3.92 trillion. The Q3 bar is $108 billion ±2%, and consensus already sits at $108.7 ~ 108.8 billion, so the revenue line is not where the surprise lives. The number that decides the reaction is the 71 ~ 72% Q4 gross-margin trough, followed by a Q4 guide against a $124.9 billion consensus. This piece prices the print, marks the 158.39 line and lays out the three scenarios in a table.
    placeholder
    Today’s Market Recap: Nvidia Drops Over 4% After Jensen Huang Resigns, AMD and Broadcom Both Rise Over 5% On November 12, the three major U.S. stock indices closed slightly lower. Nvidia announced that Jensen Huang had stepped down immediately as CEO and director, draggi
    Author  TradingKey
    Nov 13, Fri
    On November 12, the three major U.S. stock indices closed slightly lower. Nvidia announced that Jensen Huang had stepped down immediately as CEO and director, draggi
    placeholder
    US October PPI Preview: Fed Rate Hike Expectations Rise, PPI May Be Key Variable; How Will US Stocks, Dollar, and Gold Move?On Friday (Nov. 13) Eastern Time, the U.S. will release the October Producer Price Index (PPI). Following the October CPI once again exceeding expectations, the market will look to the PP
    Author  TradingKey
    Nov 12, Thu
    On Friday (Nov. 13) Eastern Time, the U.S. will release the October Producer Price Index (PPI). Following the October CPI once again exceeding expectations, the market will look to the PP
    Live Quotes
    Name / SymbolChart% Change / Price
    US500
    US500
    0.00%0.00
    JPM
    JPM
    0.00%0.00

    US Stocks Related Articles

    • 10 Best Day Trading Platforms for Beginners and Active Traders in 2026: A Practical Guide
    • How To Invest in SpaceX Stock in 2026? Everything Investors Need to Know
    • Practice Trading Us Stocks? These Are 10 Best Stock Trading Demo Apps For Beginners
    • ​5 Best Paper Trading Platforms for 2026 (Free Demo Accounts for Beginners & Traders)
    • Wall Street’s Top 10 US Stocks for 2026 vs What Reddit Is Actually Buying
    • Is Mitrade Right for You? A Complete Guide on How to Start Trading CFDs in 5 Steps

    Click to view more