


Why Signet Jewelers Stock Jumped 24% in September
Key Points
Signet topped estimates on the bottom line, and raised its guidance for the full year.
The retailer announced an accelerated share repurchase program of $125 million.
The stock looks cheap at a price-to-earnings ratio of 9.
- These 10 stocks could mint the next wave of millionaires ›
Shares of Signet Jewelers (NYSE:SIG) were moving higher last month as the world's largest retailer of diamond jewelry reported better-than-expected results in its second-quarter earnings report and announced an accelerated share repurchase program.
Investors cheered the news, and by the end of the month, the stock had finished up 24%, according to data from S&P Global Market Intelligence.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
As you can see from the chart below, the stock soared on the report and stayed up from there.
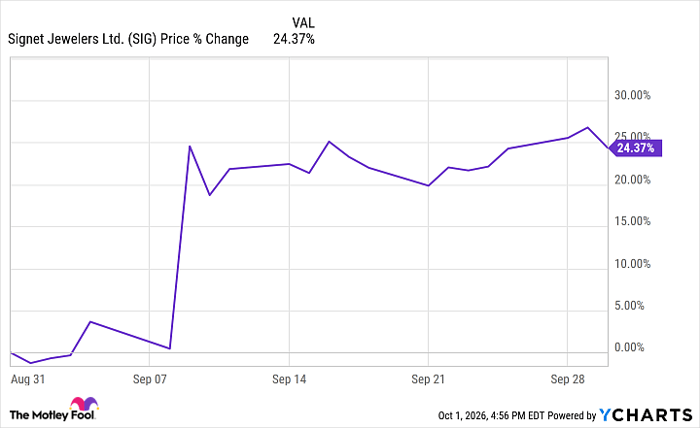
SIG data by YCharts
Signet dazzles in its Q2
Signet has traded sideways over the last few years, as the value stock has struggled to deliver consistent growth. However, in the second quarter, Signet delivered strong numbers across the board.
The company reported same-store sales growth of 2.2%, while revenue was down 0.5%. That reflects its store rationalization program as the company is focused on trimming its footprint to invest in its highest-performing stores. Revenue of $1.53 billion matched estimates, but what was more impressive was Signet's performance further down the income statement.
Adjusted earnings per share jumped from $1.61 to $2.19, well ahead of the consensus at $1.74, as the company gained leverage from its same-store sales growth, lifted its gross margin by 80 basis points, and cut selling, general, and administrative expenses by 2.4%. Adjusted operating income rose from $85.4 million to $107.2 million, benefiting from buybacks as shares outstanding fell by 4%.
It also raised its full-year adjusted EPS guidance from $9.20-$11.00 to $10.45-$12.15, indicating it expects margins to continue to improve in the second half of the year.
Investors were also pleased with the company's new $125 million accelerated share repurchase program, which is roughly 3% of its market cap.

Image source: Getty Images.
What's next for Signet
Signet has struggled to grow comparable sales and earnings per share in recent years, but the company now sees full-year comparable sales of flat to 2.5%.
Based on its updated guidance, Signet now trades at a price-to-earnings ratio of around 9, which is attractive for an industry leader, especially if it can continue to deliver same-store sales growth and buy back its stock.
If it can deliver more cost cuts, that will only increase its upside potential. Keep an eye on comparable sales going forward, as positive growth in that metric will push the stock higher.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 932%* — a market-crushing outperformance compared to 211% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
See the stocks »
*Stock Advisor returns as of October 2, 2026.
Jeremy Bowman has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Recommended Articles


