


Dell's AI Server Backlog Has Ballooned to $95 Billion. Here's What a $1,000 Investment Today Could Be Worth by 2030
Key Points
Dell is poised to capitalize on strong AI server shipments, higher average selling prices, and an improving market share.
The high-flying AI stock trades at a very attractive valuation despite its multibagger performance in 2026.
Dell's bottom line can grow at a terrific pace through 2030, setting the stock up for significant gains.
- 10 stocks we like better than Dell Technologies ›
Dell Technologies (NYSE: DELL) is playing a central role in the global artificial intelligence (AI) infrastructure ecosystem by providing high-end servers, networking, and storage solutions.
The strong demand for these AI infrastructure components has supercharged growth in Dell's Infrastructure Solutions Group (ISG) segment. The company reported a terrific year-over-year revenue increase of 89% in the ISG business in the second quarter of fiscal 2027 to a record $31.8 billion, driven mainly by demand for AI servers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The good news for Dell stock investors is that the AI server market is poised to grow at a fast clip over the long run. Importantly, the company has already built a solid backlog that should ensure healthy growth in the ISG segment. Let's take a closer look at Dell's AI server backlog and see why it can send the stock soaring over the next four years.
Image source: The Motley Fool.
Dell is scratching the surface of a massive opportunity
Dell's AI server orders reached a record $60.9 billion in fiscal Q2 (which ended on July 31). The company recognized $16.4 billion in AI server revenue during the quarter, which explains why its backlog increased to a whopping $95 billion.
Dell has received $131.7 billion in AI server orders over the past 12 months, and its growing backlog suggests that the ISG business is on track to get even bigger. Dell expects to sell $74 billion in AI servers in fiscal 2027, a 3x increase over its fiscal 2026 AI server revenue. Importantly, Dell estimates that its potential AI server order pipeline is in multiples of its backlog.
So, the $95 billion backlog figure could jump substantially going forward. After all, Goldman Sachs estimates that the AI server market could generate $1.24 trillion in revenue in 2030. The investment bank had earlier estimated the AI server market's revenue would hit $961 billion by the end of the decade. It has significantly raised that forecast due to heavy investments in AI infrastructure.
Even better, Goldman Sachs notes that a combination of strong volume and higher pricing will drive growth in the AI server market. The firm has increased its average selling price (ASP) estimate by 15% for AI servers over the prior estimate. Another piece of good news for Dell investors is that the company is gaining share in AI servers.
Specifically, Dell's AI server revenue share increased to 17% in the first quarter of 2026, up from just 5% in the year-ago quarter, driven by robust adoption of its solutions by both enterprises and neocloud infrastructure providers. If Dell maintains even 20% share of AI servers in 2030, its annual revenue from this segment could jump to $248 billion. That would be a jump of over 3x from the AI server revenue it anticipates for the current fiscal year.
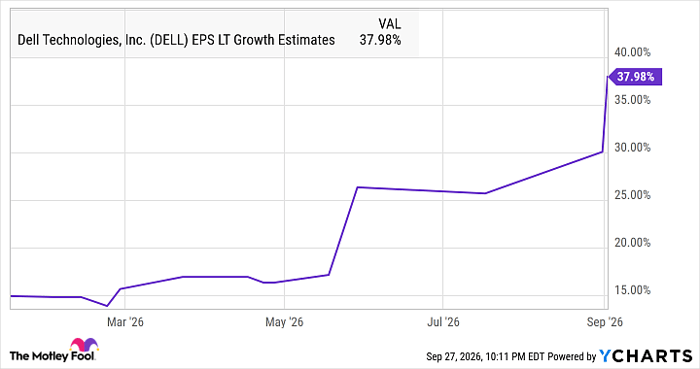
Throw in the potential improvement in AI server ASPs, and it is easy to see why analysts have become increasingly bullish about Dell's long-term earnings growth prospects.
Data by YCharts
Why now is a good time to invest $1,000 in this AI stock
Dell stock has jumped 347% in 2026, as of this writing. Even then, it trades at a reasonable 32 times trailing earnings. The forward earnings multiple of 21 is even more attractive compared to the Nasdaq-100 index's forward earnings multiple of 24.
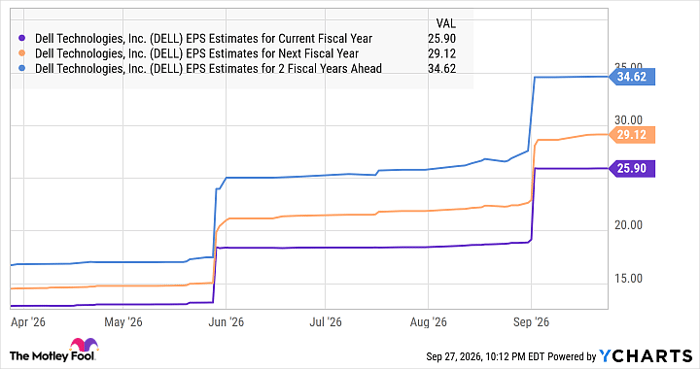
Buying this AI stock at these multiples is a no-brainer, especially considering that Dell expects a 148% jump in non-GAAP earnings per share (EPS) in fiscal 2027 to $25.50. Analysts are expecting a slowdown in Dell's EPS growth over the next couple of fiscal years, though that's unlikely to be the case given strong AI server demand and higher ASPs.
Data by YCharts
But even if Dell's earnings reach $34.62 per share in fiscal 2029, and it clocks a 38% EPS jump in fiscal years 2030 and 2031 (based on analysts' long-term growth estimate seen earlier in the article), its EPS could hit $65.93 in fiscal 2031 (which ends in January 2031). If this tech stock trades at 24 times earnings at that time, in line with the Nasdaq-100 index's forward earnings multiple, its stock price could jump to $1,582.
That's almost thrice Dell's current stock price. So, if you've $1,000 in investible cash after meeting your expenses, clearing high-interest debt, and saving enough for tough times, buying Dell with that cash could be a smart move, as it has the potential to triple your money by 2030.
Should you buy stock in Dell Technologies right now?
Before you buy stock in Dell Technologies, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Dell Technologies wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $383,680!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,382,954!*
Now, it’s worth noting Stock Advisor’s total average return is 937% — a market-crushing outperformance compared to 214% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 28, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Goldman Sachs Group. The Motley Fool has a disclosure policy.
Recommended Articles


