


Accenture Stock Forecast: Can AI Demand Rescue ACN Ahead of Q4 Earnings?
TradingKey - Accenture (NYSE: ACN) will release FY2026 and Q42026 results on Thursday, October 1, 2026, before the market opens. Its last close was at $183.52 on September 23. Accenture has partnered with several Artificial Intelligence (AI) companies, and its recent focus on AI has strengthened its strategy. However, the focus will be on the demand for AI and other companywide solutions in this quarter’s report. Wall Street will also be interested in the company’s guidance for FY2027.
Q3 Profit Improved While Bookings Weakened
Revenue in Q3 was $18.72 billion, a 6% increase from last year. Free cash flow improved to $3.6 billion from last year’s $3.5 billion. For the quarter, operating margin improved to 17.0% from 16.8% the previous year. EPS was $3.80, a 9% increase from the previous year. The company has largely benefited from remaining profitable despite selective customer spending, and the company continued to generate cash from operations and improve profitability. Strong bookings would have signaled improved demand for the company’s services, but bookings declined 2% to $19.32 billion. The company reported a 1% increase in its consulting services from last year in local currency. Bookings will be a key driver to improve the company’s stock performance.
AI Demand Is Real, but It Must Show Up in Bookings
Accenture mentions clients transitioning from one AI project to larger company-wide transformations. As per the latest earnings report, another 100 clients initiated advanced AI projects in Q3. In addition, bookings from key emerging AI and data partners are expected to more than double from fiscal 2025. Though these represent positive trends, they don’t provide insights on company’s overall revenue. There are other indicators that company management should be highlighting, for example, trends in bookings and/or client momentum in the consulting business. Management should also be communicating about AI projects driving client transformation over several years.
Anthropic Adds a Large Strategic Commitment
On September 18, Anthropic and Accenture announced that each company expects to invest at least $1 billion over five years, for a combined commitment of at least $2 billion, focused on AI safety, model evaluation, red-teaming, alignment assessments and safeguard testing. Accenture, however, should not view this as a $2 billion contract. This partnership allows Accenture to gain a competitive edge in AI by further expanding its capabilities in evaluation and testing AI models. Although Accenture has partnered with multiple AI and data companies, this deal also allows Accenture the ability to integrate additional AI solutions with its clients. Overall, the partnership is positive, however, clients should be evaluating other deals Accenture has made to gain a more positive outlook on the company.
AWS Broadens the Mid-Market Opportunity
Accenture has recently taken steps to expand its cloud and AI strategies with Accenture Edge. On September 22, Edge and AWS announced a partnership to provide a set of services targeted toward mid-market companies. These services are available through AWS Marketplace. The collaboration includes six offerings for companies with roughly $300 million to $3 billion in annual revenue. Traditionally, Accenture has worked with larger companies; therefore, this focus on mid-market companies is a change in strategy. Expanding its work with mid-market companies would allow Accenture to develop a more consistent and repetitive way to offer cloud, AI and related security services. Although demand for these offerings is likely, Accenture must gain new customers in this market to create a competitive edge. The edge may be tough to find, but the upcoming results are likely to give more insights into potential clients and markets.
Within Adds Another AI Automation Layer
On September 23, Accenture announced an investment in Within and a related business process automation partnership. Within has technology that, from Accenture’s perspective, can positively influence its client’s businesses and help differentiate Accenture from its competitors. Accenture has published research that highlights the challenges businesses face when utilizing AI and other technology to transform their businesses. Accenture believes the research identifies a clear opportunity for Accenture to increase its revenue by facilitating larger transformation projects.
Q4 Guidance Sets a Reasonable Revenue Bar
In its June outlook for fiscal Q4, which ends in August, Accenture expects revenue between $17.75 billion and $18.4 billion. Management expects constant currency growth to be between 1% and 5%.
Analysts, on average, currently expect Accenture to report revenue of about $18.05 billion and EPS of about $3.19 in the fourth quarter. The EPS expectation is the consensus of the analysts’ expectations and should not be construed as official guidance. The full year expectation is for adjusted EPS of $13.78 to $13.90 and free cash flow of $10.8 to $11.5 billion. GAAP diluted EPS guidance is $13.38 to $13.50.
With the expectations set by management, the near-term bar for quarterly revenue is within Accenture’s guidance range, while EPS remains an analyst estimate rather than company guidance. How the market reacts to long term expectations set for Fiscal Year 2027 will be the major market movement catalyst.
Fiscal 2027 Guidance Is the Real Catalyst
The FY26 guidance update provided by Accenture during Q3 reflects a narrowing of the outlook for growth in local currency to between 3.0% and 4.0% from the company’s previous outlook of between 3.0% and 5.0%.Accenture attributed the narrowing of the outlook while noting an estimated 1 percentage-point negative impact from its U.S. federal government business. Given these developments, what the company communicates about its outlook for FY27 will be closely watched.
Capital Returns Provide Support, but Not the Thesis
Accenture increased its planned FY2026 share repurchase program by $2 billion to $7.5 billion, using its existing Board authorization. Buybacks provide no strategic value. Lower valuations may result in a better floor for the stock, but a sustainable ceiling is more likely to be determined by Better bookings and more Meaningful growth in the Consulting business.
What Would Strengthen the Bull Case
My bias is still neutral heading into October 1. More constructive views would take more bookings and faster growth in consulting. Positive views would also take broader, more upward revision to AI related fiscal 2027 guidance across the firm. Negative surprises would include weaker bookings and/or weaker AI demand across the firm and other divisions. Negative surprises would also include broad based and ongoing Revenue and EPS misses.
Accenture Technical Analysis: ACN Needs $188.28 Breakout to Rebuild Momentum
Accenture’s latest confirmed closing price was at $183.52. The stock has traded lower this month, falling from its high of $197.63 on September 15 to a low of $180.70 on September 18.
Price has failed to move above the $188.28 to $190.24 resistance level and is holding just above the $180.70 to $182.56 support area.
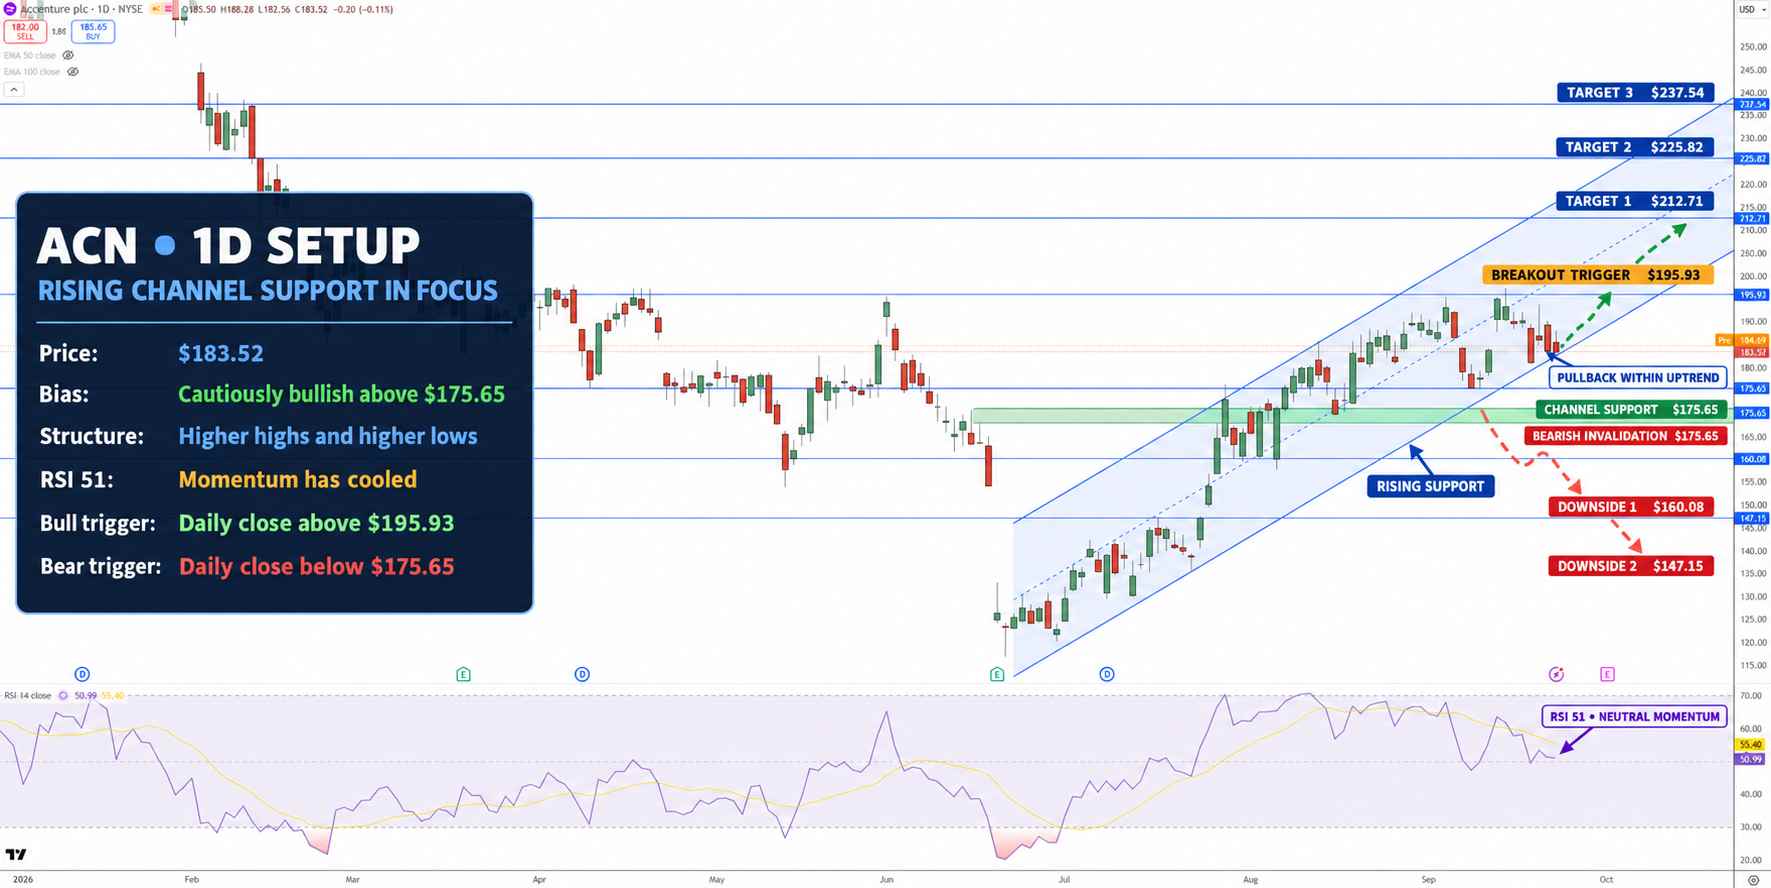
Accenture Stock Price Chart - Source: Tradingview
The 14-day RSI based on last trade data is approximately 47, placing it in neutral territory. A sustained move higher toward and above 50 would be more favorable from a bullish perspective, while a drop below 47 would indicate weaker momentum.
In the near-term, a close above $188.28 would put $193.75 in play and a close above September's high at $197.63 would be the next upside target.
While bearish, the September 18 low at $180.70 would come into play, with additional support seen at $175.50 and $175.80.
From a trading perspective, a neutral-to-bullish bias would be justified above $188.28. A break and close above $193.75 would be the first step in confirming an uptrend.
Key Levels
• Closest recorded completed trade: $183.52
• Main support: $182.56 to $180.70, then $175.50 to $175.80
• Main resistance: $188.28, $193.75, $197.63
• RSI: 47
• Breakout: $193.75, then $197.63
Why is Accenture stock in focus now?
Accenture will release its fiscal fourth quarter and full year 2026 results on October 1. Prior to the release, investors will be looking at bookings, consulting revenues, demand for and delivery of AI-related services, and the company’s outlook for fiscal year 2027. If the AI-related work is large enough, it could transform Accenture’s overall business and drive growth across the company.
What level confirms a stronger ACN recovery?
A move above $188.28 would be positive, and a move above $193.75 would be bullish. A move below $180.70 would be bearish.
Bottom Line
Accenture has announced a number of partnerships with AI companies. However, management will need to show evidence of an improvement to the company’s financial results as a result of these partnerships.
The primary focus will be on bookings and management’s outlook for fiscal year 2027. Current analyst consensus is around $18.05 billion in Q4 revenue and about $3.19 in EPS; these are analyst estimates, while Accenture’s official Q4 guidance is for $17.75 billion to $18.4 billion in revenue.
From a technical analysis perspective, Accenture remains neutral to bearish below $188.28. A close above $193.75 would indicate an improvement in the company’s stock price. A close below $180.70 would indicate a continuation of the bearish trend.
Recommended Articles


