


Prediction: This Is What a $500 Investment in Sandisk Will Be Worth in 2030
Key Points
Analysts expect Sandisk's earnings growth rate to contract after a couple of years, but that may not be the case.
AI data center investments will continue to head higher over the long run, giving Sandisk ample room to increase sales volumes.
Sandisk stock can deliver healthy gains even if its earnings increase at a conservative pace.
- 10 stocks we like better than Sandisk ›
Sandisk (NASDAQ:SNDK) was spun off from hard disk drive (HDD) specialist Western Digital in February last year, and anyone who bought its shares at that time is sitting on eye-popping gains right now.
An investment of $500 in Sandisk stock when it was spun off is now worth over $26,000. These gains of more than 52x have been fueled by a severe shortage in the NAND flash storage market. The artificial intelligence (AI)-fueled demand for data center storage has created incredible demand for Sandisk's NAND flash storage products, and supply constraints have led to a big spike in prices.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
As a result, the NAND flash market's revenue is projected to increase by a whopping 372% this year, according to Gartner. Investors, however, may be wondering if it is a good idea to buy this tech stock following its stunning run over the past year and a half. The good news is that if you have $500 in investible cash right now, putting that money into Sandisk could be a smart move.
Let's look at the reasons why.

Image source: The Motley Fool.
Booming AI infrastructure investments will ensure terrific demand for Sandisk's solutions
AI infrastructure investments are poised to increase at a robust pace over the long run. Consulting firm PwC projects that the annual capital spending on AI infrastructure could increase from $800 billion in 2026 to $1.8 trillion in 2050.
The firm notes that the need for chip upgrades in data centers will primarily drive the healthy long-term spending on AI infrastructure. Specifically, investments in chips and other hardware could account for 93% of AI data center investments in 2050, up from 70% currently.
Storage is a critical component in AI data centers. Complex large language models (LLMs) and inference applications require real-time access to huge data sets, which explains why the demand for enterprise-grade solid-state drives (SSDs) is increasing at a breathtaking pace. McKinsey estimates that the enterprise SSD market could clock 35% annual growth between 2024 and 2030 in a base-case scenario.
At the same time, adding new NAND flash capacity reportedly takes 24 to 36 months, suggesting that new manufacturing facilities will only start volume production in 2028 or 2029. This should ensure that the strong pricing environment fueling incredible growth for Sandisk in the past year isn't going anywhere.
The company's revenue shot up by 175% in the recently concluded fiscal year 2026 (which ended on July 3) to $20.25 billion. Meanwhile, its adjusted earnings per share (EPS) jumped to $70.88 from $2.99 in the preceding year. Importantly, analysts expect Sandisk's earnings to triple in fiscal 2027, followed by another 20%-plus increase in fiscal 2028.
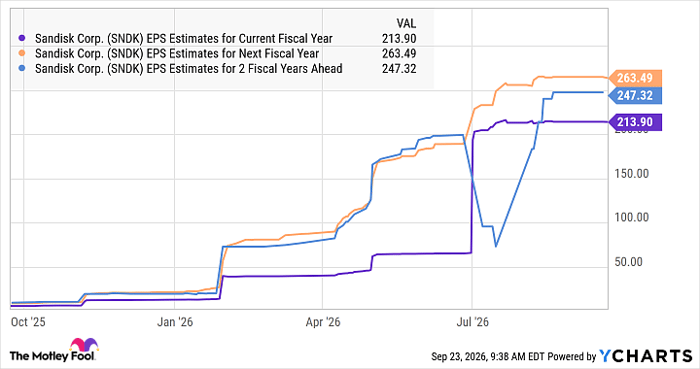
SNDK EPS Estimates for Current Fiscal Year data by YCharts
However, as the chart above indicates, Sandisk's earnings could drop in fiscal 2029. But that's unlikely to be the case amid the strong growth in AI infrastructure investments and the need for enterprise flash storage, as discussed earlier in the article.
Sandisk's long-term forecast points to more gains
Sandisk noted in its investor day presentation last month that its revenue growth rate could range in the mid-to-high teens between fiscal 2028 and fiscal 2030. Also, the company sees its non-GAAP operating margin at approximately 75% over this period, a significant improvement from the adjusted operating margin of 63% in fiscal 2026.
The combination of higher margins and double-digit revenue growth should enable Sandisk to outperform the market's expectations and clock robust earnings growth through fiscal 2030. Assuming Sandisk's earnings increase by even 15% a year in fiscal 2029 and 2030, its EPS could reach $350 at the end of the forecast period (using fiscal 2028's projected earnings per share of $263.49 as the base).
If Sandisk trades at even 10 times earnings at that time, less than half its trailing earnings multiple of 24, its stock price will reach $3,500. That's 85% higher than Sandisk's stock price right now. So, a $500 investment in this AI stock could be worth more than $900 in four years, indicating that it isn't too late for investors to buy it.
Should you buy stock in Sandisk right now?
Before you buy stock in Sandisk, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Sandisk wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $386,781!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,379,943!*
Now, it’s worth noting Stock Advisor’s total average return is 936% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 25, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Western Digital. The Motley Fool recommends Gartner. The Motley Fool has a disclosure policy.
Recommended Articles


