


Is Cintas a Buy After Its Latest Earnings Report?
Key Points
First-quarter revenue grew organically, driven primarily by volume growth.
Gross margins expanded across segments as management continues to push for numerous productivity gains.
Investors may be underestimating the workday supplier's ability to cross-sell services to existing customers.
- These 10 stocks could mint the next wave of millionaires ›
Cintas Corporation's (NASDAQ:CTAS) first-quarter earnings yesterday weren't bad by any stretch of one's imagination. The most important things I'd look for in an earnings result were there. The big question, however, is whether the stock price already reflects all of this good news.
Or, better still, does the business have enough growth runway that isn't yet reflected in the stock price?
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The workday supply specialist's shares fell nearly 3.5% in yesterday's trading session following the earnings announcement, but have mostly reversed those losses today, trading up 3.2% by 1:20 p.m.

Image source: The Motley Fool.
Volume, instead of price, drove growth
Revenue for the first quarter of fiscal 2027 (ended Aug. 31, 2026) came in at $3.01 billion, a solid 10.9% increase year over year. Organic revenue growth (barring acquisitions) stood at 8.9%. Earnings per share (EPS) grew nearly 16%, clocking in at $1.39 while also beating estimates.
Cintas's primary business, its uniform rental and facility services, grew 8% organically and accounted for about 76% of total revenue. But the smaller segments grew as well.
| Segment | Q1 2027 organic yoy revenue growth* |
|---|---|
| Uniform rental and facility | 8.0% |
| First aid and safety | 14.2% |
| Fire protection | 9.2% |
| Uniform direct sale | 9.6% |
Source: Q1 2027 earnings call. *y-o-y: year-over-year
On the earnings call, management emphasized that volume was the primary growth driver, rather than aggressive price increases, despite inflation being up.
Essentially, that's the durable growth the underlying business can deliver. To me, that says something about customer demand. When customers see enough value in outsourcing these supplies to Cintas, it indicates there's still significant room for growth by bringing in businesses that currently handle these needs in-house.
According to management, the total addressable market is between 16 million and 20 million businesses, while the company currently serves about a million of them. That's a massive market with plenty of room to create value.
Margins expanded, driving profitability
Additionally, overall gross margin increased to a record 51.5%, primarily driven by higher profitability in other segments. The first-aid and safety segment, for example, achieved a gross margin of 57.6%.
Management said the improvement in profitability came from a lot of small productivity gains rather than one big transformational project. Again, that means management has many levers, including technology investments and automation that drive efficiency, at its disposal in order to sustain profitability.
Cross-selling is in the early phase
CEO Todd Schneider also highlighted the ability to cross-sell its various services to the same customers, reminding that the company is still early in the phase.
Here's where that's highly useful: First, it means lower costs to acquire new customers, further driving margins, and second, average volume growth from the same customer increases, further cementing the growth runway.
Essentially, having multiple avenues to grow both revenue and profits in a massively untapped addressable market is the best business to have.
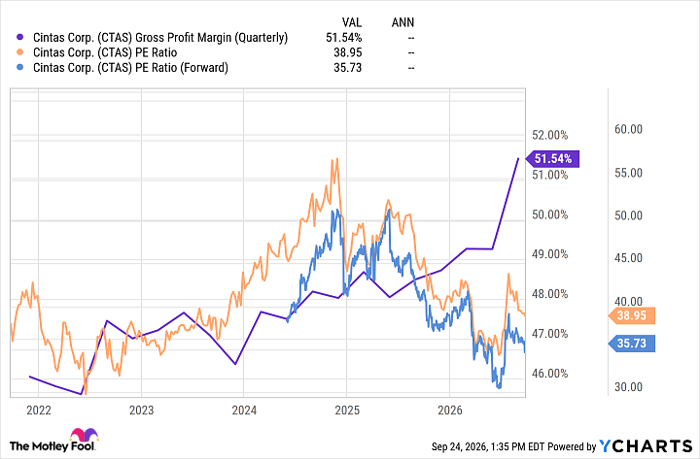
CTAS Gross Profit Margin (Quarterly) data by YCharts.
Is future growth already priced in?
There's little doubt that Cintas remains an excellent business. The real question for investors is whether the stock has enough room for further growth. Shares currently trade at an expensive 40.5 times trailing earnings and 36 times forward earnings.
Can the high single-digit organic growth persist while margins continue to expand, or at least remain stable, with cross-selling services really taking off? From its latest earnings results, I'm inclined to think so.
What makes me bullish about the business is its ability to rely on multiple growth levers and implement numerous productivity initiatives. Additionally, the company isn't racing against time to achieve this growth. I think the market is being conservative in its expectations for the business, and I doubt investors are looking more than two years ahead when pricing this stock. The stock price has stalled for the last 12 months or so, but I'd attribute that to the market waiting for more favorable news than anything else.
The risk is inflation
That said, if inflation continues rising, organic growth may slow to mid-single-digit gains, and the market may assign a lower P/E multiple.
On a conservative basis, if shares fall to a price-to-earnings ratio of 30 over five years while earnings grow at a modest 10% per annum, Cintas stock should still reach $245, implying a 24% upside. A higher growth rate -- or a higher valuation -- will ensure greater upside.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 936%* — a market-crushing outperformance compared to 213% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
See the stocks »
*Stock Advisor returns as of September 24, 2026.
Isac Simon has no position in any of the stocks mentioned. The Motley Fool recommends Cintas. The Motley Fool has a disclosure policy.
Recommended Articles


