


Amgen Stock Forecast: AMGN Reclaims $410 as Pipeline Catalysts Build
TradingKey - Amgen (NASDAQ: AMGN) jumped over $410 on Tuesday and is looking constructive in the short-term. The move upwards was caused by the release of positive topline data from the Phase III study of dazodalibep. Positive news for Amgen's oncology pipeline also came in September from Phase 3 IMDELLTRA data and an FDA-approved monitoring-time update. Dazodalibep will provide upside in Amgen's growth, but the company still needs new products to offset the shrinking growth of some of Amgen's older drugs.
Dazodalibep Adds a Potential New Growth Driver
On September 22, AMGN announced that the Phase 3 trial of dazodalibep, OASIZ 301, demonstrated that the study drug met its primary endpoint for the treatment of patients with moderate to severe Systemic Sjogren’s Syndrome.
According to AMGN, patients treated with dazodalibep showed a significant improvement from baseline in disease activity compared to patients in the placebo group at the 48 week time point. AMGN also noted that as of current, the FDA has not approved any drugs to specifically target the symptoms of Sjogren’s Syndrome.
While positive, AMGN also stated that the data released was “top-line only.” As such, the extent of improvement was not disclosed, and, therefore, the potential commercial success of the drug remains speculative. AMGN also is conducting a Phase 3 study of dazodalibep to target the symptoms of Sjogren’s Syndrome, and OASIZ 303 is expected to complete in Q4 2026.
IMDELLTRA Is Building a Broader Oncology Opportunity
Additionally, Amgen had major news on IMDELLTRA in September. On September 8th, the Phase 3 DEllphi-305 study showed positive results for the use of IMDELLTRA with AstraZeneca’s (AZN) anti-PD-L1 drug, Imfinzi, in the first-line maintenance treatment of patients with extensive-stage small cell lung cancer (ES-SCLC) and the results showed a significant improvement in overall survival (OS) when compared to Imfinzi alone. The study also showed that the combination of IMDELLTRA and Imfinzi showed significant improvement in progression-free survival (PFS) and objective response rate (ORR) when compared to Imfinzi alone.
Although the combination of IMDELLTRA and Imfinzi expanded the range of potential patients, the full impact of the study was not disclosed.
The second important announcement for IMDELLTRA was on September 14th, when the U.S. Food and Drug Administration (FDA) amended the IMDELLTRA label to allow a reduction in the recommended monitoring time for the first two doses to 6 to 8 hours from the original time of 22 to 24 hours.
Newer Products Are Offsetting Legacy Declines
In the second quarter of 2026, Amgen reported total revenues of $10.1 billion, which represented a 10% increase from the same period last year.
The positive news on newer products continues to offset the negative news on older products. The PCSK9 inhibitor, Repatha, reported revenues of $953 million, an increase of 37% from the same period last year. Revenues for the anti-sclerostin monoclonal antibody EVENITY, increased by 38% to $714 million. IMDELLTRA, a DLL3-targeting BiTE immunotherapy reported revenues of $288 million and TEZSPIRE, a monoclonal antibody that targets thymic stromal lymphopoietin (TSLP) reported revenues of $486 million, an increase of 42% from the same period last year.
Due to the introduction of biosimilars, the monoclonal antibodies PROLIA and XGEVA reported revenues of $759 million and $352 million respectively, a decrease of 32% and 34% from the same period last year.
Cash Flow Is Strong, but Debt Limits Flexibility
EPS and adjusted EPS both increased year over year. The former increased from $2.65 to $4.37, while the latter increased from $6.02 to $6.29.
Free cash flow improved to $3.5 billion from $1.9 billion. Improvement was aided by the final repatriation tax payment made in Q2 2025 and current-period business performance, partially offset by working-capital timing.
Cash and cash equivalents were $14.0 billion, while long-term and short-term debt was $57.3 billion.
Management of the cash flow has allowed Amgen to reduce the impact of debt on the flexibility of the business.
Management's 2026 Guidance Remains Solid
Annual revenue is expected to be between $38.2 and $39.4 billion. Adjusted EPS is expected to be between $22.30 and $23.50.
Amgen has a well-rounded and robust pipeline covering multiple product lines and therapeutic areas including oncology, inflammation and rare diseases to name a few.
The more pertinent question is whether the company will be able to offset losses from underperforming and/or eroding products. Products including Repatha, EVENITY, and TEZSPIRE are pivotal in accomplishing this.
Olpasiran Now Faces a Higher Evidence Bar
A different development in September also impacted Amgen’s cardiovascular portfolio. Novartis announced that their Lp(a) lowering drug, pelacarsen, did not reach its primary endpoint in its Phase 3 study. While pelacarsen and olpasiran are in different drug families and Phase 3 trials, Novartis’ result raised the bar for the type of evidence Amgen will need to demonstrate to achieve a positive cardiovascular outcome with olpasiran. As previously noted, lowering Lp(a) levels is just the first step and may not be sufficient to demonstrate an improvement in cardiovascular health.
MariTide Remains a Major Optionality Driver
Amgen is advancing MariTide through multiple Phase 3 studies and the drug has the potential to become commercially significant and has the potential to alter the treatment of obesity and associated metabolic conditions. Although impressive early clinical data increases the likelihood of a successful MariTide program, I will view the outcome as positive but uncertain research and development, and therefore, not earnings impacting, until and unless the program demonstrates positive Phase 3 clinical trial results.
Amgen Technical Analysis: AMGN Reclaims $410 as Bulls Target $418.73
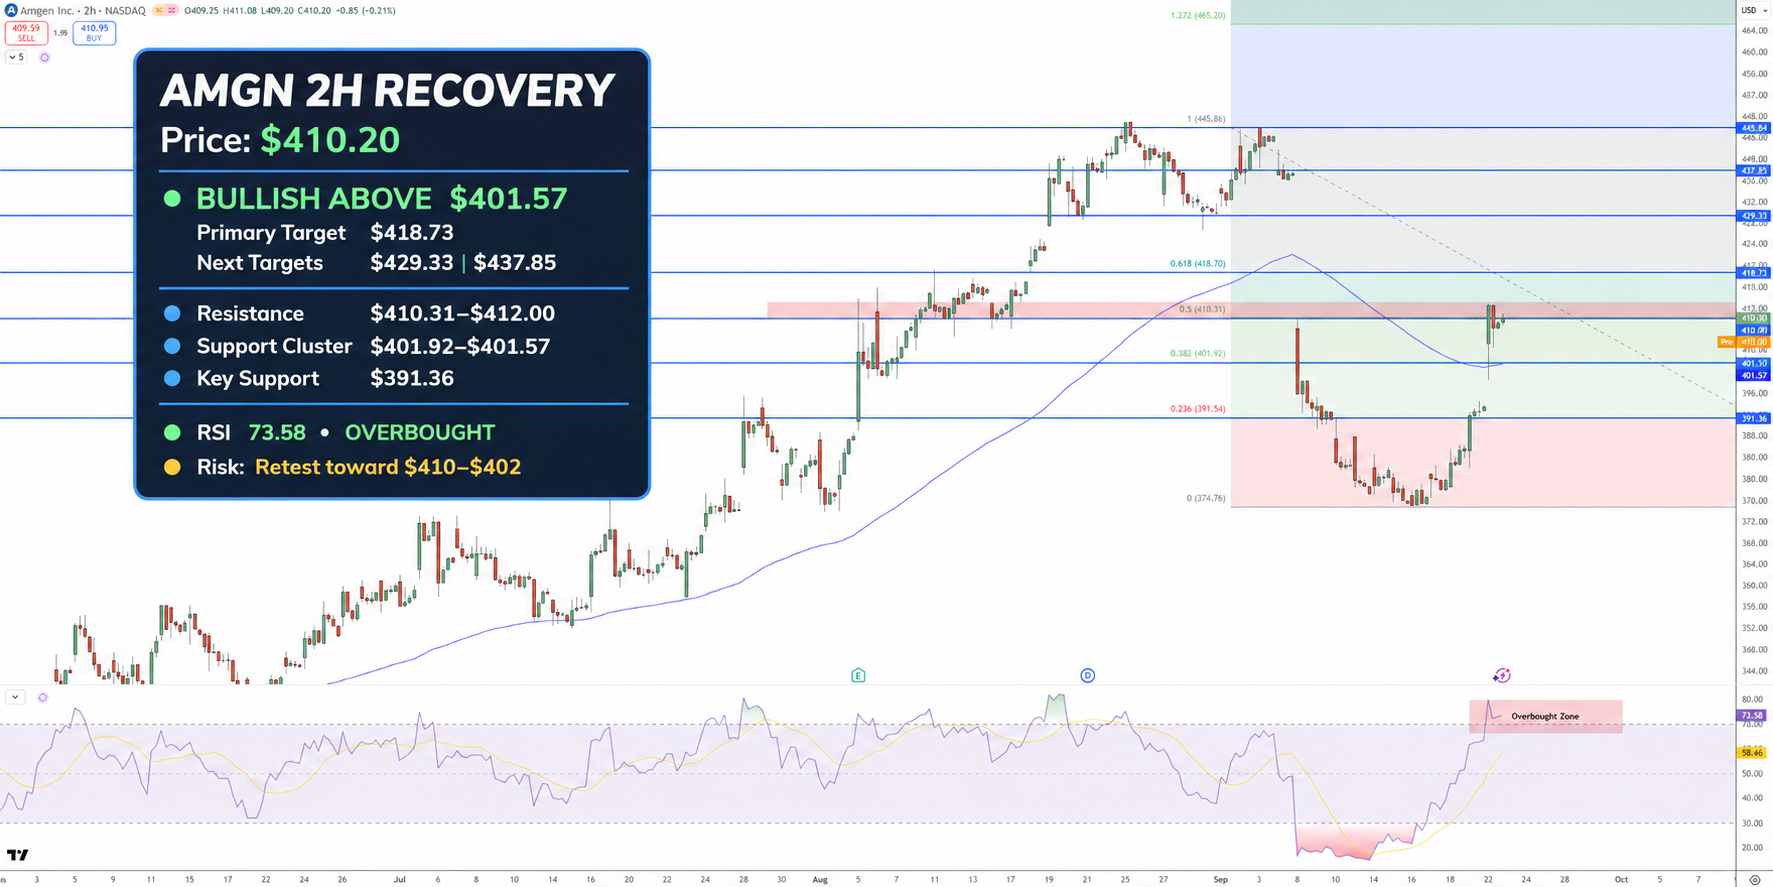
Amgen's stock price closed Tuesday at $410.24, within range of the chart price of $410.20. Amgen's stock chart is bullish over the two hour time frame after a bounce from the $374.76 swing bottom. I like the bounce above the $391.36 Fibonacci level and the moving average at $401.57, as well as the intraday break above the 50% retracement level at $410.31.
Amgen Stock Price Chart - Source: Tradingview
RSI is at 74, and the signal line is at 58. With RSI this high, it's possible Amgen stock may pull back, but it's likely to test the 61.8% Fibonacci level at $418.70 and $418.73. A move above $418.73 may project further upside to the $429.33 and $437.85 levels. If Amgen stock pulls back, I'd look for support in the $401.57 to $401.92 area, with further support at $391.36. In my view, Amgen stock is bullish as long as it trades above $401.57, and the target price is $418.73.
Why is Amgen stock in focus now?
Amgen is currently looking good, based on upcoming potential developments in autoimmune and oncology drugs. Sjögren’s disease is an autoimmune disorder and Dazodalibep’s Phase 3 results are positive. IMDELLTRA also produced positive Phase 3 first-line maintenance results in extensive-stage small-cell lung cancer, while the FDA approved shorter monitoring time for the first two doses.
What level confirms a stronger AMGN recovery?
A bullish continuation beyond $418.73, for a two-hour timeframe, would increase confidence in a move toward the next target at $429.33. A failure to rise and close above $418.73 would keep the focus on the $401.57 area.
Bottom Line
Amgen lost key U.S. RANKL antibody patent protection for Prolia and XGEVA in February 2025, with select European protection expiring in November 2025. Biosimilar competition is already negatively impacting revenue. Amgen will also have negative impacts due to the loss of patent protection for other drugs. Positive results from recent clinical trials should help offset some of the negative impacts. Other drugs like EVENITY, and IMDELLTRA will help growth. The pipeline is also positive with dazodalibep and MariTide.
Amgen will also be negatively impacted by the loss of patent protection for other drugs. The current uptrend should continue as long as the price is above $401.57. A move above $418.73 would also be positive for the stock. A close below $401.57 would not be positive.
Recommended Articles


