


Anthropic Is Targeting a Valuation of Over $2 Trillion in Its IPO. Here's Why Smart Investors Will Wait Before Buying
Key Points
Anthropic's revenue is growing rapidly, and it plans to raise $100 billion in an IPO.
It is unclear how profitable the business is today.
IPO stocks statistically underperform the indexes in subsequent years.
- These 10 stocks could mint the next wave of millionaires ›
Space Exploration Technologies smashed IPO fundraising records in June when it raised $85.7 billion at a $1.77 trillion valuation. In a few months, Anthropic is looking to top this figure.
According to reports from various financial media sources, the rapidly growing artificial intelligence (AI) lab Anthropic wants to IPO at a $2 trillion valuation and raise a record $100 billion in the process. For context, this is a larger figure than the entire IPO proceeds marketwide in every year except 2020 and 2021.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
A lot of investors are going to want a piece of the shiny AI prize. Smart investors will show restraint. Here's why it will be a better move to hold off on buying Anthropic stock at the IPO, according to history.
Image source: Getty Images.
Rapid growth and massive expectations
Because its coding tools and AI chatbot are growing at a breakneck pace, Anthropic may be the fastest-growing large-cap company in history. Its annual revenue run rate was $100 million in 2023, $1 billion in 2024, and $10 billion in 2025, according to third-party sourcing. By the time the S-1 IPO prospectus is released, we will know exactly what Anthropic's financials looked like in the last few years.
In Q2 2026, Anthropic's revenue hit a blistering $11.6 billion, which was up more than tenfold from the same period a year ago. If this growth continues through the rest of 2026, annualized revenue may reach $100 billion by year-end.
This is what the IPO bankers and insiders are betting on to fulfill this $2 trillion valuation. A company that shows it is just a few years away from hundreds of billions in revenue could well be worth that much, despite it being founded in 2022.
What if growth slows?
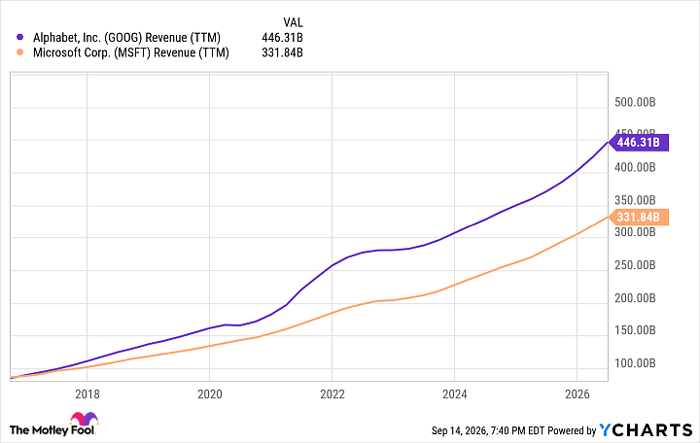
The big risk for Anthropic at a $2 trillion valuation is slowing revenue growth. Investors will be hoping that Anthropic's revenue grows at a similar clip in the years ahead, bringing it in line with the large-cap technology players like Alphabet or Microsoft. These companies have revenue figures in the hundreds of billions and are given market capitalizations in the trillions.
The problem is that these are companies with many different business lines, whereas Anthropic offers only a single product today: AI coding tools. It's a product that has seen widespread use so far, but it is a tall task to expect the world to spend hundreds of billions of dollars a year on a single software tool.
It is also unclear how much cash Anthropic is burning right now, or whether it is truly profitable. The company claims it is profitable on an adjusted basis, but this is just a sheen that management teams try to put on their financial statements to make them look more appealing to investors. The truth will be revealed in the audited financials from the S-1.
Data by YCharts.
Why smart investors will wait to buy Anthropic stock
What investors are actually buying will be revealed in the upcoming S-1 filing. However, statistically, we already know that Anthropic is likely to underperform the market after its first day of trading.
Why? Because we have data on IPO stocks going back decades. On average, IPO stocks underperform the benchmark indexes over the subsequent three years, a pattern attributable to high expectations going into the listing and to insiders selling shares once their lockup period ends. With Anthropic, there will be hundreds of billions of dollars in insider stakes looking to cash out once the company goes public.
A valuation of $2 trillion would make Anthropic the seventh-largest business in the world by market cap. On that figure alone, the expectations may be too high to fulfill.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 938%* — a market-crushing outperformance compared to 211% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
See the stocks »
*Stock Advisor returns as of September 17, 2026.
Brett Schafer has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet and Microsoft. The Motley Fool has a disclosure policy.
Recommended Articles


