


Is 2027 the Turnaround Year for These 4 EV and Air Taxi Stocks?
Key Points
Rivian is seeing better-than-expected sales of its electric R2 SUV, but the true test will be if its affordable Standard version takes off.
Lucid has struggled with profitability and needs to introduce a more affordable vehicle next year.
Archer and Joby are both awaiting FAA type certification for their air-taxi aircraft designs.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
2026 has been a rough year for electric vehicle stocks. That's regardless of whether those vehicles are on the ground or in the air (or, in the case of Tesla's newly unveiled Roadster, maybe both).
Even Tesla's shares haven't been immune to the Wall Street sell-off. They've dropped 18.1% so far this year. But that's nothing compared to the movement of four other electric vehicle makers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Electric car manufacturers Rivian Automotive (NASDAQ: RIVN) and Lucid Group (NASDAQ: LCID) are down 37.2% and 70.7%, respectively, this year. Meanwhile, electric vertical takeoff and landing (eVTOL) air taxi designers Archer Aviation (NYSE: ACHR) and Joby Aviation (NYSE: JOBY) are down 46% and 65.3%, respectively, over the same time frame.
But if 2026 continues to be a bust for all four of these companies, could 2027 be a turnaround year for them? Here's what Rivian, Lucid, Archer, and Joby would each need to do to turn their fortunes around in 2027, and -- more importantly -- the likelihood that they'll be able to pull it off.

Image source: Getty Images.
Rivian: The biggest of the bunch
Of these four companies, Rivian is by far the largest. Even after its 2026 share price slide, the company sports a $16.9 billion market cap. The other three companies combined have a market cap of only $8.8 billion.
"More money, more problems" doesn't apply to start-ups in the automotive industry. Deeper pockets allow a manufacturer like Rivian to invest in manufacturing infrastructure and potentially scale up production to meet demand for large orders, like the electric delivery vans Rivian has provided to its partner Amazon.
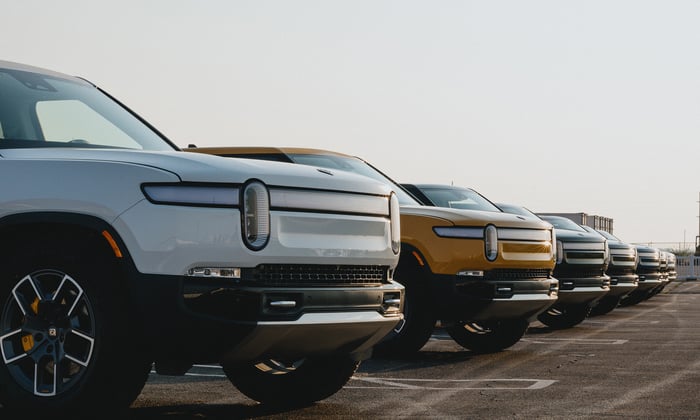
Image source: Rivian Automotive.
Rivian's latest product, the electric R2 SUV, currently fills a surprisingly empty niche in the U.S. EV market: mid-priced non-crossover SUVs. The currently available Performance trim is beating sales projections at its $57,990 price point, and expectations are high for the Standard trim, which is expected to debut in 2027 at a $44,990 starting price.
Scaling up production when your company isn't yet profitable requires resources, and in July, Rivian announced a capital raise of 75 million shares, which caused the stock to fall 18%. Investors may have to weather similar volatility as Rivian enters the resource-intensive preproduction phase for the Standard R2.
That Standard R2 launch could make or break Rivian when it occurs in 2027. Until then, investors should consider Rivian to be a high-risk bet on an uncertain outcome.
Lucid: Down for the count
It's hard to believe, looking at their share prices now, but less than four years ago, Lucid's market cap was higher than Rivian's.
What happened in the interim? It's more a question of what hasn't happened: profitability.
Neither Rivian nor Lucid is profitable, but Rivian did generate a gross profit in 2025, meaning it's at least selling its vehicles for more money than it costs to produce them. But even though Lucid is targeting the high-end market with its luxury Air sedan and Gravity SUV, those higher price points aren't yet covering production costs.
Lucid had planned to roll out a lower-cost model this year, but that's now been postponed to late 2027. If Lucid misses that deadline, or pushes it back again without having taken significant steps toward profitability, it might permanently miss its chance. At this point, Lucid looks like a highly speculative turnaround bet.
Archer and Joby: Waiting for the FAA
Although there are more than a few differences between Archer's and Joby's aircraft, business plans, and balance sheets, the biggest looming obstacle for both is the same: U.S. Federal Aviation Administration (FAA) type certification of their eVTOL aircraft designs.
For obvious reasons, the FAA has a lengthy, rigorous certification process for new aircraft designs, involving numerous design reviews, system and equipment tests, and test flights. Both companies are slogging through the multiyear process.

Image source: Archer Aviation.
It's unclear whether Archer, Joby, or one of their rivals will become the first eVTOL maker to be granted FAA certification for its air taxi design. But whichever company it is will almost certainly see its share price jump immediately, while its rivals' stock prices sink until they, too, achieve that coveted approval.
Meanwhile, if the FAA uncovers any serious issues with either design, sending it back to the drawing board, it could be catastrophic for investors.
Considering it's already late October, approval seems unlikely for either company in 2026, so 2027 is the year to watch. Because until that commercial approval is granted, these companies' entire business plans are pure speculation.
Should you buy stock in Joby Aviation right now?
Before you buy stock in Joby Aviation, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Joby Aviation wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $350,756!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,363,905!*
Now, it’s worth noting Stock Advisor’s total average return is 922% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 23, 2026.
John Bromels has positions in Amazon and Tesla. The Motley Fool has positions in and recommends Amazon and Tesla. The Motley Fool has a disclosure policy.
Recommended Articles


