


35.16 Billion Reasons Micron Stock Is Headed to $3,000
Key Points
Micron has been limited in its ability to buy back stock over the last two years.
Beginning Dec. 9, Micron is expected to start deploying excess cash toward additional buybacks.
Micron's $35.16 billion share repurchase authorization is the highest ceiling in the company's history.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Over the last year, Micron Technology (NASDAQ: MU) has delivered one of the most extraordinary rallies in the semiconductor industry. Shares are surging as artificial intelligence (AI) infrastructure spending creates unprecedented demand for memory chips. But despite these gains, investors might still be underestimating Micron's upside potential.
The company just revealed another catalyst after disclosing that its board of directors expanded its stock repurchase authorization to $35.16 billion. The announcement suggests Micron is preparing to return a meaningful portion of its excess cash to shareholders.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's explore why stock buybacks are important and analyze why this could help propel Micron stock toward $3,000.

Image source: Micron Technology.
Micron is about to unleash a historic buyback program
For much of the past two years, Micron's ability to buy back stock has been restricted by stipulations tied to the CHIPS and Science Act. In December 2024, Micron entered into federal funding agreements supporting manufacturing investments in Idaho and New York.
In doing so, Micron's ability to buy back stock was generally limited to offsetting dilution from stock-based compensation and subject to specific government approvals. As a result, Micron did not repurchase any stock during fiscal 2025 and spent just $650 million buying back 2.5 million shares in fiscal 2026.
On Dec. 9, these restrictions are changing. Anticipating this transition, Micron expanded its buyback authorization from approximately $2.16 billion remaining under its previous program to $35.16 billion. This is the largest buyback ceiling in Micron's history.
Image source: Getty Images.
Micron's record profits are turning into heaps of cash
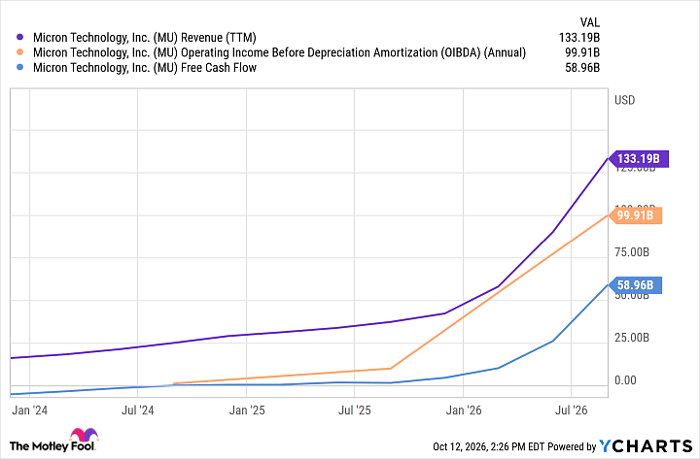
During fiscal 2026, Micron generated $133.2 billion in revenue, representing 256% year-over-year growth. Operating income reached a staggering $99.3 billion, compared with $9.8 billion during fiscal 2025. That represents an operating margin of nearly 75%.
The reason for Micron's astronomical growth is straightforward: Memory prices are skyrocketing as AI infrastructure demand from the hyperscalers overwhelms available supply. Micron's average selling prices increased 180% for DRAM and 200% for NAND during fiscal 2026.
What's even more encouraging is that management expects the constrained memory supply to persist through 2027 and 2028. These conditions should continue to produce enormous cash flow.
During Micron's fiscal fourth quarter alone, operating cash flow was roughly $44 billion. After accounting for capital expenditures (capex), free cash flow reached $33.2 billion. Think about it this way: Micron generated enough free cash flow in one quarter to support nearly the entire newly authorized buyback.
MU Revenue (TTM) data by YCharts
Can Micron reach $3,000 per share?
As of this writing (Oct. 12), Micron stock trades for roughly $1,000 per share, and the company has approximately 1.13 billion shares outstanding. At a share price around $1,000, a $35.16 billion repurchase program could retire approximately 35 million shares. That's roughly 3.1% of outstanding shares.
That alone is not enough to send Micron to $3,000. However, buybacks could become a powerful catalyst for share price appreciation if the company continues to generate record levels of free cash flow and expands its buyback authorizations.
During Micron's September earnings call, CFO Mark Murphy said he expects fiscal first-quarter 2027 free cash flow to be "significantly higher" than the $33.2 billion generated during the fourth quarter. Murphy made it clear that investors should expect to benefit, noting that Micron intends to return 100% of excess cash to investors over time, primarily through stock repurchases. If favorable memory pricing persists, Micron could have the financial flexibility to authorize additional buybacks, further reducing its outstanding share count and boosting earnings per share.
Wall Street expects Micron to generate roughly $176 in earnings during fiscal 2027. At approximately 7 times forward earnings, Micron looks inexpensive relative to many other AI semiconductor stocks. If investors become convinced that Micron's profits are more sustainable than in previous memory cycles, the stock could experience considerable valuation expansion.
A 17x forward P/E multiple on the projected earnings of $176 implies a stock price of $2,992. A modest additional benefit from share repurchases could easily push the share price above $3,000. This represents 202% upside from today's prices.
While buybacks alone won't triple the stock, the combination of Micron's expanding long-term strategic customer agreements, robust pricing power, visibility into sustained cash generation, and management's commitment to buy back stock should result in investors awarding the company a substantially higher earnings multiple over time. For this reason, I see Micron as an attractive AI infrastructure stock to buy and hold.
Should you buy stock in Micron Technology right now?
Before you buy stock in Micron Technology, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Micron Technology wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $379,123!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,408,822!*
Now, it’s worth noting Stock Advisor’s total average return is 950% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 12, 2026.
Adam Spatacco has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


