


May Mobility's SPAC Merger: Is This a Road to Nowhere for Investors?
Key Points
May Mobility is looking to become the first pure-play autonomous ride-hailing investment option.
The autonomous segment of ride-hailing remains in the very early stages.
May Mobility is transitioning to an asset-light model, but that comes with pros and cons for investors.
- 10 stocks we like better than ACP Holdings Acquisition Corp. ›
Investors eager to buy into the futuristic vision of profitable driverless vehicles will get their chance soon. May Mobility is aiming to become the first U.S. publicly listed pure-play option for an autonomous ride-hailing technology company. It is poised to go public through a special purpose acquisition company (SPAC), merging with ACP Holdings Acquisition (NASDAQ: ACGC) that values the combined company at roughly $1.4 billion.
It's expected to operate as May Mobility. trading on the Nasdaq exchange under MAY. But before investors get too excited, let's pump the brakes and take a look at the details.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Opportunity knocks
It's easy for investors to get excited about the opportunity, but many might not be aware of the potential market size or growth prospects. The global robotaxi market is projected to reach about $415 billion by 2035, with the U.S. accounting for a roughly $48 billion slice of that pie. The fleet of U.S. commercial autonomous vehicles (AVs) is projected to expand from only about 4,000 vehicles currently to around 35,000 by 2030 -- or about 8% of the ride-sharing market.
A year ago this month, Bank of America projected that the long-term U.S. total addressable market (TAM) for AV ride-hailing is a trillion-dollar opportunity as companies such as May Mobility aim to replace the drivers that take roughly 70% of every fare. It's also important for investors to realize how early in the game this is: Alphabet's Waymo, with an estimated $350 million in annualized revenue, would represent only about 0.5% of U.S. ride-hailing bookings.
The opportunity is potentially lucrative, albeit still very early in the game. So, what makes May Mobility intriguing?
An asset-light transition
May Mobility is moving to an asset-light model. At the company's initial U.S. ride-hailing launch site, it estimates the costs for the safety driver; vehicles (financing, depreciation, insurance, maintenance); site operations (fuel/charging, depot operations, and staff); and remote vehicle supervisors, software maintenance, and field engineers. In this asset-heavy scenario, May Mobility's projections put its annual revenue per vehicle between $130,000 to $150,000, as it keeps all the revenue. But because it also incurs all the costs, it checks in with a negative gross margin per vehicle with a safety driver.
Under its asset-light model, which includes removing the safety driver, May Mobility transfers the vehicle costs as well as the site operating costs to a fleet operating partner, although it will still incur the costs for remote supervisors, field engineers, and software maintenance.
This scenario would come with a larger fleet size thanks to a fleet-operator partner, and lower revenue ($50,000 to $72,000 per vehicle) as it splits the sales with that partner. But it checks in with a gross margin per vehicle between $35,000 to $50,000 annually because it would push off significant costs and could scale up more quickly without needing to purchase and own the fleet.
There's further upside with management targeting a 50% reduction in its bill of materials (BOM) by the end of 2028. That's from cost savings realized through computing and sensors with next-generation chip alternatives and as lidar/radar/camera markets scale up and mature.
May Mobility also expects to reduce its BOM through cost reductions in hardware components and integration when its software could be installed by the original equipment manufacturer (with Toyota as a partner for AV-ready vehicle platforms at scale) rather than installing it in vehicles afterwards. Over the long term without drivers, management is targeting gross margins of about 70%, and margins under earnings before interest and taxes around 30%.
How going public helps
When the SPAC deal and merger closes, it could provide May Mobility with up to $337 million in funding. Investors can look at the economics and do the math: In 2025, the company generated roughly $10 million in revenue with a 27% gross margin, while burning $93 million in cash. The SPAC funds should enable it to strengthen its balance sheet and liquidity, finance added research and development, invest in the supply chain to reduce costs, and launch new in markets without drivers. However, without a major cash pile, the cash burn could erode its liquidity rather quickly.
What it all means
It's an exciting time in an automotive industry that's poised to evolve rapidly over the next decade. However, investors must understand that this is an exceptionally high-risk investment currently. May Mobility's 27% gross margin is an encouraging beginning, but the cash burn is significant and will only increase in the near term. It will rely heavily on the $337 million of fresh capital from its public debut, and that could erode rapidly.
Investors also have to consider that despite being in the early innings, there are some heavyweights accelerating forward, including market leader Waymo and Tesla's slow but steady progress with its Cybercab business.
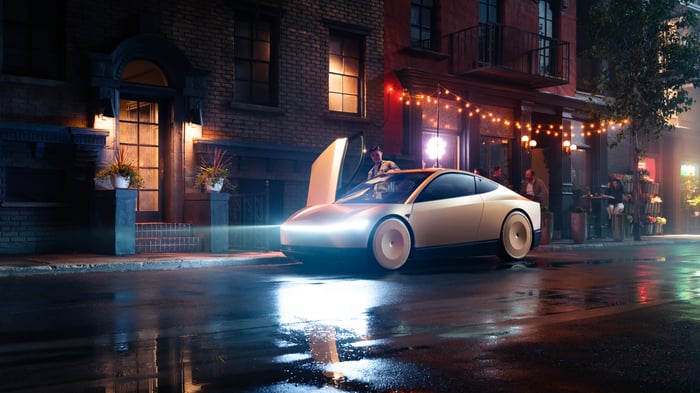
Tesla's Cybercab. Image source: Tesla.
May Mobility is intriguing, but this only scratches the surface. Potential shareholders must read through the investor presentation, available here, and recognize that this could end in a total loss. For now, this should be a company that most retail investors watch curiously from the sidelines, especially as this debut tests investor demand for a pure-play AV ride-hailing company.
Should you buy stock in ACP Holdings Acquisition Corp. right now?
Before you buy stock in ACP Holdings Acquisition Corp., consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and ACP Holdings Acquisition Corp. wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $395,625!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,397,147!*
Now, it’s worth noting Stock Advisor’s total average return is 951% — a market-crushing outperformance compared to 214% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 22, 2026.
Bank of America is an advertising partner of Motley Fool Money. Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet and Tesla. The Motley Fool has a disclosure policy.
Recommended Articles


