

Tesla's Free Cash Flow Went Negative. It Still Has a $43.5 Billion Cash Cushion.
Key Points
Tesla's free cash flow is negative, but it has a large cash reserve and access to resources.
Future growth depends on robotaxis in the near term and later on Optimus.
- These 10 stocks could mint the next wave of millionaires ›
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Tesla's (NASDAQ: TSLA) free cash flow (FCF) turned negative in the second quarter of this year, and, according to the consensus estimate from analysts surveyed by market intelligence company Visible Alpha, the company will continue to burn cash until 2029. The company posted an FCF loss of $1.1 billion versus a gain of $6.2 billion a year ago as it invests heavily in self-driving cars, artificial intelligence, and its Optimus robot initiative. While Tesla has significant liquidity to fund its substantial investments, does it provide enough of a buffer to give investors confidence?
Tesla's capital spending plans
The short answer is "yes, provided you believe in the robotaxi rollout." But that's a somewhat limited argument because if you don't believe in the robotaxi rollout, which Tesla's dedicated robotaxi, Cybercab, will ultimately lead, then it makes no sense to buy a stock trading at 205 times estimated 2026 earnings.
However, the key investor question about cash flow and resources is the timing of cash flows from robotaxis. With $43.5 billion in cash and equivalents at the end of the second quarter, and after deducting $9.3 billion in debt and finance leases, Tesla still has a net cash cushion of $34.2 billion, which should be sufficient to ensure the company has ample liquidity to handle some delays.
Tesla's cash-flow profile
Tesla's spending include building out a vertical supply chain that includes chips, batteries, a lithium refinery, and production lines to fund its automotive, AI, and robotics programs. In its second-quarter earnings report, Tesla announced it spent $3.3 billion on capital expenditures.
Tesla's net cash position should be sufficient to support the business until it generates free cash flow again in 2029, after which its net cash position is forecast to improve significantly as earnings and cash flow roll in from robotaxis and Optimus.
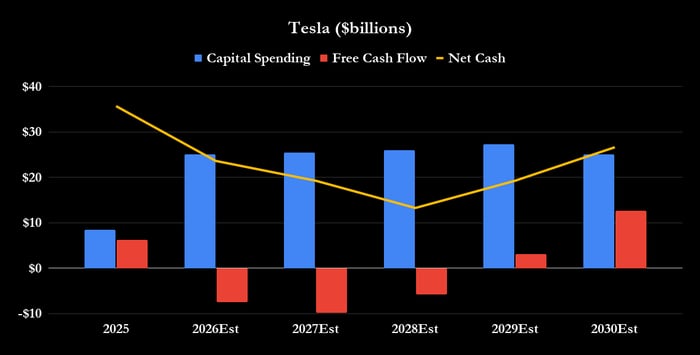
Data source: Visible Alpha. Chart by the author.
Wall Street estimates can be overly optimistic
Investors always need to take forecasts for what they are: guesses. The reality could prove significantly different; the robotaxi rollout, for example, hasn't progressed as quickly as CEO Elon Musk thought it would. In addition, the Cybercab hardware continues to face regulatory hurdles, as well as supply chain and production challenges. Meanwhile, Tesla needs to validate and release its next major upgrade of full self-driving (FSD) software, v15, that will ultimately run Cybercab.
In short, the assumptions made by analysts are highly uncertain. For example, the Visible Alpha consensus median estimate calls for Tesla to generate $25 billion in robotaxi revenue (primarily from the mobility service itself) in 2030, representing 13% of its sales, up from $1 billion in 2027.
Given the slow pace of the rollout, investors shouldn't be surprised if Tesla misses these estimates.
Image source: The Motley Fool.
Why it may not matter
That said, the buffer created by Tesla's current cash levels and future operating cash flow isn't the only reason investors feel confident that Tesla will have sufficient liquidity to continue pursuing its growth aspirations, even if Cybercab (robotaxi) revenue is delayed. If Tesla can demonstrate that it's definitely on track to generate recurring revenue from robotaxis, then it will be able to borrow money backed by that revenue.
Indeed, CFO Vaibhav Taneja noted in January that the company had "over $44 billion of cash and investments" on its books and would use its own internal resources, especially when we look at the Robotaxi fleet, because any time you have a consistent stream of cash flow, you can go and get money from the banks. And we have had conversations with banks about it."If you believe Cybercab (robotaxi) will work, even if it's delayed, there's good reason to believe Tesla's current cash balance, operational cash flow generation, and ability to borrow will ensure it has no trouble funding its growth initiatives.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Nvidia: if you invested $1,000 when we doubled down in 2009, you’d have $577,856!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $64,119!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $387,158!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, available when you join Stock Advisor, and there may not be another chance like this anytime soon.
See the 3 stocks »
*Stock Advisor returns as of September 21, 2026.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Tesla. The Motley Fool has a disclosure policy.
Recommended Articles


