


If the Fed's Next Move Is a Rate Hike, Here's How a Long-Term Portfolio Should (and Shouldn't) Change
Key Points
The market’s counting on at least a quarter-point increase in interest rates next month.
While higher rates are meant to cool inflation by limiting economic growth, this cause-effect relationship is far from etched in stone.
While there are some proven steps you can take to protect your portfolio, remember that no two scenarios or situations are ever exactly the same.
- 10 stocks we like better than S&P 500 Index ›
If there was any lingering hope the Federal Reserve would be lowering rather than raising interest rates in the foreseeable future, it was just wiped away. Although the Bureau of Labor Statistics didn't publish an annualized inflation figure for this October due to last October's government shutdown, Tuesday's look at the month-to-month data confirms the United States' effective annualized rate of inflation still stands in the ballpark of 3%. That's not catastrophic, but it's certainly high enough to cause concern. The cost of borrowing money is elevated, for example, ultimately posing a threat to corporate profits. It's understandable if you're worried about your investment portfolio.
Just don't overreact to the rhetoric. While it's a backdrop you'll want to remain aware of, December's likely rate hike meant to curb these continued price increases isn't the tripwire it's being described to be.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Don't try to predict the unpredictable
Don't misunderstand. High and/or rising interest rates are somewhat correlated with an underperforming stock market. There's not an unreasonable basis for concern.
This correlation, however, isn't a particularly strong one. There are plenty of instances in which an inflationary environment that spurred rate hikes doesn't actually stymie the market, as in 2017 through 2019. And while the market eventually suffered a meltdown in 2008 under an overhang of high interest rates, the S&P 500 (SNPINDEX: ^GSPC) rallied between 2005 and 2008 despite a steady pace of interest rate hikes throughout that period. High rates in the latter half of the 1990s weren't a problem for stocks either.
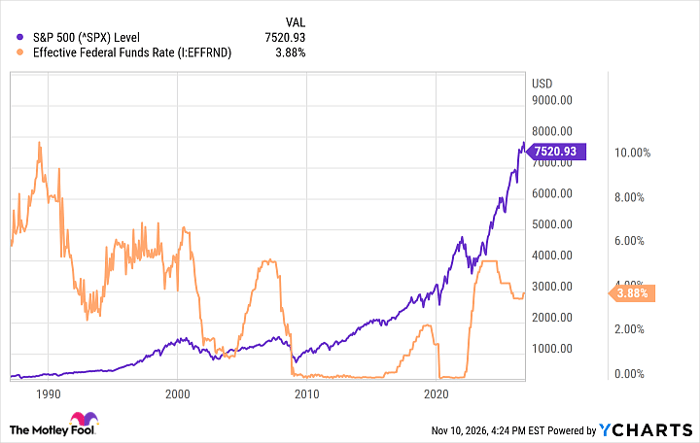
^SPX data by YCharts
Perhaps the more pertinent takeaway about any historical correlation between stocks and interest rates, however, is the sheer unpredictability of interest rate changes. If there is a relationship between the Fed Funds Rate and the direction of equity prices, there's no discernible way to determine when either or both will reverse course. This poses the biggest risk that the matter will not be in the market when the economy finds itself back on firmer footing. The beginning of recoveries is often when the market makes the biggest gains.
In other words, knowing that you can't possibly know what you'd like to know, your best course of action is standing pat with quality holdings -- even if it means you know your stocks are due to suffer some degree of setback.
In this vein, for what it's worth, although the CME FedWatch data indicates traders are betting there's an 88% chance of a quarter-point increase in the federal funds rate in early December (and a 12% chance for a 50-basis-point rate hike), The Federal Reserve's Open Market Committee has also recently suggested the rate will also move at least a little lower at some point in the year ahead.
With all of that being said, although the possibility of rising interest rates in the near future doesn't mean you should get out of the market altogether -- or avoid getting in -- you might want to reallocate your portfolio in a way that's better-suited for such an environment.
Prepping for higher rates
None of these general rules for high and/or rising interest rates are etched in stone; there are always exceptions. Broadly speaking, though, there are four key strategic themes to consider if rates remain at high levels for a while.
1. Add value, subtract growth
In general, much of the growth of many growth companies is ultimately driven by borrowed money. If the cost of this funding increases or there's more risk to lenders, this growth potential is dialed back.
Image source: Getty Images.
Plenty of value stocks are also dependent on debt, to be clear. This isn't a changing dynamic for these underlying companies, though, and unlike growth stocks, value stocks' price/earnings ratios don't expand as much when loans are cheap, and the economy is humming, only to see these earnings multiples compress when borrowing gets expensive again and the economy weakens.
2. Avoid highly leveraged companies and sectors
There may be exceptions to the value-versus-growth dynamic in a rising rate environment, however. It's possible that some growth names don't depend on debt at all to drive growth, just as it's possible a more typical value name that's already heavily indebted and operating on paper-thin profit margins might still struggle in such an environment.
3. Own companies with real pricing power and products and services always in demand
It's possible, of course, that a company's balance sheet and operating costs remain entirely unaffected by higher interest rates. If an organization offers a service or product that's always in demand at any price regardless of the economic backdrop (think utilities and grocery stores), that outfit could conceivably shrug off any upcoming interest rate increases.
4. Understand how interest rate increases are impacting the economy in this particular cycle
Finally -- and perhaps most importantly -- remember that every situation is always at least a little bit different than any other seemingly similar one.
Take banks as an example. Banks' stocks are typically desirable when interest rates are elevated because higher rates mean more net interest income is earned on the same-sized loan portfolio. The current scenario is measurably different, though. Right now, higher interest rates are keeping would-be borrowers on the sidelines, preventing banks from making all the loans they might otherwise like to make. The Mortgage Bankers Association reports that in the final week of October, mortgage loan applications were down more than 40% from a year earlier and remained near their multiyear low set in the middle of the month.
At the same time, high interest rates continue to strengthen the value of the U.S. dollar. Although this works against U.S. companies that ship goods overseas, it works in favor of those that purchase a great deal of foreign-made products and services. If you look hard enough, you might find a buried treasure benefiting from this dynamic.
Should you buy stock in S&P 500 Index right now?
Before you buy stock in S&P 500 Index, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and S&P 500 Index wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $348,060!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,067,492!*
Now, it’s worth noting Stock Advisor’s total average return is 849% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 12, 2026.
James Brumley has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Recommended Articles


