


Gold closed below $4,000 again — the ETF crowd and central banks stayed, the momentum money left
Spot gold is trading at $3,998.71, up 0.28% on the session but below the $4,000 handle for the second time in two weeks, after Wednesday's close at $3,987.69 and a third consecutive lower daily low — Thursday's trough was $3,968.82.
The obvious explanation writes itself: the 10-year Treasury yield is back at 5.00%, the dollar index printed a fresh yearly high of 102.85, and CME pricing puts an 87% chance on a 25-basis-point hike at the 9 December FOMC.
All of that is true. None of it tells you who actually sold.
The three prices inside $3,999
Gold has three inputs that matter, and this week only two of them moved.
Rates and the dollar did the damage
Rates. The 10-year added about 12 basis points to reach 5.00% after October core CPI held at 0.3% month on month for a third straight month against 0.2% expected. For an asset that pays nothing, the opportunity cost rose in a straight line.
The dollar. The index at 102.85 is the strongest since April 2025. Gold is priced in dollars, so a stronger dollar mechanically lowers the dollar price of gold even with no change in demand.
Positioning. This is the one that explains the violence of the move. CFTC data for the week to 3 November shows managed-money net longs at 324 tonnes, down 3% week on week and the lowest in 21 weeks. Silver net longs collapsed to 2,700 contracts, the lowest since February 2024. Platinum joined palladium in net-short territory for the first time since May 2025.
Goldman Sachs puts a number on the split: roughly 95% of five weeks of selling came from the non-reportable category — the part of the market that is neither hedgers nor reporting speculators. In plain terms, the exit was trend-following and momentum money, not strategic allocation.
The cross-metal confirmation matters here. Silver, platinum and palladium all moved the same way, and the three of them are not bought by central banks. That is not a gold-specific story about reserve managers; it is a systematic reduction of precious-metals exposure by the fastest money in the market.
Who did not sell
The strategic side of the market is still buying.
Central banks purchased 321 tonnes in the third quarter, up 42% year on year and taking the year-to-date total to about 675 tonnes. The People's Bank of China added 25.8 tonnes in October — its 24th consecutive month. Global gold ETF holdings peaked at a record 4,256 tonnes at the end of September after 211 tonnes of third-quarter inflows, and Chinese gold ETFs took in RMB 4.25 billion in the fourth quarter through 10 November.
That is not a market in liquidation. It is a market where the fastest, most leveraged holder left first, and the slowest holder has not moved.
The table that decides the next leg
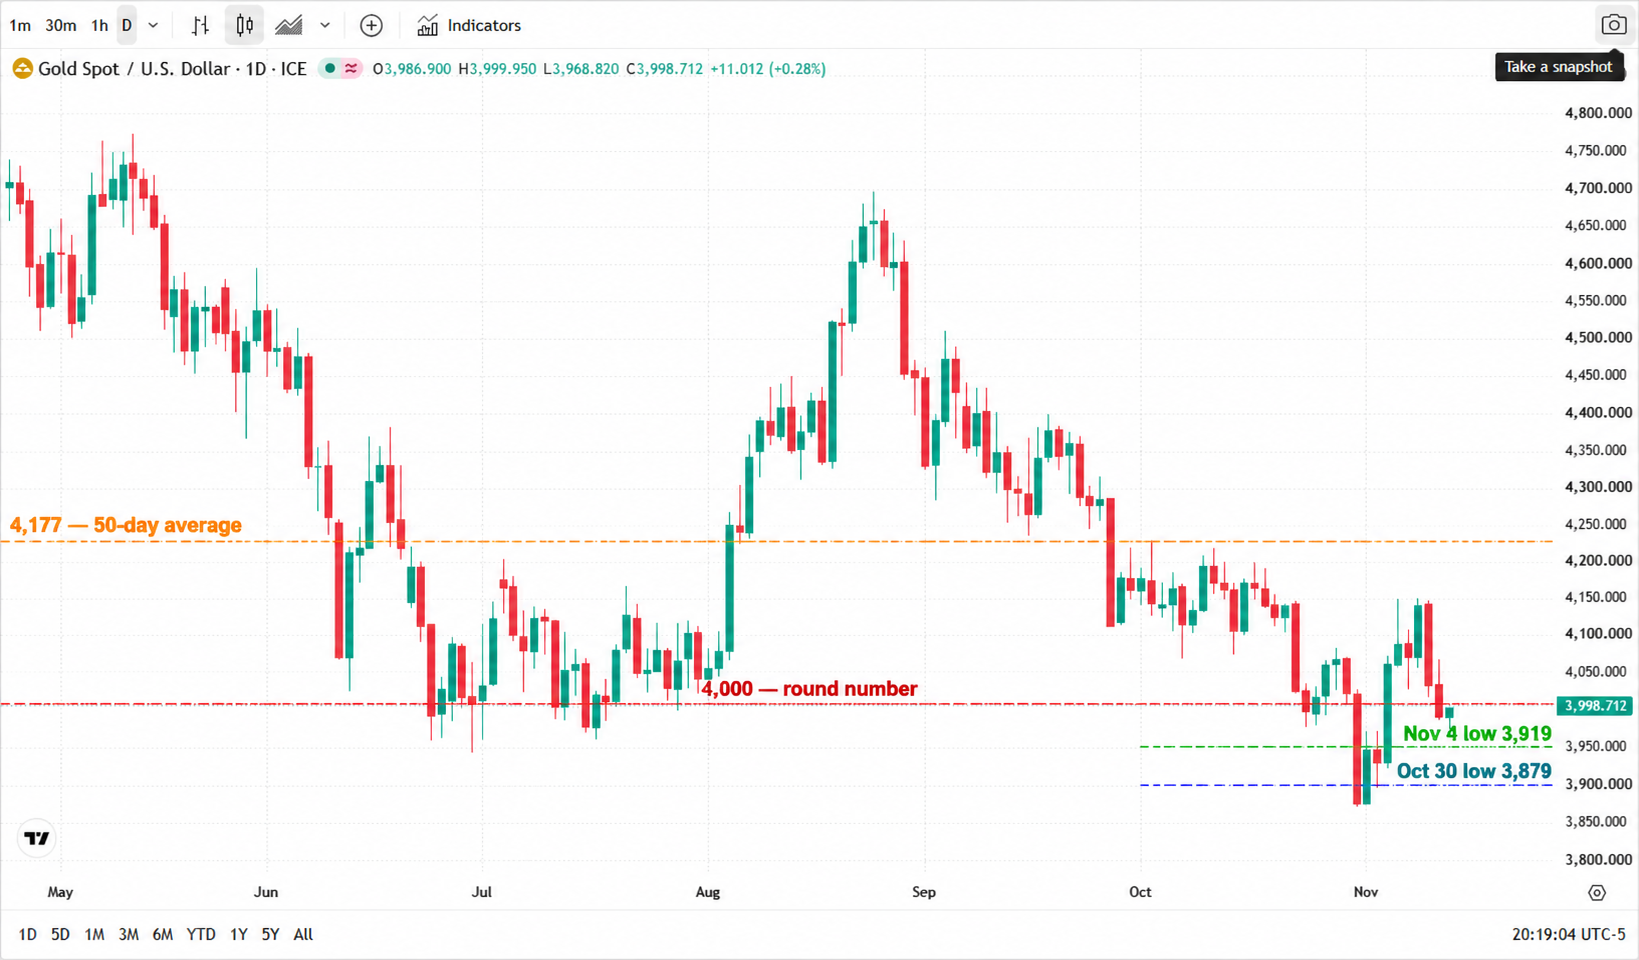
* Chart source: TradingView (XAUUSD daily)
The 50-day has flipped to resistance
Technically, gold is below its 50-day and 100-day averages at 4,177 and 4,200, which now sit overhead as resistance rather than support.
| Trigger | Direction | Level | What it would mean |
|---|---|---|---|
| Daily close back above 4,000 | Up | 4,050 / 4,100 / 4,177 | The break was a positioning flush, not a trend change |
| Hold between 3,919 and 4,000 | Sideways | 3,919 support | Price discovery while the 50-day catches down |
| Break 3,919 (4 November low) | Down | 3,879 (30 October low) | The October low gets retested; Goldman flags 3,850 as next |
| Break 3,879 | Down | Opening of a lower range | The record ETF and central-bank bid is being tested, not just the momentum bid |
Two things would change the read. First, a decisive reclaim of 4,000 that holds for more than a session — that would say the sellers were positioning, not conviction. Second, a break of 3,879 while ETF holdings start shrinking week on week — that would mean the slow money is finally moving, which is a different and much heavier market.
Until one of those happens, the honest description is this: rates did the damage, positioning did the selling, and the strategic bid has not blinked.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


