


Ford's Q3 Sales Slipped. Here's the Silver Lining: Customers Are Splurging on Fancy Trims.
Key Points
Ford's business segments were a bit inconsistent in Q3, but high-margin models were a bright spot.
Ford's combined sales of its Tremor and Platinum trims jumped nearly 60% through September.
The question facing investors is, will this be a durable advantage, or a flash in the pan?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Ford Motor Company (NYSE: F) investors could be forgiven for doing a double take at its latest third-quarter results. While the following figures aren't massive numbers, their different directions are something worth noting.
Third-quarter revenue declined 2% year over year to $49.5 billion, yet adjusted EBIT (earnings before interest and taxes) increased 3% to $2.7 billion. Less revenue, more adjusted profit? The explanation goes beyond the number of vehicles rolled out of dealerships.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ford is selling a richer mix of vehicles while working to bring costs under control. For long-term investors, that combination could be compelling -- as long as Ford proves it's not a one-quarter wonder.
The silver lining
Ford's Explorer lineup brings investors a useful example. Through September, combined sales of its higher-margin Tremor and Platinum trims increased 59.9% year over year. Sales of the more affordable Active and ST-Line trims grew 23.3%.
Those are year-to-date figures, rather than third-quarter-only results, but they help illustrate where a chunk of customers are spending their money within Ford's product lineup. In fact, looking at that customer segment for greater transparency, Ford's off-road lineup accounted for 24% of U.S. vehicle sales through September, up 3.8 percentage points from a year earlier. Management also said F-Series achieved the lowest incentive spending among full-line truck brands during the third quarter.
That's a great scenario for Ford and its investors, as customers are choosing more profitable vehicles without Ford having to throw quite as much cash on the hood to move the metal. Ford also noted it remains on track to reduce warranty and material costs by $1 billion this year, excluding Novelis-related effects and tariffs.
The result is Ford finding ways to improve adjusted earnings without relying on stronger companywide revenue. This is important for long-term investors because the automotive industry is notoriously cyclical, and growing vehicle sales is not always easy if the economy deteriorates or if average new car prices continue to set new records, keeping some consumers on the sidelines.
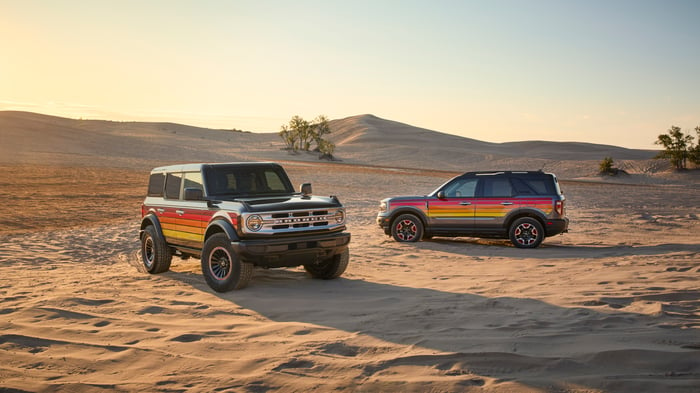
Ford's higher-margin trim success isn't limited to the Explorer. Image source: Ford Motor Company.
Don't celebrate just yet
All that said, there are limits to the good news in the third-quarter results. Reported net income declined from approximately $2.4 billion to $2 billion. Adjusted operating profit tells us something useful, but it isn't the entire earnings picture.
It's fair to point out that, although one quarter doesn't make a trend, Ford's business divisions were a bit inconsistent during the third quarter. Ford Blue and Ford Pro both reported lower quarterly EBIT, while Model e's loss narrowed and Ford Credit's earnings increased.
In other words, premium vehicles and the juicy margins all helped, but they didn't singlehandedly rescue the quarter. Further, one thing that's becoming increasingly worrisome is the affordability crisis in the U.S., with the average price of new vehicles hovering around $50,000.
That's a development that's beginning to price some consumers out of the new-vehicle market, which also puts automakers under pressure to lower costs without removing value to make vehicles more affordable, all without completely eroding margins or weakening demand -- it's a difficult balance facing automakers going forward.
What investors should watch
For investors, what's the takeaway exactly? A richer vehicle mix and better cost control could help Ford earn more from the sales it already generates. Watch whether customers keep choosing those higher-margin trims, whether incentives remain disciplined, and whether warranty improvements keep showing up financially. A weaker economy could test all three, especially given that North America is facing an affordability crisis, with the average price of new cars continuing to rise.
Ford doesn't need every quarter to set a sales record, make progress, or reward investors. But it does need to prove that selling a more profitable mix is a durable advantage, rather than a good quarter wearing a fancy trim badge.
Should you buy stock in Ford Motor Company right now?
Before you buy stock in Ford Motor Company, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Ford Motor Company wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $342,020!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,270,017!*
Now, it’s worth noting Stock Advisor’s total average return is 885% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
Daniel Miller has positions in Ford Motor Company. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Recommended Articles


