


Andy Jassy Just Delivered Magnificent News for Amazon Investors
Key Points
The Amazon Web Services (AWS) cloud platform offers an expanding portfolio of artificial intelligence (AI) services for enterprises.
The platform has delivered six-straight quarters of accelerating revenue growth, but Amazon CEO Andy Jassy says even more momentum is ahead.
Amazon stock looks cheap following its recent 15% correction.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Many artificial intelligence (AI) stocks are in the throes of a sharp correction right now, as investors wrestle with concerns about the sustainability of the data center infrastructure spending boom. As a result, Amazon (NASDAQ: AMZN) stock was down 15% from its August record high as of the market close last Friday.
But the sell-off doesn't really jibe with the strong set of third-quarter operating results the company reported on Oct. 29, particularly from its Amazon Web Services (AWS) cloud computing platform. While discussing the results on a conference call with investors, Amazon chief executive Andy Jassy offered a series of forecasts for AWS that suggests even better times are ahead.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's what he said and why it could fuel a sustained long-term rally in Amazon stock.
Amazon CEO Andy Jassy. Image source: Amazon.com.
Amazon Web Services is on track to become a trillion-dollar business
AWS offers hundreds of solutions to help businesses thrive in the digital age, from simple data storage to complex software development tools. However, its expanding portfolio of AI services is the main driver of the recent acceleration in its revenue growth.
AWS operates data centers all over the world that are filled with advanced AI chips from suppliers like Nvidia, and it rents the computing capacity to enterprise customers for a fee. But Amazon also designed its own chips, like Graviton and Trainium, which it says can offer 30% to 40% better price performance than alternatives. In the third quarter, revenue commitments for these chips increased by a mind-boggling 20 times compared to the year-ago period.
But in addition to hardware, enterprises need access to a broad variety of ready-made foundation models to accelerate the development of AI software applications. AWS Bedrock offers more than 100 of them from leading companies like OpenAI, Anthropic, Mistral AI, and Meta Platforms. During the third quarter, Amazon said Fortune 500 companies ramped up their spending on Bedrock sevenfold compared to the same time last year, with token volume growing by 17 times. Jassy says Bedrock is the fastest growing multibillion-dollar business in AWS's history.
All of this contributed to a record $45.9 billion in AWS revenue in the third quarter, a 39% increase from the year-ago period. It was the sixth-straight quarter in which revenue growth accelerated, emphasizing the platform's incredible momentum.

But all signs point to even faster growth in the future. AWS ended the third quarter with a $578 billion order backlog from customers who were waiting for more data center capacity to come online, which increased by a triple-digit percentage. Moreover, Jassy told investors that AWS could grow its revenue by more than 40% in both 2027 and 2028.
To top things off, he also said AWS could become a trillion-dollar revenue business within the next five to 10 years. For some perspective, its current annual revenue run-rate is $184 billion.
Should investors buy Amazon stock?
Amazon is on track to spend around $220 billion on building data center infrastructure in 2026, and it plans to spend even more in 2027, which will help AWS convert its enormous backlog into revenue. The company can't deduct these costs upfront because data centers have a useful life of several years, so the money it's spending today could impact its earnings in 2027, 2028, 2029, and beyond.
Therefore, it's critical that AWS generates a positive return on all of that spending. Fortunately, Jassy says the data center investments are likely to deliver even higher yields, and even more free cash flow than he could have imagined, which is great news for investors.
Amazon delivered earnings of $12.37 per share over the last four quarters, placing its stock at a price-to-earnings (P/E) ratio of just 19.4, a steep discount to the Nasdaq-100 index which has a P/E of 29.9. In other words, Amazon looks heavily undervalued compared to a group of its big-tech peers.
But there is one issue. Amazon had over $68 billion in non-operating profit during the first three quarters of 2026, mainly from paper gains on its investment in Anthropic, which was completely unrelated to its core businesses. Wall Street analysts think Amazon's earnings will decline to $10.58 per share in 2027 (according to Yahoo! Finance), because Anthropic is unlikely to continue rising in value at the same pace.
Therefore, Amazon looks slightly more expensive on a forward basis, with a P/E of 22.8.
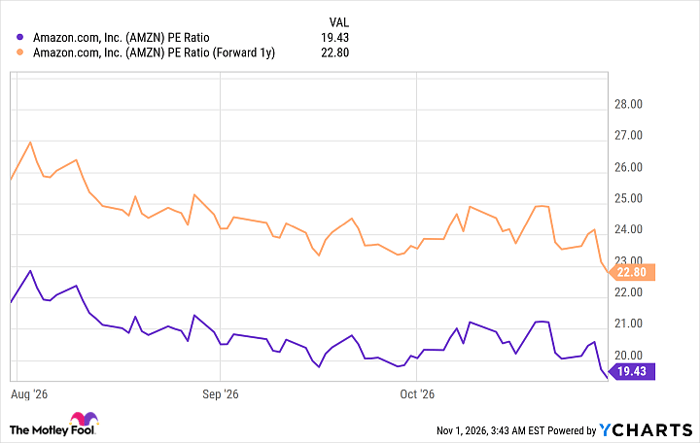
AMZN PE Ratio data by YCharts
But that is still a very attractive valuation in my opinion. Given the blistering growth in AWS and the trillion-dollar revenue opportunity ahead, I think Amazon stock could be a great long-term buy at the current price.
Should you buy stock in Amazon right now?
Before you buy stock in Amazon, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Amazon wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $336,195!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,241,567!*
Now, it’s worth noting Stock Advisor’s total average return is 875% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
Anthony Di Pizio has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Amazon, Meta Platforms, and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


