


SK Hynix ADR Stock Price Forecast: Record Q3 Revenue Drives 12% Rally, Technicals Signal Rise to $173
TradingKey - On October 28 Eastern Time, SK Hynix (SKHY) surged 12% after releasing its third-quarter financial report. Record revenue and operating profit, coupled with a shareholder return plan that exceeded market expectations, drove investors to re-evaluate its earnings growth and cash return capabilities.
In the third quarter, the company reported revenue of 104.62 trillion Korean won and an operating profit of 83.33 trillion Korean won, up 32% and 38% quarter-on-quarter, respectively, with an operating margin of 79.7%. According to JPMorgan, these two metrics were 7% and 9% above market consensus, respectively.
The beat was mainly driven by memory price hikes and an improved product mix. DRAM average selling prices (ASPs) rose nearly 30% quarter-on-quarter, while NAND rose about 25%, both exceeding JPMorgan's forecasts. Citi pointed out that server DDR5 shipments grew by over 40% quarter-on-quarter, while NAND shifted toward high-value products, supporting profitability gains.
Strong operational performance also translated into shareholder returns. JPMorgan stated that the company's 2026 shareholder return plan reaches 100 trillion Korean won, significantly higher than the market consensus of around 40 trillion Korean won, serving as another catalyst boosting the stock price.
Growth expectations also provided support for the stock price. Long-term agreements signed with 14 customers cover over half of the company's capacity for 2027 and 2028, enhancing demand visibility. Citi raised its fourth-quarter operating profit forecast from 89.8 trillion to 107 trillion Korean won, while Wedbush raised its price target from 2.56 million to 3.00 million Korean won, maintaining an "Outperform" rating.
However, foreign exchange and investment valuation losses caused third-quarter net profit to fall below expectations. The market's positive reaction focused more on core business earnings exceeding expectations, long-term contracts supporting future demand, and a larger shareholder return plan.
From a technical perspective, following today's sharp rise, SK Hynix is approaching the 0.5 Fibonacci retracement level around $165.32. The current move represents a gap-up recovery after a sharp drop, with short-term momentum strengthening noticeably.
Looking at the trend, after repeatedly pushing higher in the high-level zone from September to early October, the stock failed to sustain its advance and subsequently fell continuously until beginning to recover near $130.79. Lows of the recent candlesticks have gradually shifted upward, and this gap-up open expanded the rebound, indicating that short-term price action has progressed from a low-level bottoming attempt to filling the previous breakdown zone.
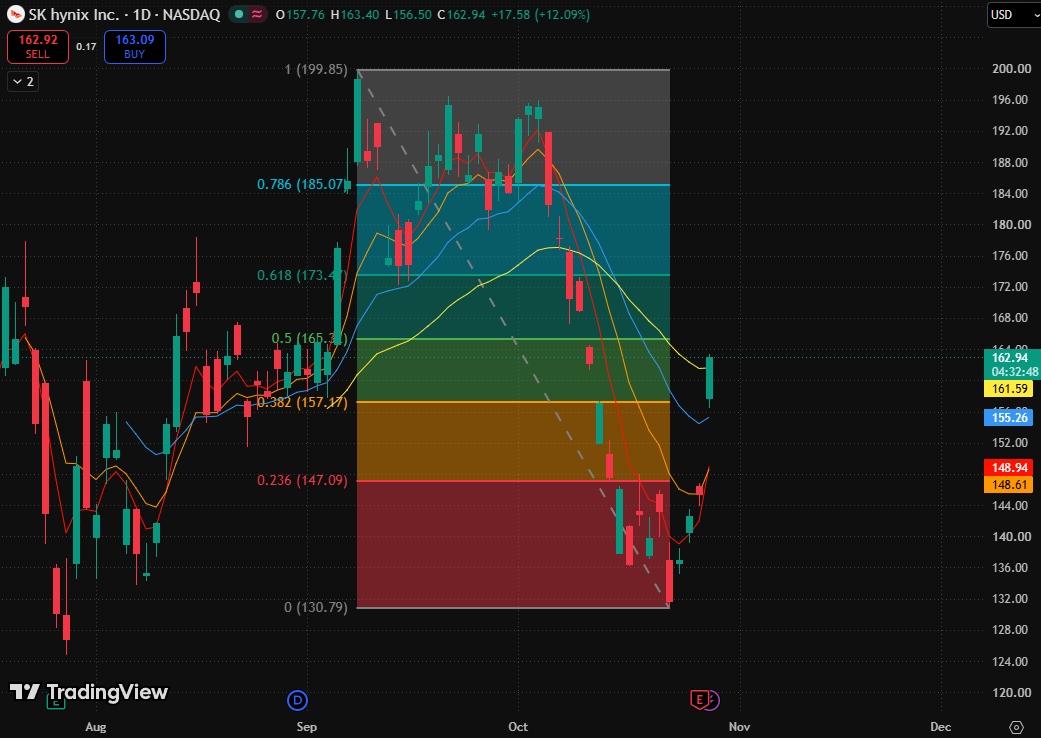
SK Hynix ADR daily chart, Source: TradingView
On the upside, immediate resistance is seen at the 0.5 Fibonacci retracement ($165). A successful breakthrough would point to the 0.618 retracement level ($173), with further resistance at the 0.786 Fibonacci retracement level ($185.07).
The biggest downside risk is that the newly reclaimed key moving averages fail to convert into support, leading to a retest of the first confluence zone (the range between the 0.382 Fibonacci retracement and the 20-day exponential moving average), which would downgrade this strong rebound into a brief recovery within a downtrend, redirecting prices toward the second moving average cluster.
Recommended Articles


