


Amazon or Alphabet: If I Could Only Own One for the Next Decade, It Would Be This One
Key Points
Alphabet's cloud business is growing faster than Amazon’s.
Alphabet also boasts a higher-margin business than its tech peer.
Both are reasonably valued at current levels.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Amazon (NASDAQ: AMZN) and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) are two companies that hardly need an introduction. Both are leaders in their respective industries, generally post excellent financial results, and have crushed broader equities over the long run. Investors arguably can't go wrong with either of these, and I personally own shares of both. But if I had to pick just one to own for the next decade, it would likely be Alphabet. Here's why.
Image source: The Motley Fool.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The AI tailwind could favor Alphabet
Over the next 10 years, the cloud computing and artificial intelligence (AI) industries will likely continue growing. Amazon and Alphabet, two leaders in these markets, are both likely to capitalize. What separates the two companies? Let's start with Amazon. The company's cloud segment, Amazon Web Services (AWS), boasts the largest market share.
Amazon offers perhaps the largest library of services among the Big Three in the cloud computing industry. However, Alphabet is particularly competitive in the AI niche of the cloud market. Alphabet's cloud sales have been growing faster in recent quarters. During the second quarter, Google Cloud's revenue soared by 82% year over year to $24.8 billion. Alphabet's total revenue jumped by 24% year over year to $119.8 billion.
By contrast, Amazon's total revenue increased 20% year over year to $200.6 billion, with AWS cloud sales jumping 37% year over year to $42.2 billion. One reason I'd pick Alphabet over Amazon right now is the former's strength in AI. Despite fears that the AI bubble will burst, spending on the technology continues to rise, and we are arguably just entering the era of agentic AI systems.
There is at least some evidence that demand for agentic AI is there. Meta Platforms (NASDAQ: META) launched one of the first consumer-facing AI agents in September, and it has been hugely successful so far. Corporations are also extensively using AI agents. And as more of them are developed, demand for precisely the sort of services that Alphabet and Amazon offer should continue to rise. All that to say, bullish long-term projections about AI infrastructure spending appear justified, and Alphabet is in a particularly strong position to capitalize on that.
Margins matter
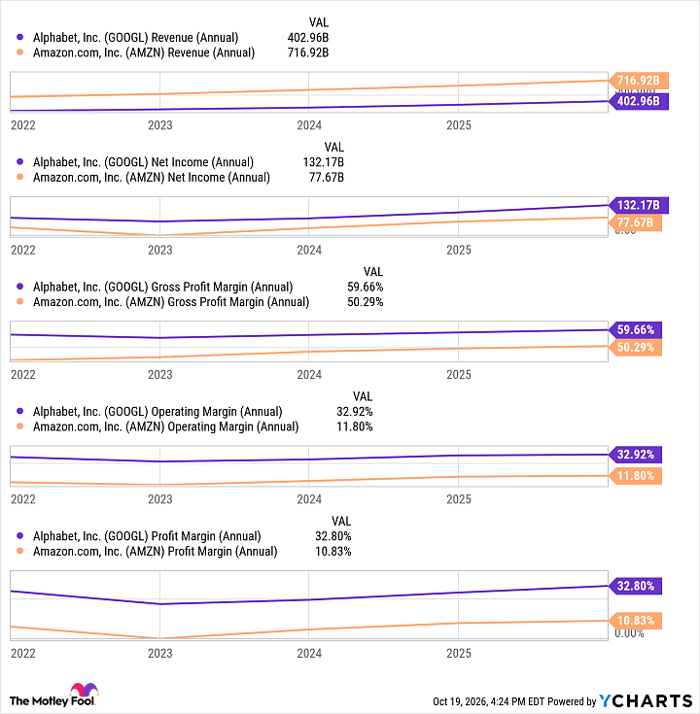
What if we look at the rest of their businesses? Amazon's is larger, at least in terms of sales. But Alphabet has an advantage. Its business carries much higher margins. That's not surprising. Alphabet makes most of its money from digital ads (Amazon's ad business is much smaller than Alphabet's). Once the advertising infrastructure is up and running, the cost of showing one additional ad is small. Meanwhile, Amazon's core e-commerce business is a famously low-margin operation.
In fairness, the company is looking to improve on that front, and in my view, it will succeed. Amazon has launched AI-powered robots in its warehouses to help streamline the packaging and shipping process. That's one of the initiatives the company has implemented to improve e-commerce margins. Still, for now, Alphabet has a clear advantage in this category.
As a result, despite generating lower sales, Alphabet typically records higher profits.
GOOGL Revenue (Annual) data by YCharts
E-commerce and digital advertising are both industries with attractive long-term growth prospects, and given their wide moats, Amazon and Alphabet are likely to remain leaders in their respective markets. Over the long run, Alphabet's earnings could remain higher than Amazon's due to its higher-margin core business.
What about valuation?
Even with its fast-growing cloud business, strong margins, high profits, and attractive long-term prospects, Alphabet appears to be reasonably valued. The company is trading at 21.8x forward earnings. True, that's a bit higher than the 19.1x average for information technology stocks, but Alphabet is worth a premium considering the strength of its business.
Amazon also looks attractively valued. It is trading at 23.6x forward earnings, compared to the 23.3x average for consumer discretionary stocks. Perhaps if Amazon were deeply undervalued relative to its growth potential -- and by comparison with Alphabet -- it'd be the better stock to buy today. But that's not the case. It's another reason why I'd choose Alphabet, but again, that's only if I absolutely had to pick one of them. I'd advise investors to buy shares of both companies.
Should you buy stock in Alphabet right now?
Before you buy stock in Alphabet, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Alphabet wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $370,440!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,330,110!*
Now, it’s worth noting Stock Advisor’s total average return is 924% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 21, 2026.
Prosper Junior Bakiny has positions in Alphabet, Amazon, and Meta Platforms. The Motley Fool has positions in and recommends Alphabet, Amazon, and Meta Platforms. The Motley Fool has a disclosure policy.
Recommended Articles


