


CoreWeave's 15% Bond Yield Is Not a Neocloud Problem. Here's Why I'm Buying Neocloud Stock Dips.
Key Points
CoreWeave's bond yields went up to 15%, which will make refinancing its debt more expensive, and its 0.46 current ratio means some of that refinancing will have to happen soon.
In contrast to other neocloud platforms, CoreWeave does not own most of the property where its data centers are sited, nor the power supplies for them.
Nebius and Iren have much stronger balance sheets that are loaded with cash, and they can borrow against their data centers to secure low-interest loans in the future.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
CoreWeave (NASDAQ: CRWV) caused a panic in the neocloud trade after the yields on some of its bonds reached 15%. The high interest rates that investors are demanding to hold the company's current debt mean that it will be a lot more expensive for CoreWeave to borrow additional money for its future artificial intelligence (AI) infrastructure needs.
The neocloud provider's yields for bonds with 2032 maturity dates have been surging throughout the year. That reflects concerns about how much capital it will need to fund the AI data center build-outs, but this is actually more of a CoreWeave problem than a neocloud issue. Here's why I have been aggressively buying neocloud stocks amid the misunderstanding.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
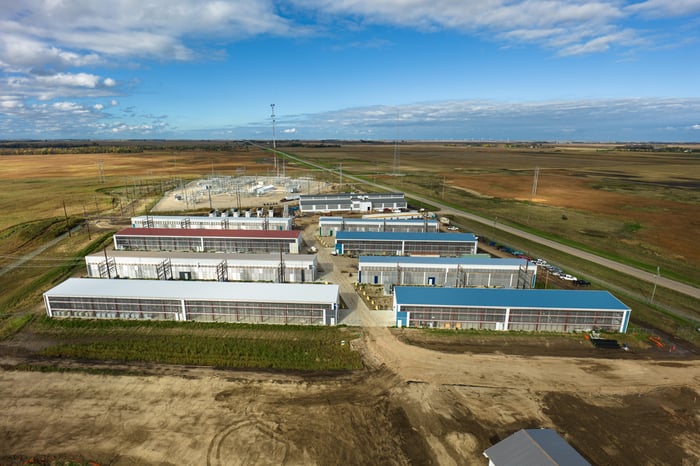
Image source: Getty Images.
CoreWeave has a different business model
When people think about neocloud stocks, they often think of CoreWeave, Nebius (NASDAQ: NBIS), and Iren (NASDAQ: IREN). Iren remains my favorite despite its lackluster year-to-date performance, and it shares many similarities with Nebius. However, there are key differences between those two and CoreWeave.
CoreWeave doesn't own all of its data centers. It uses a leasing model and brings its GPUs to prebuilt data centers. That means CoreWeave does not own the land or power for these facilities. As its land and power costs go up, it will face margin pressure. Granted, the value of each megawatt of compute it offers may continue to climb, which would mitigate its rising costs, but those costs are problems Nebius and Iren don't have to worry about.
Those two companies have made a point of owning their land and power. That helps them keep costs low as revenue increases. It also gives them additional funding sources. Iren and Nebius can eventually borrow against their data centers to get low-rate loans if needed; CoreWeave doesn't have that option. All three companies also use GPU-based financing to essentially borrow against the AI chips they buy.
CoreWeave's balance sheet is filled with risk
CoreWeave's revenue more than doubled year over year to $2.58 billion in the second quarter, but that impressive growth rate hides some serious financial risks. For instance, the company has $5.5 billion in cash against $20.9 billion in total current liabilities. Its net losses also more than doubled year over year.
CoreWeave also has a lot of debt coming due, including $10.6 billion by the end of 2027. In the meantime, the company paid $640 million in interest in the second quarter, which was much more than its $49 million net operating loss.
Iren and Nebius are also borrowing money to fund their data center build-outs, but they have much cleaner balance sheets. CoreWeave's current ratio -- a metric that weighs current assets against current liabilities -- stood at a dangerously low 0.46, further fueling refinancing worries. Nebius and Iren have deeper cash positions, resulting in current ratios of 3.08 and 3.55, respectively.
It's no wonder CoreWeave is facing higher interest rates. Its finances are catching up to it faster than to Iren and Nebius, which have secured low-rate financing using debt instruments that won't mature for years. Furthermore, Iren and Nebius haven't borrowed against their data centers yet. Iren CEO Dan Roberts hinted that his company might use data center financing to cover some of its capex requirements in 2027, which could spare it from having to issue high-yield bonds or engage in dilutive equity sales.
In summary, CoreWeave is in a more desperate financial situation and has fewer financing options.
The biggest winners will be the surviving neoclouds
Iren and Nebius are built to withstand the current turbulence. They have good balance sheets, multiple ways to access capital without paying high rates, and surging revenue growth. While CoreWeave has a $104.2 billion backlog, it will take years for all of that revenue to be realized. That backlog also limits CoreWeave's beneficial exposure to rising values for compute since most of the capacity it's building is already allocated to hyperscalers, AI labs, and other companies.
The fact that CoreWeave is struggling with high interest rates and looming bond maturities shows that the landscape can be challenging even for established neoclouds. In this environment, it will be even more difficult for new neocloud platforms to stand out and gain momentum. The few that are rapidly gaining market share may separate themselves from the competition by vast distances.
Nebius and Iren may end up with market positions in the neocloud industry similar to those that Amazon, Microsoft, and Alphabet enjoy in cloud computing. There are other cloud providers, but between them, those three hold more than 60% of the market. Iren and Nebius may find themselves in the same positions in the AI neocloud niche because of their technology, strong balance sheets, and long-term AI tailwinds.
Should you buy stock in CoreWeave right now?
Before you buy stock in CoreWeave, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and CoreWeave wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $380,363!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,315,732!*
Now, it’s worth noting Stock Advisor’s total average return is 919% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 18, 2026.
Marc Guberti has positions in Iren. The Motley Fool has positions in and recommends Alphabet, Amazon, and Microsoft. The Motley Fool has a disclosure policy.
Recommended Articles


