


PepsiCo vs. Starbucks: Which Consumer Goods Stock Is a Better Buy for 2027?
Key Points
PepsiCo offers a highly diversified portfolio of global snacks and drinks with strong retail ties.
Starbucks maintains a massive global coffeehouse footprint and a premium brand loyalty program.
Which beverage giant is the better long-term play for your portfolio through 2027?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Investors choosing between PepsiCo (NASDAQ:PEP) and Starbucks (NASDAQ:SBUX) must weigh steady snack-and-sip diversification against premium coffee growth. Both brands dominate their niches, but different economic tailwinds will likely determine the winner in 2027.
PepsiCo uses a massive snack and drink catalog to capture reliable shelf space globally. Starbucks focuses on premium retail experiences and beverage innovation in 88 markets. Comparing their cash flow and valuation metrics helps determine which giant offers more value over the next few years.
The case for PepsiCo
PepsiCo sells a variety of snacks and beverages to wholesale distributors, retail chains, and foodservice operators. Its largest customer is Walmart (NASDAQ:WMT), which accounted for approximately 14% of revenue in 2025. Customer concentration like this adds a layer of risk to the business, though long-term deals with partners like Yum! Brands (NYSE:YUM) provide a stable foundation.
In the 12 months ended Sept. 5, 2026, revenue reached nearly $98.2 billion, an increase of roughly 6.4%. Net income reached approximately $10.9 billion. This performance suggests a steady trajectory for its diversified portfolio of beverage and snack categories.
As of Pepsi's December 2025 balance sheet, the debt-to-equity ratio, which measures total debt against the value of assets owned by shareholders, was nearly 2.4. The current ratio reached approximately 0.9. This metric indicates the company's ability to cover its short-term debt with assets like cash and inventory. In the fiscal year ended Dec. 27, 2025, free cash flow was close to $7.7 billion, representing the cash remaining after covering all operating and capital investments.
The case for Starbucks
Starbucks operates thousands of coffeehouses and sells packaged coffee through a global alliance with Nestlé (OTC:NSRGF). The business depends on a loyal customer base for its company-operated stores and regional licensed partners. This model prioritizes the coffeehouse experience for millions of daily visitors while expanding through partnerships in ready-to-drink beverages.
In the 12 months ended Sept. 27, 2026, revenue reached nearly $37.9 billion, representing growth of roughly 1.9%. Net income was approximately $2.5 billion. While revenue growth was modest, the company managed to maintain a net margin of close to 6.7% as it navigated shifting consumer habits.
As of Starbucks' September 2026 balance sheet, the debt-to-equity ratio was roughly -2.9, which means total liabilities exceed shareholder equity. Its current ratio was close to 0.8. In the fiscal year ended Sept. 27, 2026, free cash flow reached nearly $3.7 billion.
Risk profile comparison
PepsiCo faces risks from evolving consumer preferences, including the adoption of GLP-1 weight-loss medications, which may curb snack demand. The company is also exposed to significant competition from Coca-Cola (NYSE:KO) and various private-label brands. Geopolitical instability and water scarcity in manufacturing regions further complicate the long-term outlook for its global operations.
Starbucks must manage the volatility of high-quality coffee prices and macroeconomic downturns that affect discretionary consumer spending. The company is currently subject to operational risks related to managing its global workforce, including unionization efforts at coffeehouses in the U.S. Additionally, Starbucks faces the challenge of successfully implementing its restructuring strategy to drive future growth.
Valuation comparison
PepsiCo offers a significantly lower entry point based on its future earnings estimates and sales multiples compared to the higher valuation currently assigned to Starbucks.
| Metric | PepsiCo | Starbucks |
|---|---|---|
| Forward P/E | 16.6 | 32.4 |
| P/S ratio | 1.9 | 3.1 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
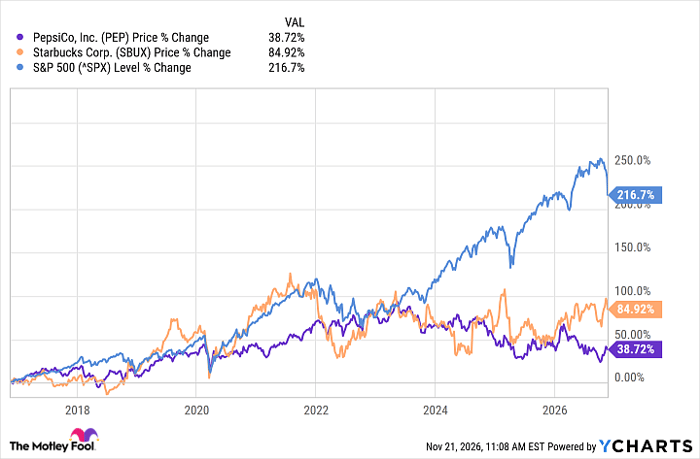
I think fundamentally PepsiCo is not a stock you buy in hopes of staggering gains. Indeed, both Pepsi and Starbucks have trailed the S&P 500 (SNPINDEX:^GSPC) over the past decade:
PEP data by YCharts
The soda giant didn't even keep pace with inflation. Pepsi is a mature, established company, and its main attraction is likely its dividend, which yields about 4.2%. So I could see the appeal for conservative investors.
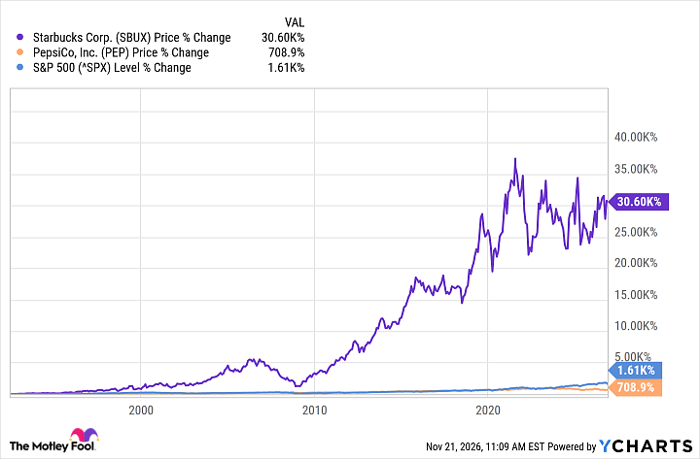
Now, zooming out a bit, Starbucks' long-term performance is a lot more impressive:
SBUX data by YCharts
But that was then, and this is now. Revenue growth of 1.9% is uninspiring, to say the least.
I don't find either of these stocks especially attractive, but I think, to paraphrase Warren Buffett, PepsiCo could be run by a ham sandwich and be just fine. Plus, it's a Dividend King, having raised its annual dividend for more than 50 straight years. I'd prefer more growth, but I'll settle for a Steady Eddie. PepsiCo gets my vote for 2027 and beyond.
Should you buy stock in PepsiCo right now?
Before you buy stock in PepsiCo, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and PepsiCo wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $305,941!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $771,325!*
Now, it’s worth noting Stock Advisor’s total average return is 719% — a market-crushing outperformance compared to 192% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 22, 2026.
Erin Kennedy has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Starbucks and Walmart. The Motley Fool recommends Nestlé and Yum! Brands. The Motley Fool has a disclosure policy.
Recommended Articles


