


ASML vs. Broadcom: Which Tech Stock Is a Better Buy for 2027?
Key Points
ASML maintains a unique monopoly on the advanced machinery necessary to manufacture high-end semiconductors.
Broadcom continues to dominate the networking and infrastructure software markets with high profitability.
Which chip industry powerhouse is the superior choice for your long-term portfolio?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
The semiconductor world is currently split between the machines that build chips and the designs that power them. Is ASML (NASDAQ:ASML) or Broadcom (NASDAQ:AVGO) the better play for your portfolio?
ASML holds a virtual monopoly on the advanced lithography machinery required to print the world's most sophisticated microchips. Meanwhile, Broadcom has evolved into a powerhouse of networking components and enterprise software. Both companies are critical to the tech supply chain, but they offer distinct paths for investors seeking exposure to high-end silicon.
The case for ASML
ASML manufactures lithography systems, which are massive machines that use light to print intricate patterns onto silicon wafers. It provides the essential hardware for every major chipmaker to produce smaller, faster, and more efficient processors. Because its technology is unique, it serves as a critical gatekeeper for the entire high-end semiconductor market.
In the 12 months ended Sept. 30, 2026, revenue reached nearly $43.4 billion, an increase of roughly 22.5%. The company generated approximately $14.8 billion in net income. This growth highlights the sustained demand for extreme ultraviolet lithography systems used in advanced chip production for artificial intelligence and high-performance computing.
As of ASML's December 2025 balance sheet, the current ratio, which measures a company's ability to cover its short-term debts with short-term assets, is approximately 1.3. The debt-to-equity ratio is roughly 0.2, showing that the company uses relatively little debt compared to its total equity. In the fiscal year ended Dec. 31, 2025, free cash flow was close to $12.2 billion.
The case for Broadcom
Broadcom is a dominant player among semiconductor stocks, providing infrastructure software and hardware solutions to global enterprises. The company has significant customer concentration, with its top five end customers accounting for roughly 40% of revenue in its latest annual report. Customer concentration like this adds a layer of risk to the business, as evidenced by a $30 billion commitment from Apple (NASDAQ:AAPL).
In the 12 months ended Aug. 2, 2026, revenue reached close to $89.1 billion, representing significant growth of nearly 48.7%. The company reported net income of approximately $38.3 billion during this time frame. This surge was partly driven by the integration of large acquisitions and booming demand for artificial intelligence infrastructure across data centers.
As of Broadcom's November 2025 balance sheet, the current ratio is roughly 1.7. The debt-to-equity ratio is approximately 0.8, indicating a higher level of total debt relative to shareholder equity than ASML. In the fiscal year ended Nov. 2, 2025, free cash flow was close to $26.9 billion, though stock-based compensation accounted for roughly 27.5% of operating cash flow, inflating reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
Risk profile comparison
ASML faces risks from its position at the center of global trade tensions, particularly concerning international export restrictions. The company also operates in the cyclical semiconductor equipment market, where spending by chipmakers can fluctuate based on broader economic conditions and interest rates. Furthermore, the rapid pace of innovation requires constant, heavy investment in research and development to maintain its technological lead over any potential competitors.
Broadcom operates in a highly cyclical industry that faces rapid price erosion and evolving technological requirements driven by artificial intelligence. It relies heavily on a limited number of contract manufacturers, such as Taiwan Semiconductor Manufacturing Company (NYSE:TSM), which produced approximately 95% of its wafers according to its latest annual report. Broadcom also faces intense regulatory scrutiny and risks associated with its strategy of integrating large acquisitions into its software portfolio.
Valuation comparison
Broadcom looks potentially cheaper based on its forward P/E, which compares the stock price to future earnings estimates, whereas ASML has a lower P/S ratio.
| Metric | ASML | Broadcom |
|---|---|---|
| Forward P/E | 29.9 | 17.9 |
| P/S ratio | 12.1 | 18.6 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
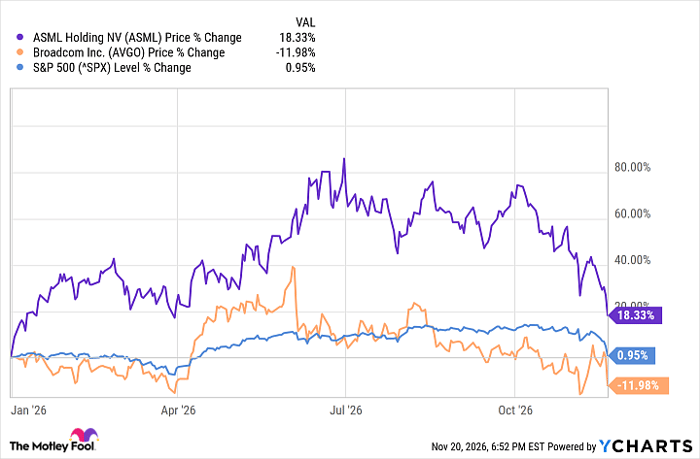
The current market environment is, shall we say, hostile to tech stocks, and shares of ASML and Broadcom reflect that:
ASML data by YCharts
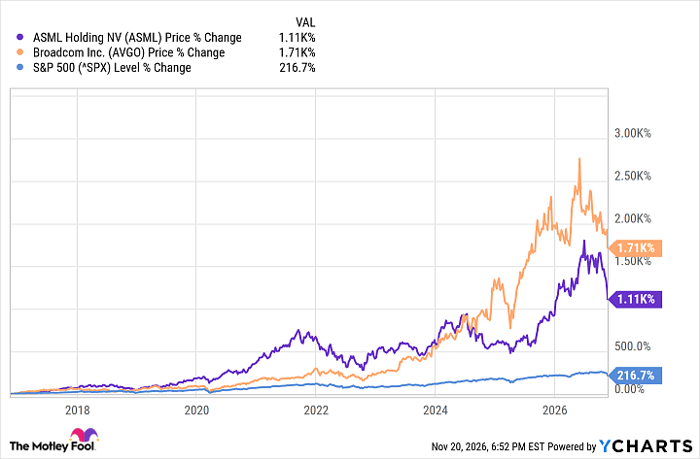
That said, zooming out over the past decade, both stocks have put in decent performances, handily outpacing the S&P 500's (SNPINDEX:^GSPC) return:
ASML data by YCharts
In the past, I have picked ASML over many other stocks for several reasons. For one, it has a monopoly in the extreme ultraviolet lithography niche it operates in. That gives it strong pricing power and a solid moat. ASML also consistently reports a net margin in excess of 30%, and it pays a modest dividend.
However, it's hard to argue with Broadcom's long-term performance. A company of that size reporting nearly 50% revenue growth is pretty wild. ASML and Broadcom are both exposed to the inherent cyclicality of the semiconductor industry, so I think that risk factor offsets itself. And the tech sector (and the market in general) may be melting down right now, but long-term investors shouldn't get especially concerned over what happens in the course of a week, or a month, or even a year.
I'm breaking with my pattern here. I don't think ASML is a bad choice, to be clear, but Broadcom has strong margins and even better revenue growth. Broadcom gets my vote for 2027 and beyond.
Should you buy stock in ASML right now?
Before you buy stock in ASML, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and ASML wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $305,941!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $771,325!*
Now, it’s worth noting Stock Advisor’s total average return is 719% — a market-crushing outperformance compared to 192% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 21, 2026.
Erin Kennedy has positions in Apple and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends ASML, Apple, Broadcom, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


