


Micron Has Plunged 36% From Its Peak. Here’s the Price at Which I’d Buy.
Key Points
Micron Technology stock has slipped substantially from its 52-week high, and its valuation suggests now is a good time to buy.
Memory supply won't be catching up to demand any time soon, and that could help Micron outperform expectations.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Micron Technology (NASDAQ:MU) investors have endured a rough time in recent months, as shares have pulled back nearly 36% from their June 25 peak, when the stock reached a 52-week high.
Though Micron stock regained some momentum in August and September, the past one and a half months have again been quite brutal. The semiconductor specialist has lost 29% of its value during this period. Each share of Micron now trades at just under $800, as of this writing.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, looking at the share price in isolation isn't the right way to value a stock. We will have to take a closer look at Micron's valuation and growth to decide if it is worth buying following its recent slide.
Image source: Micron.
The valuation clearly tells investors to buy Micron hand over fist
Micron has a price-to-earnings ratio of 11, and its forward earnings multiple of 4.4 is even more attractive. The stock's price-to-sales ratio is just under 7. For comparison, the tech-focused Nasdaq Composite index trades at 39 times earnings and 5 times sales.
The pace of Micron's growth makes it clear that it is too cheap to ignore right now. The artificial intelligence (AI)-driven memory demand has supercharged Micron's growth, leading to exponential growth in revenue and earnings in recent years.
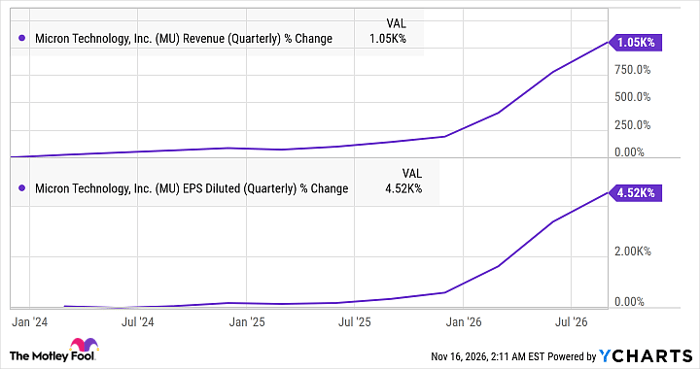
MU Revenue (Quarterly) data by YCharts
Importantly, the company can keep growing at a solid pace in the future amid tightening memory supply. Dell Technologies CEO Michael Dell recently noted that memory constraints could last until 2030, driven by strong AI demand outpacing supply. In fact, Dell isn't the only one who thinks so. Micron's rival SK Hynix also expects the memory shortage to last until the end of the decade, while Taiwanese memory manufacturer TeamGroup also sees memory supply tightening next year.
Semiconductor manufacturing equipment provider ASML Holding, which is witnessing terrific growth in the memory segment, noted recently that it won't be able to meet demand for its chipmaking equipment for the next couple of years. As such, I won't be surprised to see Micron sustain its healthy earnings-per-share growth beyond 2027.
Analysts are predicting a 134% increase in Micron's earnings in fiscal 2027 (which will begin later this month). However, they expect significantly slower growth of 17% in fiscal 2028, which is unlikely. That's because the memory shortage could continue pushing up prices and drive a stronger-than-expected increase in Micron's revenue, which will eventually result in a healthier bottom-line performance compared to analysts' expectations.
Here's why I'd consider buying the stock now
If I had $800 in investable cash right now, I would consider buying a share of Micron given its attractive valuation and favorable memory market dynamics. The stock's recent pullback isn't justified given its phenomenal growth and sunny outlook, which helps explain why it is now trading at such attractive multiples.
Even Wall Street is bullish about Micron's trajectory over the coming year. Almost all of the 55 analysts covering Micron rate it as a buy with a 12-month median price target of $1,575, according to CNN. That points to a potential gain of just over 100% in just one year, suggesting that Micron is capable of making a parabolic move.
So, investors can consider buying this AI stock right away given its incredibly attractive valuation and red-hot growth rate that seems sustainable.
Should you buy stock in Micron Technology right now?
Before you buy stock in Micron Technology, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Micron Technology wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 17, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends ASML and Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


